

Value investor. Bird appreciator.
Tel Aviv
Joined April 2025
- Tweets1.4K
- Following325
- Followers230
- Likes16.7K




Dean retweeted

Good analysis here on $PPL (held)
To be clear, I don’t believe this is a 10x bagger! But 99% of ASX stocks will never be one either
But, I do believe that 3.5-4x Ebitda (post todays move) is too cheap for this stock.
I do think there’s 100% upside next 12 months or so
And keep in mind most stocks have share based payments and capex so it’s all relative
6 years of strong growth is impressive!
I think one of the larger PE acquirers in the sector will come for them soon enough
👇👇👇


Dean retweeted

$ANT Anthropic is making $ 250bn+ non-cancellable compute commitments with Google, Amazon, and Microsoft through 2033, and semis trade like we are about to drive off a cliff next year


Dean retweeted
Bloomberg - European Gas Hits €97 for First Time Since 2022 on Winter Risks - bloomberg.com/news/articles/…

Dean retweeted
Pureprofile $PPL (held)
Strong guidance !!
Double digit sales growth and expanding margins 🔥
$8-$9m ebitda for FY27 and should finish year circa $5-$6m net cash 💰
EV at current prices is $24m so on 3x EV/Ebitda whilst compounding earnings and revenue at 20% pa last 6 years 🤯🤯🤯
How is this not a 6 cent stock ???!?
We think someone acquires them sooner rather than later 👀
👇👇👇


Dean retweeted

Very well written fund letter why AI is not fully displacing humans any time soon.
Have heard this from fundamental investors as well as quants. Especially about the velocity of idea (or signal) generation vs finite time for human review.

Dean retweeted

GMS $GMS.L
Implied day rates are approaching a 10-year high🫣
Assuming historical cash conversion, we're generating +$50m/y FCF at steady state now, and +$90m/y three years out. Market cap ~$300m.
p/fcf ~6x
As deleveraging continues, we'll see a transfer of value from debt to equity holders. ✅


Oh Canada...

⏹️Will the diesel crisis get worse?
🔲Who benefited from the loss of Qatari LNG?
⏹️Why are tanker attacks in the Gulf intensifying, and what does that mean for oil prices?
🔲Will Trump’s $8 billion farmer support program offset the diesel crisis?
⏹️Is Trump’s plan to import Russian diesel legal—and does it matter?
⏹️Why is Trump waiving sanctions on Russian oil buyers?
🔲How are record tanker rates crushing Asian and European refiners?
⏹️Can the EU still block Arctic oil and gas development?
🔲Why is US power-grid strain becoming a year-round problem?
🔲Is the Northeast facing a real climate-policy revolt?
⏹️Will Trump’s plan to rehabilitate dark-fleet tankers actually increase oil supply?
🟥Daily Energy Report
Daily Energy Report
afalhajji.substack.com/p/dai…

Dean retweeted

$PVE Executive Chairman and CEO Kevin Bailey joined @MSTFinancial’s Oil & Gas International Exposure Series.
Watch the full replay on our investor hub 👇 povalley.com/activity-update…
#PVE

Despite widespread rioting, an upcoming winter, low storage levels, and natgas prices already at triple their pre-hormuz level, the EU is still committed to the Russian LNG ban taking effect this coming January
Risky but you gotta respect it
$PVE.AX
forbes.com/sites/marktemnyck…


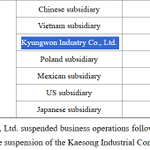
An interesting find. You comb through the filings of a random SK company and you find out they have an inactive overseas subsidiary in North Korea.


Dean retweeted
I have a better idea
$RIG


Lego Maersk Duel-Fuel Container Vessel revealed!
1516 Pieces / $149.99 / 1st March 2026
#Lego #Legonews #Legoleaks

Dean retweeted

RIG's new amended RCF keeps RP leverage and liquidity thresholds unchanged, but with some looser terms adding shareholder-return flexibility
The key dividend driver is VAL merger accelerates deleveraging at close and over the next 12 months as three 7G drillships return to work
- From 5.5x net leverage at YE24, Transocean has deleveraged to ~3x currently, mostly due to converting backlog into cash for debt reduction. The deleveraging aspect of the all-stock merger is key for Transocean; incorporating Valaris’ balance sheet (currently ~1.3x net leverage) should reduce net leverage to ~2.5x at close, with a visible path to ~2.0x by 2Q27.
- After Transocean delivered Atlas, Titan and Aquila (acquired) in 2022-2023, capex has materially declined to maintenance, modest upgrades and SPS levels, which supports meaningful free cash flow (OCF-Capex) averaging ~$180mm per quarter since 2024. The organic deleveraging is likely to continue, which makes underwriting 2x net leverage (covenant definition) by 2Q27 reasonable.
- Further, Valaris’ TTM EBITDA of $424mm represents a cyclical trough, depressed by idle (warm) rigs in TTM period. Operating leverage turns positive over the next 12 months as 7G drillships DS-10 (June 2026), DS-15 (Sept 2026) and DS-18 (4Q26) return to work. Activations are likely to draw on working capital initially, but EBITDA growth is clear, with cash flow to follow.
Transocean avoided this drag because due to its Norway-eligible harsh-environment semisub fleet, a market in which Valaris has no exposure. Valaris’ 7G drillships were hit by delays in West Africa during 2025 but are now scheduled to recover. The combined company has a more diversified fleet, which should lower its cost of capital, all else equal.
- The Net Leverage calculation in Transocean’s RCF credit agreement excludes the $286mm of Restricted Cash on its 6/30/2026 balance sheet. Restricted cash consists largely of Debt Service Reserve Accounts funding the next 12 months of amortization and interest on Transocean’s secured bonds. These funds are structurally dedicated to secured bondholders, not the bank group on Transocean’s revolver so are excluded from its net leverage calculation.
- Transocean’s repayment of its Poseidon, Titan and now Aquila secured bonds both reduces debt and releases restricted cash, which receives no credit under the revolver’s net leverage covenant. The 2030 secured notes had $822mm outstanding at 6/30/26, falling to ~$763mm after the August paydown. With the call premium stepping down from 104.375 to 102.188 in February 2027, a refinancing into unsecureds is logical; eliminating $117.5mm of annual amortization could fund a larger dividend program, though is subject to Board capital allocation policy...

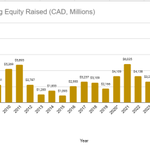
TSX-V equity raises in the mining sector are again at a new all-time high on a TTM basis after 824m CAD (+40% y/y) was raised in September
$OGD.TO $FAR.TO $GEO.TO $MDI.TO


Dean retweeted

A couple years ago there were so many ppl on here excited about deepwater consolidation, yet now consolidation has reached its blue sky outcome and few seem to care.
I view these assets effectively as permanent holds at this point, or at the very least holds until values begin to approach replacement cost. Hard to overstate how much having 80% of supply in the hands of 3 players transforms the industry dynamics for the better. $RIG $NE $SDRL

