

clear pilled but still feeding ▀ Fomocraft Trader ▀
Joined June 2019
- Tweets468
- Following1.5K
- Followers954
- Likes925





Pinned Tweet
Meta ruined my life.
The layoffs also laid off my metaverse illusion, along with my 0 valueNFTs.
As an absolute OG, I remember the raw electricity of the onchain metaverse era.
Pure vibes. Real ALPHA.
In 2019, I watched the Dogecoin Center rise in @cryptovoxels,
raising funds to send $DOGE to Mars and attempting to contact @elonmusk ,
long before he ever tweeted about it. (fig 1,2)
The seeds of the DOGE-1 Mission in 2025 were planted right there.
Back then, we built the first onchain gallery for Autoglyphs,
when they were still trading at 1 ETH.
I was the architect behind it.
Years later, those same works sold in bundles at ~500 ETH each. (fig 3)
I also designed one of the largest crypto art galleries in @decentraland, hosting exhibitions to give digital artists real visibility. (fig 4)
We genuinely believed this was the future, a real path to blockchain mass adoption.
Then the pandemic hit, everyone rushed from atoms to pixels.
The niche went mainstream, the suits arrived.
OpenSea was the OpenAI of its time.
And the moment Facebook rebranded to Meta marked the absolute top.
Then came the collapse.
They came for the hype, took the profits,
and left us with the ruins.
Every niche that goes mainstream pays this price.
History doesn’t repeat but it rhymes.
And right now, the echoes are deafening.
So, Zuck, do me a favor:
please give me a heads-up before your next rebrand.
I really need to exit my positions first.
Thanks.


ai的本质是消灭误差的拟合收敛,但是进化靠的是异常/错误. 一个不出错的自洽系统无法进化,恰恰是人类那些笨拙的偏见与意外,才是系统跳出局部最优、发生“基因突变”的唯一机会。

人是 AI 世界的随机数发生器
人在未来 AI 世界中的一个重要角色,就是充当随机数发生器。
AI 可以无限地生成内容、推演逻辑、优化结果,甚至不需要人参与,也能持续运转下去。但如果一切都只是 AI 自己生成、自己反馈、自己迭代,那么这个世界可能逐渐陷入某种自我循环,虽然高效,却缺乏真正的生命力。
而人的参与,会为这个系统带来新的变量。
人的经历、情绪、好奇心、突发奇想,以及与真实世界的偶然相遇,都会产生不可预知的想法。这些想法进入 AI 系统,又被 AI 放大、延伸和创造,进而产生新的可能性。
人提供不确定性,AI 提供无限的生成与扩展能力。
但人的价值又不只是制造随机性,而是能够通过自己的体验、审美和价值判断,为生成的内容赋予意义。
因此,一个完全由 AI 自我循环构成的世界,可能非常庞大,却也可能单调而缺乏意义;而一个有人持续参与的 AI 世界,则可能因为不断涌入的真实体验、意外和独立意志,变得更加丰富、多元和充满生命力。
AI 负责拓展可能性的边界,人负责带来意外、选择方向,并赋予意义。
或许,AI 时代人最值得保留和发展的能力,恰恰是那些看似不够高效的东西:体验、好奇、探索、创造,以及独立思考。
lol retail paid the zcash:native premium in 2025, pros collected it and then took over the book in 2026. etf was just the announcement

coinbase never had pricing power on alts and in 2026 it's even getting worse 🫥
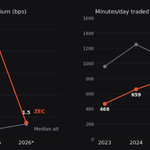
50 of the most traded alts on coinbase,not microcaps. % of minutes with 0 trades (21 – 22 utc):
2024: 14%
2025: 19%
2026: 51%
ETH, SOL, XRP still print every minute but everything below is going dark.

the August pump was borrowed but the $75K floor is earned.
went through the new @glassnode x @Bybit_Official derivatives report. here's the btc part read 👇
>btc ran +24.6% in 5 days while OI fell 12.6%, and 89% of liqs were shorts. the rally was shorts buying back, straight up.
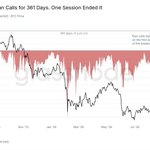
> options priced it as a one-off. puts had been rich for 361 days and flipped to calls in a single session. 1W IV ripped 80%. 6M IV stayed flat.
>a month later the event premium is gone. now skew's back to puts, DVOL's at 39, and btc gave back $81k → $75K.
> then the fed hiked for the first time since 2023, ETFs bled two days straight, and $75k held anyway.
🧐Shorts lit the fuse and spot is holding the floor.


Public arb pays 1 bp. Access pays 20.
I started with a boring question: how far do tokenized stocks drift from NAV, and how long before someone arbs it back?
The answer turned out to be less interesting than who gets to collect it.
Then I followed the money on-chain and the question changed.
AAPLx and NVDAx have been live ~14 months. Between them: 9 and 18 economically meaningful supply expansions, and essentially zero identifiable economic burns.
But in a single 3.5-month window on Solana, I rebuilt 10,663 xChange atomic settlements. Extend to Ethereum, Ink and Arbitrum and you get another 10,011 SwapExecuted events across 138 tickers, ~$18.55m notional.
That gap is the whole story:
> xChange "issue/redeem" doesn't mean a literal mint or burn. It's an atomic xStock↔stablecoin swap against Backed's inventory.
> So a flat totalSupply doesn't mean no primary flow. It means the same inventory is being recycled.
> The active players aren't a crowd of arbitrageurs fighting over basis. They're a handful of dealers with wholesale access, execution wallets, and a CEX inventory rail.
> Open AMM arb still exists. The observed gross edge is thin. The fatter money sits with order flow, primary access, and settlement 👇🧵(0/8)

SNDK: attention doesn't become on-chain depth
SNDK is the most useful counterexample in the sample. Crypto traders follow it, and its perp volume on CEXs ranks near the top. The tokenized spot never grew primary flow to match.
>93 xChange settlements
>4 supply expansions
>only 47 trades matchable to 5-min underlying data
>median implied deviation ≈ +30 bp — clearly worse than AAPLx and NVDAx
Thin tokenized spot, harder to price well.
The lesson: a name being popular in crypto doesn't mean its tokenized spot automatically gets depth. When the inventory rail, dealer quoting and secondary pools don't show up together, demand just stays on the CEX or in derivatives. It never settles into on-chain spot liquidity. (7/8)
xChange didn't kill arbitrage. It changed who gets to collect it.
In an RFQ market the dealer sees the user's order, NAV, its own inventory, and its primary cost — then quotes one price. Aggregators then price RFQ against AMM. A stale quote rarely stays exposed to outsiders for long, because the dealer has already merged pricing and hedging into a single execution path.
AMMs don't work like that. A pool prices passively along a curve. It doesn't know the underlying just moved, and it doesn't know xChange's wholesale quote. So user flow keeps creating the transient dislocations that 6ug cleans up.
Arb didn't disappear. It's just that in this sample, the visible space on public AMMs is thin and capped by pool depth.
9BB gets 15–20 bp because it holds the client entrance and the primary exit at the same time. 6nj's value is moving inventory into a CEX efficiently. And fully public AMM arbitrage? About 1 bp gross. (8/8)
headhunter friend says credit trader demand is picking up.
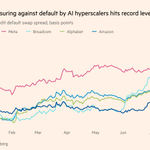
makes sense. seven of the big ai names hit record 5y cds this week. nvda at an all time high. meta's $12bn texas datacenter debt priced like B- paper, parent's still IG.
capex is eating free cash flow and credit noticed first. 🤔

lower highs🙄the grind base case is happening,all you need is patience

👀my read on 2026 H2 and how i'm positioned:
the base case for the second half is stepwise deleveraging from stretched highs, not an ai bubble collapse, but not a continuation of ai euphoria either.
the whole thing rests on one condition: credit stays intact.
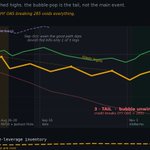
HY OAS is still low. the private credit behind the ai buildout is the real landmine, but it hasn't turned into a systemic credit event yet. as long as that holds, ai can grind at the top and bleed leverage on repeat.
what's got me leaning this way:
> leverage is still high. margin debt is at record highs, and SOXL still trades at a premium into selloffs.
> hawkish backdrop. this market already priced in cuts. so no cut IS the bad news. higher for longer welds the valuation ceiling shut.
> the fed got less legible. Warsh scrapped the rate roadmap, so every data print swings harder and the post event vol crush fades.
> geopolitical tail is back. hormuz and oil are re-entering the pricing, with crude bouncing off the lows.
net: an asymmetric tape. good news gets muted and bad news gets amplified.
two paths from here. i lean the FIRST.
1. grind lower in steps — base case
leverage never fully clears. small bounces, lower highs each time.
jul-aug bleeds. late aug, the jackson hole + NVDA window could trigger a short bounce. sep into early nov, seasonality stacks on top of more deleveraging.
post election early nov probably bounces, but the size depends on two things: did leverage actually clear, and did the fed actually pivot.
2. flush then new highs — the optimistic long shot
2024-H2 crypto style.
brutal setup though. both have to happen: a loud capitulation flush in jul-aug that wipes leverage clean, AND macro turning good with the fed going dovish.
line those up with post election seasonality and year-end highs are back on the table. but now the first condition isn't close yet.
the tail:
if private credit, ai data center financing, and HY OAS all start bleeding in one direction, that's not a correction anymore but the bubble unwinding.
how i'm positioned:
equities: 1/3 in spot. selling short-dated puts to leg into the stepdowns, using part of that premium to buy deep OTM puts as tail cover.
crypto: don't fight the tape. short the bounces while it's under the 200ma, but a fed pivot or liquidity turn is my stop.
the wildest sector on earth turning boring at the top, while the real risk hides in the debt nobody's marking daily. that's the whole setup.

🧐hyperscaler fcf going negative isn't a footnote. it's the whole story. that gap gets funded with debt. oracle's downgrade is the first invoice. watch the cds not the earnings.


👀my read on 2026 H2 and how i'm positioned:
the base case for the second half is stepwise deleveraging from stretched highs, not an ai bubble collapse, but not a continuation of ai euphoria either.
the whole thing rests on one condition: credit stays intact.
HY OAS is still low. the private credit behind the ai buildout is the real landmine, but it hasn't turned into a systemic credit event yet. as long as that holds, ai can grind at the top and bleed leverage on repeat.
what's got me leaning this way:
> leverage is still high. margin debt is at record highs, and SOXL still trades at a premium into selloffs.
> hawkish backdrop. this market already priced in cuts. so no cut IS the bad news. higher for longer welds the valuation ceiling shut.
> the fed got less legible. Warsh scrapped the rate roadmap, so every data print swings harder and the post event vol crush fades.
> geopolitical tail is back. hormuz and oil are re-entering the pricing, with crude bouncing off the lows.
net: an asymmetric tape. good news gets muted and bad news gets amplified.
two paths from here. i lean the FIRST.
1. grind lower in steps — base case
leverage never fully clears. small bounces, lower highs each time.
jul-aug bleeds. late aug, the jackson hole + NVDA window could trigger a short bounce. sep into early nov, seasonality stacks on top of more deleveraging.
post election early nov probably bounces, but the size depends on two things: did leverage actually clear, and did the fed actually pivot.
2. flush then new highs — the optimistic long shot
2024-H2 crypto style.
brutal setup though. both have to happen: a loud capitulation flush in jul-aug that wipes leverage clean, AND macro turning good with the fed going dovish.
line those up with post election seasonality and year-end highs are back on the table. but now the first condition isn't close yet.
the tail:
if private credit, ai data center financing, and HY OAS all start bleeding in one direction, that's not a correction anymore but the bubble unwinding.
how i'm positioned:
equities: 1/3 in spot. selling short-dated puts to leg into the stepdowns, using part of that premium to buy deep OTM puts as tail cover.
crypto: don't fight the tape. short the bounces while it's under the 200ma, but a fed pivot or liquidity turn is my stop.
the wildest sector on earth turning boring at the top, while the real risk hides in the debt nobody's marking daily. that's the whole setup.

meta renting out spare compute doesn't mean ai demand is topping.
meta's renting bc right now its own compute earns less run internally than it does rented to someone else. that's a margin call on utilization, not a demand call.
demand didn't change. what the market wants from compute did. it flipped from "how much do you own" to "how much profit do you squeeze out of what you own." the metric quietly moved from capacity to conversion.
here's the part that matters.
if more companies find they can't fully digest the compute they bought, "just stack more gpus" stops being an obvious trade. and the second the market stops rewarding raw capacity and starts pricing conversion, the commodity layer is the one that gets repriced first.

