

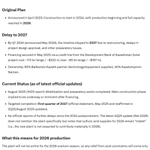






Kazatomprom $KAP have released a new 46-slide January 2026 Investor Handout📘⚛️⛏️🇰🇿 including this graphic showing #Kazakhstan's 2026 #Uranium production guidance, now forecast at ~73M lbs, about 12M lbs below their original plan of ~85M lbs this year✂️🤠🐂kazatomprom.kz/storage/c6/ka…


At the CIBC Whistler 2026 conference, Cameco’s Grant Isaac laid out a clear, high-level case for why he believes nuclear and uranium fundamentals are stronger than at any point in the modern cycle. For those who missed it, I just wanted to provide an overview of what was discussed. While I know that many of you will already have heard Grant talk about the subjects below on several occasions, including during the extensive interview that I did with him at the end of December, I still think it’s important to share those given the fundamental backdrop we are working with as we head into what will be an eventful year for the sector. Framed as a deliberately conservative view, the presentation focused on the growing disconnect between understated demand assumptions and overstated supply expectations across the nuclear fuel cycle.
On the demand side, Isaac emphasized that industry “base case” forecasts already show nuclear demand rising steadily, driven by reactor restarts, life extensions, power uprates, and more than 60 GW of reactors currently under construction. Importantly, he argued this consensus view materially understates reality. It excludes non-FID projects such as the announced US plan involving Westinghouse, Brookfield, Cameco, and the US government to build 10 large reactors, which alone would add roughly 65M lbs of uranium demand over a decade. It also excludes potential nuclear demand from data centers and AI, as well as naval propulsion, all of which compete for the same uranium, conversion, and enrichment services. Demand will continue to outperform expectations and the price expectations should adjust accordingly.
Against this backdrop, Isaac argued that the supply side is overstated and I couldn’t agree more. Primary supply assumptions treat licensed capacity as equivalent to actual production, even though both Cameco and Kazatomprom are operating with material curtailments due to price discipline. Secondary supply assumptions still embed Russian material, despite the effective bifurcation of Western and Russian markets. Planned production is also inflated by treating early-stage PEA timelines as reliable, despite the mining industry’s long history of delays. The result is a much larger effective supply gap than commonly depicted. This imbalance feeds directly into utility contracting dynamics. Isaac highlighted that uncovered utility requirements are now larger than at any point on record, a consequence of more than a decade of sub-replacement-rate contracting. In 2025, utilities contracted roughly 101M lbs while consuming around 190M lbs, with the difference met by inventory drawdowns and a few other levers that I have extensively discussed in the past (please see last year’s WNA report on my platform the Contrarian Codex for more details on utility behavior, conversations with fuel buyers, contracting strategy and much more). He stressed that uranium has no true “in-year” demand, as fuel is procured years in advance, making the long-term contracting cycle the key driver of price formation rather than spot activity and we have clearly seen a consistent and strong rise in price.
Isaac also addressed pricing mechanics, noting that the published long-term price of roughly $86/lb reflects only the minority of fixed-price contracts. About 70% of recent contracting has been market-related, with floors rising fast into the $80 level (with some reports noting that the $90 range for floors is also on the table in some capacity) and ceilings approaching the $150 range, implying an effective midpoint closer to $115. Historically, long-term prices gravitate toward those midpoints as contracting accelerates. Meanwhile, off-market activity continues as utilities increasingly realize that the pounds they may want to secure are not available in the same price point, location, volume nor timeframe that they have previously been able to secure supply at. Strategically, Cameco remains disciplined. The company intends to capture demand through market-related, long-dated contracts before ramping production, avoiding premature supply that would pressure spot markets. Isaac closed by underscoring Cameco’s vertically integrated position, spanning uranium mining, conversion, fuel fabrication, and reactor exposure through Westinghouse, which allows the company to participate in nuclear build decisions far earlier than traditional fuel suppliers. In his view, this integration uniquely positions Cameco to benefit as the next nuclear contracting cycle unfolds.
3
128
$yca production cut by KAP
Breaking!⚡️📰World's largest #Uranium miner Kazatomprom $KAP has released its 4Q25 and 2025 Full Year Operations and Trading Update, including its initial 2026 Production Guidance.🇰🇿⚛️⛏️🔮 #Kazakhstan's 2025 production was in line with midpoint of 2025 Guidance.✅
On 22 August 2025 $KAP announced a reduction to their 2026 Subsoil Use Agreements by -10% (-3,000tU) to 29,697tU (77.2M lbs)⬇️ and today they flexed down their 2026 Guidance to 5% below that SUA level to between 27,500 to 29,000tU, midpoint 28,250 tU (73.4M lbs) about -3.8M lbs below SUA.⬇️⛏️
They also include the warning: "The 2026 production guidance remains subject to sulphuric acid availability."⚠️🤠🐂
londonstockexchange.com/news…


I try to put myself in the mindset of a utility buyer who needs #uranium, has booked enrichment and fabrication services, knows there's an immenent 51m lb deficit, and still doesn't move. What exactly are these people thinking?
1
594


Uranium Outlook: Yellow Cake CEO on market drivers - One2One Investor Forum proactiveinvestors.com/compa… #Uranium
1
253
🔔With #SPUT on the Spot #Uranium bid today holding $93.7 Million cash💰⚛️⛏️🛒😊 #Nuclear fuel brokers @UraniumMarkets report that sellers have raised their Asks to $77.00/lb for delivery to Cameco, Canada & Orano, France⬆️🇨🇦🇫🇷 and $77.25 to ConverDyn in the USA.⬆️🇺🇸🤠🐂🌊🏄

Russia's extension of counter-sanctions, banning enriched uranium exports to "unfriendly" nations like the US and EU until 2027, could tighten global supply (Russia holds ~44% of enrichment capacity). This may drive uranium spot prices up in the next 6 months, potentially to $90-100/lb from current ~$77, echoing 2024 jumps after similar restrictions. Alternatives from Canada/Australia could mitigate, but short-term volatility is expected.
$yca upward pressure building on U prices

342
Broken!💥🔨 #Uranium shortfall threatens #Nuclear #energy renaissance, industry warned⚠️⚛️⛏️🆘🚑 @WorldNuclear Fuel Report sees doubling of Uranium demand over next 15 years⚛️⏫as mined supply falls by 50%⛏️⤵️ leaving a 'significant gap' to be filled.↕️🤠🐂ft.com/content/0d6cb34e-4fda…


1
140


$yca
Van Eck increasing holdings to 7% and shorts starting to close.
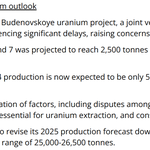
$kap and $ccj production downgrades.
londonstockexchange.com/news…
4
207
$ccj #uranium $yca $u.un
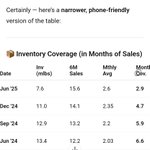
Let's not forget that as well as yesterday 2025 production downgrade that Cameco significantly had already rundown inventory by 3.4 mil lbs in H1 per their July update !
Time for utes to take action.

Inventory insights - quite the drawdown !
As of December 31, 2024, we held an inventory of 11.0 million pounds of U3O8 equivalent
After delivering 8.7 million pounds in the second quarter, our uranium inventory was 7.6 million pounds on June 30, 2025
4
535

More 2026/27 requests from Utes for > 40mlbs will likely spill over into spot carry trades taking the spot higher above long term pricing #uranium
