

Research and Policy Advisor @KansasCityFed doing macro and labor; Minnesota PhD; Views and tweets are my own. Retweets ≠ endorsement. https://teapawt.net/t.co/gHcXdyyG5O
Kansas City, MO
Joined April 2018
- Tweets733
- Following807
- Followers2K
- Likes1.7K
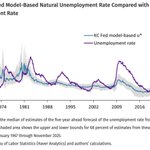


Keep up with the KC Fed Model-Based Natural Rate of Interest and Natural Unemployment Rate here!
kansascityfed.org/research/e…

The Federal Reserve has a dual mandate to ensure price stability and full employment. But how to tell if labor markets are at full employment and how to know what interest rate achieves the dual mandate? This requires estimating two time-varying objects: u* and r*.


Relatedly, the KC Fed Model-Based u* indicates that labor markets were slack for most of the 2010's even with inflation below 2% and policy rates near zero. Labor markets became balanced a few years before the pandemic, became tight in 2022, and are now roughly balanced again.

Did you read Nakamura, Riblier, and Steinsson's 2025 Jackson Hole paper "Beyond the Taylor Rule"? Check it out!
It inspired Johnson Oliyide and I to check how much post-pandemic monetary policy diverged from our own specification of the Taylor Rule
kansascityfed.org/research/c…

In a new Charting the Economy, we use our own monthly estimate of the natural rate to calculate the prescribed federal funds rate from a Taylor Rule that tracks r* while responding to inflation deviations from 2% and the unemployment gap.
Andy Glover retweeted

Looking forward to @SEDmeeting in Copenhagen from tomorrow!
Come and check out our session on Housing and Rental Markets on Saturday, with @andyecon and @_ChoongYang. I'll be presenting my recent paper on the "Home Purchase Channel of Expenditure".

Last weekend to submit for Midwest Macro here at the KC Fed! Lots of interesting papers already submitted, but we want MORE!
kansascityfed.org/events/202…
So happy to see this in print!

What happens if employers can't use pre-employment credit screening (PECS) in hiring? In a model with adverse selection in both credit and frictional labor markets, banning PECS lowers labor market efficiency but helps reduce poverty traps.
New paper from Corbae & @andyecon 👇

Come to KC in May for the Midwest Macroeconomic Meetings at the KC Fed!
kansascityfed.org/events/202…
Our Economic Bulletin (kansascityfed.org/research/e…) on how private-lending spreads have played a surprising role in dampening rate hikes was cited by @TheEconomist's recent discussion of what to expect during monetary easing!
economist.com/finance-and-ec…

Time for the KC Fed Jackson Hole Economic Symposium! Looking forward to interesting papers and discussions!

New KC Fed Economic Bulletin asks why higher interest rates haven't slowed the economy more. TLDR answer: private lending spreads usually increase significantly during monetary tightening cycles, but have been flat (or fallen) during this one.
kansascityfed.org/research/e…
We consider how risk-adjusted lending spreads (Gilchrist-Zakrajsek’s excess bond premium) and the effective stance of monetary policy respond to monetary policy shocks (Ala Bauer and Swanson).
Find that EBP usually rises more than 1-1 with shock, whereas stance rises less.