






And in response, Governor Abbott has endorsed, in name, Cipher Digital alongside Amazon as committed to compliance with his standards.
$CIFR is in position to win.


Cipher just posted this press release in support of Governor Abbott's recent actions regarding data centers in Texas.
Simply put, those that are comparing or thinking the situation in Texas is anything like what's going on in New York are grossly mistaken.
Texas is going through the process of separating the real from the fake. It's important that the MWs requested from the grid are going to productive stewards of the asset.
This benefits quality companies like $CIFR.

$OPEN just announced a raise. I love it.
“And waiting could make the shares we are buying back today more expensive, and homes we could be buying don’t get bought.”
Sounds to me like the next few quarters are shaping up to be fantastic.

Some news. Today, for the first time in Opendoor's history, we bought back our own stock.
Our share count is down 5%. We paid for this buyback with money borrowed at a 0% coupon and we still have hundreds of millions of dollars left to grow faster.
There are plenty of helpful details, along with a lot of legalese, in our press release and 8-K (linked below). But there are a few things I want to say directly and in plain English.
First, I *despise* dilution. On my first earnings call at Opendoor, I told you that if we issue a share, it has only one job: to make every other share worth more for our existing shareholders, not to extend runway for management. The flip side is just as simple: when our own stock is one of the best uses of capital, we should buy it back. Today, we did just that - by 5%.
Second, I run a publicly traded company. I don’t get to have feelings about the macro or the way Wall Street works. My job is to understand the rules of the game and use them to find an edge and build a better company.
One of those realities is that our stock price has lots of volatility.
People disagree - A LOT - about what Opendoor could be worth one day. Some think we're worth less. Some think we're worth dramatically more. I obviously have a view…
That disagreement isn’t just noise - it has economic value that Wall Street monetizes every single day.
Most companies would treat this as a headache, but we see it as an asset. If people are going to speculate about our future, I'd rather our shareholders get paid than anyone else. So instead of complaining about volatility, we used those dynamics to borrow $650M at a 0% coupon.
Then we turned around and used part of those proceeds to buy back our own stock. At today's prices, buying back our stock and call options was one of the best trades on the board. The rest stays on our balance sheet so we can buy more homes and grow faster.
As for dilution, we bought our stock where we thought it was cheap and pushed any future dilution far above today’s price. Not one net new Opendoor share will exist below $10.38. And if we buy back stock in the future, that floor goes higher.
But why raise now? Because the best time to raise capital is when you don’t need it. We’ve proven the business can reach ANI profitability, but profitability is just the starting point, not the finish line. And waiting could make the shares we are buying back today more expensive, and homes we could be buying don’t get bought. I’d rather move now.
Some people will call what we did today aggressive. They’re right. But being aggressive is how we fixed a company that spent years being careful. I’d make that trade again.
To our shareholders: You trusted us with your capital. Today, for the first time, Opendoor used its own capital to buy more of itself. The company is putting its money where its mouth is. Tomorrow, I will too.
After our lawyers allow, I’m personally buying $100K worth of shares. I'm all in, and I plan to keep buying.
Huge deal! Excellent video! $IREN is top notch!🔥🔥🔥
Delivery of horizon 2, 3, and 4 to follow and at faster speeds than Horizon 1.
2026-27 is looking fantastic for shareholders.
As I’ve said for months, $150 is doable by EOY.

Horizon 1: delivered.
IREN has delivered Horizon 1 to Microsoft and achieved NVIDIA Exemplar Cloud status on NVIDIA GB300 NVL72.
Read more: iren.gcs-web.com/static-file…
Yup! As expected! $IREN has delivered Horizon 1 to Microsoft.
Shoutout @FransBakker9812. He’s been on this.
Major derisking event, and major demonstration of operational expertise.
globenewswire.com/news-relea…

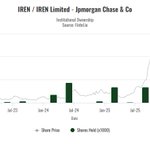
Major institutions continue to pile into $IREN. These are not names looking for a quick trade. This is sticky ownership here to stay.
Here's a quick summary of recent ownership changes:
Goldman Sachs: 33.64M (+504%)
Bank of America: 21.03M (+883%)
State Street: 6.39M (+144%)
Bank of Montreal: 2.14M (+108%)
BIT Capital: 7.03M (+44%)
JP Morgan: 2.7M (+46%)
Hardly any selling from the institutions either.

Ashlee is an OG of those that follow Rocket Lab.
He's 100% spot on with his analysis on GHOST. It's a far bigger deal than most even understand.
Bottom line: Rocket Lab continues to establish itself as a critical prime of the present and future.

You guys see what's going on, right?
For decades and decades, the US government has chased this idea of responsive space. Rockets that can go up on very short notice, ideally from lots of locations, and place satellites over areas of interest and importance.
It's been an incredibly hard thing to pull off. SpaceX started chasing this mission in a way but then moved away from the Falcon 1 and focused on Mars.
Rocket Lab has very much picked up the mantle.
It's putting pads in more and more places. It has two pads in spots rather handy for things happening in or near Taiwan.
This is stuff Lockheed and Boeing and others thought about but could not even begin to make happen.
Rocket Lab is basically becoming a space prime the likes of which we have never seen before.


Cipher has gotten so unbelievably cheap, it's ridiculous.
$CIFR already has already contracted ~$686M of NOI for 2027. This is contracted, co-location with funding already secured.
A 20x multiple, which Equinix and DLR command on similar projects, gets you to $13.7B EV.
We have not even mentioned the pipeline, which includes 477 of unsigned MWs set to energize in 2027, and not dependent on batch 0.
Let me put it simply:
You pay for the 700MW of already signed HPC, and for free you get a 5.3GW pipeline, possible BTM expansion, possible cloud optionality, and the talent of the team.
I bought more shares today.

Michael Burry is in the business of staying relevant to sell as many substacks as possible.
A fine business model which likely is printing great money for him.
But that is not where I would go for investing insight.
Good print for $NBIS.
Being short compute here is absurd.
As expected the $NBIS print came in extremely strong.
Bottom line: Demand for AI compute has gone asymmetric.
The question is to what rate supply can catch up. I see no reason to believe the gap between supply and demand wont continue to grow.
Those that have the supply win.
Great write-up from Jim covering $CRWV earnings.
Let me simplify the top-down view when comparing $IREN and $CRWV. (These are my own views, not necessarily Jim's).
$IREN will make more money per MW in the coming months/years than CoreWeave. Operationally, CoreWeave is at the top of the market in software orchestration, but the economics do not pan out. I would not go bearish on $CRWV here, I think they, of all neoclouds, will benefit drastically from new funding pools organized by Nvidia. Their biggest problem is simply their cost of capital is far too high. However, as this market evolves, the advantage of superior orchestration will diminish in comparison to vertical integration.
Then again, Mirantis begins to close the orchestration gap with CoreWeave. Their margin becomes $IREN opportunity.
Regardless, here's the bottom line. The future is large scale AI factories. The future demands massive quantities of electrons. The bottleneck lies there for the foreseeable future. And, sovereign control of the stack will demand a premium. Sovereign control requires vertical integration, which $IREN specializes in.

$CRWV: Q2 Earnings
Revenue: 2.6B or 10.4B ARR
EOY 2026 ARR Target: 18B-19B
Backlog: 104.2B at end of Q2 (129.2B Aug 11)
Adjusted EBITDA Margin: 59%
Operating Margin: 5%
Adjusted Net Loss: -22%
Full AI Platform
Contrary to misinformation on X, Coreweave serves Managed Inference, Development Tools, Orchestration and Observability and are a full AI Platform.
EBITDA Margins
Their EBITDA margins with software come out to 59%. $IREN's H1-4 EBITDA margins are 85% but after depreciating DC build cost for an apple-to-apple's comparison, $IREN's H1-4 EBITDA margin minus DC depreciation come out to 55%.
$IREN is able to keep up on EBITDA margins without software because IREN is vertically integrated on the power and datacenter front. Coreweave's software make up for it's colocation costs to achieve 59% EBITDA margins. For comparison $NBIS has ~40% EBITDA margins. Once $IREN integrates Mirantis and DSX OS, it has a great chance of leading on EBITDA margins among the 3 Neoclouds.
Backlog
Coreweave hit a 129.2B backlog on earnings day Aug 11 which is a huge 25B increase from 104.2B at end of Q2. This is great news for $CRWV, $NBIS, $IREN as it shows the unprecedented demand in this sector.
Financing
Coreweave will likely benefit from Nvidia's 500B financing pool along with $NBIS and $IREN. However, it's high interest cost make it's Net Loss Margin -22% on what otherwise is a great inflection point of 5% operating income.
In other words, Coreweave is a profitable business operations wise besides its high interest payments. This bodes well for Neocloud sector profitability as a whole.
Enterprise Customers
Coreweave has the widest diversification of customers among Neoclouds with:
Primary Cloud: Bentley, Caterpillar, Grammarly, Isomorphic Labs, Sunday Robotics.
Expanded Partnership with: Cognition, Databricks, HRT, Periodic Labs, Rescale, Runway ML.
Primary cloud is important because although Coreweave and NBIS both serve Cloudflare, they are not the primary cloud for cloudflare. Likewise Shopfiy's primary cloud is GCP not NBIS. Being a primary cloud for a customer is more indicative of usage beyond of orchestrated GPUs or bare metal+k8s.
Contracted Power
3.7GW by end of Q2 and 4.2GW by Aug 11. This is a majority colocation however, colocation is working for Coreweave as they still achieve 59% EBITDA margin. This sometimes results in delay but their main problem is interest expense, not colocation.
$CRWV is a 55B company with 35B debt for a total of 90B EV. If $IREN can buildout 5GW and integrate in Mirantis to catch Coreweave, it has large upside as $CRWV itself still has significant upside from it's 90B EV.


Nearly 24 hours after Rocket Lab has reported Q2 earnings. I just finished my readthrough on the 10-Q, and had Claude back me up.
Here's some nuggets pulled from the 10-Q you may have missed.
Thread below.

5. ~$1.9B of the May ATM remain, likely funding needed for Iridium.
Regarding the funding of the Iridium purchase, simple framework to think through:
Minimum $3B needed for acquisition. Possible additional $1.8B depending existing Iridium loan terms.
Worth keeping an eye on.

Final read:
This is an extremely quality quarter for Rocket Lab. Headlines will read about Neutron, but under the hood, this company is executing at a high level.
Rocket Lab is making M&A moves at its present valuation that it never before could, all while the underlying business flourishes.
I remain a confident shareholder and look forward to the coming quarters of execution.
Best,
Beav