

Former Fixed Income Trader & PM. Tracking the market’s rhythm with patience and a steady hand.
Joined June 2016
- Tweets1.9K
- Following925
- Followers339
- Likes3.1K


Metronome Capital retweeted
I believe the @nvidia board is not acting in the best interest of shareholders nor in a manner consistent with their fiduciary duties.
What we know is that the board fired Jensen or forced his resignation for violating company policy and/or in response to the accusation of an affair with a spy.
They did so without careful consideration of the impact on the company, its customers, its shareholders or other stakeholders.
They rushed to judgment without the benefit of careful due diligence or even with a basic understanding of the facts.
How do we know this?
We know this by how quickly Jensen was fired and how little was known at the time of his firing.
It takes time to convene a board meeting. There was time, maybe, for one Zoom.
And this is a decision that should have been made by a board sitting in person and carefully deliberating the facts once they are known.
And they should have slept on the decision and met again the day after to discuss the facts, the risks and the other implications of their decision.
The timing and lack of information did not allow for careful board deliberation.
While boards can fire a CEO for an inappropriate relationship with a subordinate, it should not be an automatic decision. That is why we have boards comprised of humans and not agents.
A board should consider whether or not such a relationship was consensual or whether it was an abuse of power dynamics. And a board has to consider what the impact of the firing is on all stakeholders.
If I were in this board, I would not have rushed to judgment based on articles in the media. I would have made sure the board had all of the facts so it could make a careful and informed decision.
Boards of Delaware companies have a duty of care which means they must make informed, prudent and good faith decisions. This clearly did not happen here.
What law firm is advising this board?
Or is the board even taken good legal advice?
It doesn’t look like it.
And now the board is compounding its failures by insisting that there is no possibility for Jensen’s return as CEO.
Why is it in the best interest of the company to foreclose the possibility of Jensen’s return and to do so before all of the facts are known? This is yet another breach of their duty of care.
Furthermore, the board has launched an investigation whose scope is unknown. Investigations can be extremely damaging to a company and should be carefully targeted to address whatever facts need to be known rather than be overly broad in scope.
In short, this looks like a series of major governance failures by directors that panicked due to headlines in the media. They likely felt compelled to do something because they were afraid of looking bad in the media, not because it was the right thing for them company.
They couldn’t stand the heat.
The board’s conduct here is shocking for a company of this scale and importance to our country and the world at large, particularly at this moment in history.

Metronome Capital retweeted

TeraWulf CFO: There are infrastructure funds that are chomping at the bit to buy equity in stabilized assets at the project level at significantly higher multiples than where any of us trade today. $WULF

Jensen Huang, a brilliant entrepreneur, visionary, businessman, leader, the Godfather of AI, proves we’re all human and fallible and probably deserve to be replaced by robots.
1
126
$WULF is doing something its peers aren’t, providing guidance on easy to model annual growth targets.
On this morning’s Q3 call, Wulf reaffirmed its target of contracting 250–500 MW of new critical IT capacity every year. Management also said it can hit that target with the sites it already controls.
When you build that guidance into a cash flow model, the upside is substantial. My 10-year DCF uses a conservative 9% discount rate and a 6.5% terminal cap rate, and assume new MW additions start in 2029:
Here's the model. Pull it apart, flex the inputs, and tell me what you’d change.
docs.google.com/spreadsheets…


Every current and potential $WULF shareholder needs to know this:
Management’s message from today's conf. call was that they won’t issue equity at today’s share price to fund growth. They named several alternatives but put no sizes, terms or timing on any of them.
Paul Prager, CEO (prepared remarks)
TeraWulf won’t sign a lease that forces it to issue equity at a valuation management thinks undervalues the company.
For Muskie specifically, the goal is a financing plan that reflects the value created at the site, preserves returns and minimizes dilution. Development would be phased, with capital raised alongside contracted demand.
Justified is already funded on the equity side. The remainder will come from project-level debt backed by Google’s credit support.
Rising financing costs are priced into new contracts, and TeraWulf won’t absorb financing risk that belongs elsewhere in the structure.
Patrick Fleury, CFO (prepared remarks)
Existing liquidity plus the remaining $280M of Abernathy proceeds covers three things without tapping equity markets:the rest of the Lake Mariner build
the remaining Justified equity
interim letters of credit at Muskie
The revolver was upsized to $400M with a $150M accordion, and the limit on how much of it could back letters of credit was removed. In December, the roughly $300M of cash now posted as Muskie letter-of-credit collateral is expected to be replaced by letters of credit drawn on the revolver, which frees that cash.
Once all the Lake Mariner leases commence, that project should generate significant cash and pay down debt quickly. Pulling equity out of stabilized assets and sending it back to the parent is a 2027 priority.
Q&A: Stephen Byrd (Morgan Stanley) on the equity overhang
Fleury listed the options:customer prepayments
customers buying TeraWulf equity at higher prices
more leverage, since the Lake Mariner project will be under-levered once it’s online
infrastructure funds buying project-level equity in stabilized assets at multiples well above where the public stocks trade
He said they would not sign one of the company’s biggest leases and then be forced to dilute shareholders “at these levels.”
Prager added that customers work with them to protect the spread. Fleury described open-book talks with tenants on cost of capital, aimed at keeping the lease yield on cost above TeraWulf’s cost of capital, backed by protections in the lease.
Q&A: Michael Funk (BofA) on selling stabilized assets
Fleury said the plan is to build and own long-term, but selling a minority stake to an infrastructure fund is possible. His example was Blackstone buying into FirstEnergy’s transmission business. He tied this to public markets continuing to undervalue data center developers, and said execution comes first.
Related points
The Google backstop at Justified requires no new equity or warrants for Google, unlike the Lake Mariner deal, and its cost is recoverable from Anthropic.
In response to a question about a competitor’s capital-light deal, management said it isn’t their primary focus. Their view is that full turnkey colocation creates more equity value per MW.
Metronome Capital retweeted

⚠️ $CIFR Q3 SCORECARD: The "EPS beat" was Google's warrant. Rent came in 65% light. No new lease.
Two days ago I posted the 3 numbers that mattered for this print (quoted below). Cipher reported before the open. Here's how each one scored, plus what changed in the filings.
The short version:
• The GAAP headline was a non-cash warrant gain, exactly as flagged.
• First rent arrived, but far below what the street expected.
• No new lease, and the 2027 power bucket got smaller.
• Barber Lake rent is still "Q4". Google's top-up is still pending, on slightly different terms.
Stock reaction so far (11:26 ET): opened $7.36, sank to a new low of $6.66 (−8.6%), now $7.05 (−3.3%) on ~23M shares.
A muted move for a stock that swung −16%, +24% and +13% on its last three prints. The market had already priced a lot of this.
━━━━━━━━━━━━━━━
THE NUMBERS vs CONSENSUS
• Total revenue: $26.7M vs $38.7M expected (−31%)
• HPC lease revenue: $5.9M vs $16.6M expected (−65%)
• Bitcoin revenue: $20.8M vs $24.0M expected (~296 BTC mined, down from ~346 in Q2)
• GAAP EPS: +$0.08 basic vs −$0.25 expected. Diluted: −$0.22
• Net income: +$31.6M, including a $127.2M non-cash gain on the Google warrant
• Adjusted EBITDA: −$10.0M (Q2: −$30.0M)
• Unrestricted cash: $656M at 30 Sep (Q2: $832M). $724M pro forma for October's convert
• Total debt: $6.70B pro forma, matching our pre-print count
━━━━━━━━━━━━━━━
SCORING THE PRE-PRINT CHECKLIST
1️⃣ Data-centre rent vs $16.6M → ❌ MISSED
HPC revenue was $5.9M. Black Pearl had only 18 MW of critical IT capacity delivered to Amazon so far, out of a 300 MW gross campus. Rent began in August, so this is about 1.5 months of a small first phase.
Read: the lease is real, but the ramp is slower than the street modelled. Q4 consensus for HPC revenue was $77M. That now looks like a stretch.
2️⃣ Barber Lake rent date + Google top-up → ⏳ STILL PENDING
Barber Lake's lease hadn't started at 30 Sep, so Google's warrant clock hasn't started either. The new deck gives the schedule:
• Data halls 1 & 2: rent in Q4 2026
• Halls 3 & 4: Q4 2026 to Q1 2027
• Hall 5: Q1 2027
The company says construction is on track for the amended milestones.
Correction to my original post, from the new 10-Q:
• The make-whole floor is $435M, not $430M.
• The warrant covers ~26.2M shares, not 24.18M. About 2.0M were added on 16 Oct when the 2030 notes were settled in stock.
• At $7.29, that's ~$191M of value against the $435M floor: a ~$244M gap, or roughly 33-34M extra shares (or cash).
Same mechanism, slightly different numbers. It triggers when Barber Lake's first rent starts.
3️⃣ New lease on 2027 power → ❌ NONE
No new lease. And the 2027 bucket shrank. Before the print I counted 477 MW available in 2027 (Odessa 207 + Reveille 70 + Ulysses 200). The new deck shows 270 MW for 2027: just Reveille and Ulysses.
Odessa now sits under "active discussions on HPC monetization", with its cheap power contract still ending in July 2027.
The CEO's line: Cipher is "advancing design work before committing to new leases." That reads like no deal is imminent.
━━━━━━━━━━━━━━━
THE CALLS THAT LANDED
✅ "Watch the GAAP headline"
I wrote that a falling share price would shrink the Google warrant liability and could produce a fake "beat". It did: +$127.2M warrant gain turned a loss into +$31.6M net income.
Strip it out and the quarter lost ~$96M, about −$0.23 a share. That's in line with the −$0.25 consensus, not a beat.
✅ "The 30 Sep balance sheet won't include October's convert"
It's in subsequent events. The $850M convertible and the 40.7M-share exchange both closed on 16 Oct.
✅ Convert upsize
The $150M option expired unexercised. So October's raise stayed at $850M. That's a small positive.
━━━━━━━━━━━━━━━
WHAT'S NEW IN THE FILINGS
🟢 Barber Lake costs, with numbers this time
The deck shows Barber Lake's cost per IT MW at $10.4M originally, $12.3M without the lease extension, and $13.0M with it (+25% vs the original budget).
The company says yield on cost holds at ~15.2% because the AI lab's extension adds rent, versus 12.9% without it. Cipher chose to invest more capital in exchange for 10 more lease years instead of taking change-order reimbursement.
That's the company's framing. It still means more Cipher money in the ground before the extra rent arrives in years 11-20.
🟢 ERCOT
Colchis (1 GW) got a conditional base-load classification. Another 1.6 GW got conditional studied-load classifications. Final classifications are expected in December, after the Texas data-centre audit.
🟢 Pipeline headline grew: 5.9 GW
But read the footnote: that's ~3.4 GW of grid capacity subject to ERCOT's batch process, plus up to 2.5 GW of potential on-site gas generation. The gas part is a development plan, not energised or contracted power.
New site: Horizon, 70 MW in Texas, energisation expected 2029.
🟡 A new NOI number, not like-for-like
In August the company said ~$793M of average annual NOI (Oct 2026 to Sep 2036). The new deck says ~$864M, measured over a longer window (Aug 2026 to Jul 2041) and including projected extra rent from Barber Lake's cost-sharing. Don't read the move from $793M to $864M as growth.
🟡 Contracts
Contracted revenue is $16.6B, as expected. Including tenant extension options it's $28.4B, but those options are the tenants' choice.
🟡 A name in the deck
The deck mentions a $10M water-infrastructure commitment at Colorado City, funded jointly with Fluidstack and Anthropic. The filings still don't name the AI lab behind Barber Lake's second 10-year term. Don't assume.
🔴 Cash and the equity question
Unrestricted cash fell $176M in the quarter to $656M. Construction commitments are still ~$1.6B. An at-the-market share programme of up to $725.7M is in place.
The press release and deck don't repeat August's "we do not expect to require additional equity". I'd treat that silence as information.
🔴 Bitcoin is shrinking faster
~296 BTC at Odessa vs ~346 in Q2, on the same 207 MW and ~11.6 EH/s. Network difficulty is doing the work. Bitcoin revenue still pays most of the bills until rent ramps.
━━━━━━━━━━━━━━━
WHAT IT MEANS
The pre-print setup was: the leases are real, the equity is a thin slice behind ~$6.7B of debt, and Monday was the first check on whether contracts turn into cash on time.
Answer: they're turning into cash, but slowly. 18 MW of 700 MW is paying. Barber Lake rent is still a Q4 promise. And there's no new lease to change the funding story.
What hasn't changed: the debt is fixed-rate and mostly project-level, the tenants are investment-grade, and the contracted backlog didn't shrink.
What to watch next:
1. Barber Lake's actual first-rent date, and how Google's ~$244M top-up is settled (shares or cash).
2. Q4 HPC revenue against $77M consensus. I expect estimates to come down.
3. ERCOT's final Batch Zero classifications in December.
4. Any lease on Reveille or Ulysses before 2027
energisation, and what happens to Odessa before its power contract ends in July 2027.
5. Unrestricted cash next quarter, and whether the ATM gets used.
Not investment advice. No price target. Do your own research.
━━━━━━━━━━━━━━━
SOURCES
• Cipher Digital Q3 2026 press release and business update deck (8-K, 2 Nov 2026)
• Cipher Digital Q3 2026 10-Q: Notes 12 (leases), 16 (Google warrants), 21 (subsequent events), MD&A liquidity
• Pre-print consensus: FactSet (30 Oct 2026)
• Original case study and pre-print post (quoted)
Repost if this was useful.


$CIFR: everyone’s counting the $16.6B of contracts. Nobody’s counting what’s left for shareholders.
Read this before Monday.
Cipher Digital reports Q3 2026 before the US open on Monday 2 Nov (call 8:00 ET). I went through the 10-Ks, 10-Qs, proxy, decks, four call transcripts and the October 8-Ks.
TLDR:
• Down 75% from the $29.18 close on 18 Jun. Down 54% in October alone.
• ~$16.6B of contracted lease revenue (Amazon, Fluidstack with a Google backstop, a third hyperscaler, plus an AI lab for Barber Lake years 11-20).
• ~$3.3B market cap. ~$6.7B of debt. Q3 is the first quarter with any lease rent.
The short version: the leases are real. The equity is a thin, leveraged slice on top of them. Monday is about three things, and EPS isn't one of them.
Here's the full breakdown.
━━━━━━━━━━━━━━━
1/ WHAT CIPHER IS NOW
Cipher Mining renamed itself Cipher Digital in Feb 2026. It's turning from a bitcoin miner into a data-centre landlord: it finds sites with grid power, builds the shell and power systems, and leases them for 10-20 years. Tenants bring their own computers.
Through June, 100% of revenue was still bitcoin ($24.8M in Q2).
The signed portfolio:
• Black Pearl (Wink, TX): 300 MW, Amazon, 15 years, ~$5.5B. First capacity delivered Aug 2026.
• Barber Lake (Colorado City, TX): 300 MW, Fluidstack, Google backstops up to $1.4B of Fluidstack's obligations. Extended to 20 years on 25 Sep (+~$5.2B from an unnamed AI lab for years 11-20). Halls now arrive in phases, Q4 2026 to Q1 2027.
• Stingray (West TX): 100 MW, investment-grade hyperscaler, 15 years, delivery 1H 2027.
Company guide: ~$793M of average yearly net operating income (NOI) from Oct 2026 to Sep 2036 across the three leases.
Behind that: Odessa (207 MW, bitcoin, cheap power contract ends Jul 2027), Reveille (70 MW) and Ulysses (200 MW) with interconnection approved, then ~2 GW in Texas waiting on ERCOT's Batch Zero process.
━━━━━━━━━━━━━━━
2/ HOW THE MONEY FLOWS
Each campus has its own bond: $1.73B at 7.125% (Barber Lake), $2.0B at 6.125% (Black Pearl), $810M at 6.0% (Stingray). The Stingray bond covered ~98% of project cost.
Bond cash sits in restricted accounts ($3.7B at 30 Jun) and pays for construction. Rent then pays interest and amortisation.
The parent pays for everything else: overhead, cost overruns, equity for new sites, and the Google make-whole (section 3). That's where new shares come from.
History: free cash flow has never been positive. 2021-2025 cumulative FCF was about -$1.68B, funded by ~$0.93B of equity and ~$3.15B of notes. Diluted shares went from ~219M (2021) to ~382M (2025). ~455M are outstanding after October.
━━━━━━━━━━━━━━━
3/ THE FORENSIC FLAGS
The books are clean: unqualified audit and controls opinion, last year's IT-controls weakness fixed. The risk is in the capital structure.
🔴 The Google make-whole
Google got 24.18M warrants at $0.01 for backstopping Fluidstack's rent. If those shares are worth less than $430M the day before Barber Lake's lease starts, Cipher tops up the difference in shares or cash.
At $7.29 the gap is ~$254M, roughly 35M extra shares. Barber Lake's first rent is expected in Q4 2026.
🔴 "No equity needed" didn't last
4 Aug call: "we do not expect to require additional equity."
13-14 Oct: $850M 0% convertible due 2032 (conversion price $15.31) plus 40.7M new shares to retire $165.9M of 2030 notes. Proceeds fund extra equity in Barber Lake.
🟠 Barber Lake overruns
Cipher bears the first $359.3M above budget. Beyond that the tenant pays 50%, recovered as extra rent over 20 years. The CEO said in August current builds are "running at the contingency level" given inflation.
🟠 Guarantees start only when rent starts
New in the FY2025 10-K: tenant guarantees (Google's included) apply only after rent commencement, and tenants can terminate on significant construction delay.
🟠 Stock comp
$52.8M in FY2025 (24% of revenue). $57.6M in H1 2026 (96% of revenue).
🟠 Non-GAAP switch
From Q1 2026 the headline metric moved from Adjusted Earnings to Adjusted EBITDA, which also strips out interest ($66.7M in Q2).
🟠 Incentives reward volume
Bonus KPIs are MW energised, MW of power portfolio and MW under LOI or lease, not per-share returns. 2025 bonuses paid at 200% of target. 2025 PSUs certified at the 225% max.
🟠 Insiders sold the top
CEO Tyler Page sold ~$20.4M at $28.14 (22 Jun) and ~$5.9M at $24.50 (30 Jun), per Form 4 summaries. Holder V3 Holding sold ~$78.5M.
🟢 What's fine
Fixed-rate project debt (6.0-7.125%) that amortises with rent. The 2030 convertible is almost fully retired ($6.6M left).
━━━━━━━━━━━━━━━
4/ GUIDANCE vs WHAT HAPPENED
• Black Pearl rent: Nov 2025 deck said Aug 2026. The 10-K moved it to Q4 2026. First capacity came in Aug 2026, called "2 months early". Early vs the revised date; on time vs the original.
• Barber Lake: "complete Sep 2026, rent Oct 2026", repeated on 4 Aug. On 25 Sep, halls were phased to Q4 2026-Q1 2027 (company cites changing tenant requirements). Slipped.
• Reveille: Q2 2027 in Nov 2025, Q3 2027 in Aug 2026. Slipped a quarter.
• No new equity for contracted builds: said Feb and Aug 2026. Missed in October.
• Average contracted NOI: $669M → $787M → $793M as Stingray was added. Delivered.
• ERCOT: Texas paused Batch Zero on 3 Aug (Governor's audit). On 15 Sep Cipher got 3.2 GW of conditional classifications. ERCOT's verification report is due 10 Dec. On track, not final.
━━━━━━━━━━━━━━━
5/ WHAT THE STREET EXPECTS
FactSet consensus (30 Oct, 25 analysts, average rating Buy, average target $28.33, which predates most of the fall):
• Q3 revenue: $38.7M (HPC leasing $16.6M, bitcoin $24.0M)
• Q4 revenue: $114.2M (HPC $77.0M)
• FY2027 revenue: $809.9M; EBITDA $533.1M
• Q3 GAAP EPS: -$0.25
Note the Q4 HPC number. The company's NOI schedule has $97M for Oct-Dec 2026, but that predates the Barber Lake phasing.
Positioning:
• Short interest 91.6M shares, 26.4% of float, 2.3 days to cover (mid-Oct settlement). Part of that is likely convertible-arbitrage hedging against ~$2.15B of converts.
• Daily RSI ~25. Realised volatility ~96-99%.
• Last three prints (same-day close): +12.5% (24 Feb), +23.5% (5 May), -15.6% (4 Aug).
━━━━━━━━━━━━━━━
6/ WHAT THE PRICE IMPLIES (reverse DCF)
I valued only the three signed leases on the company's own NOI schedule, minus overhead, debt and the Google make-whole. Whatever the market pays above that is the price of everything else: Odessa, Reveille, Ulysses, Batch Zero, Apollo.
• The signed leases alone justify $7.29 only at a ~6.9% discount rate (no growth) or ~8.3% (2% growth).
• At a more typical 9-10% for a leveraged developer, the market is paying $1-3B for the pipeline.
• Each point of discount rate moves the leases' equity value by about $1B, or ~$2 a share.
That's the key insight: the equity is a thin slice on top of $6.7B of debt. Small changes in rent timing or cost of capital move the share value a lot, in both directions.
Fully built enterprise value is ~$9.6B, about 14x contracted 2027 NOI. At the June peak it was ~25x.
All assumptions are mine and illustrative. Not a target.
━━━━━━━━━━━━━━━
7/ MONDAY: THE 3 NUMBERS THAT MATTER
1. Data-centre rent vs $16.6M. How many Black Pearl MW were paying by 30 Sep?
2. Barber Lake's rent start date, which triggers Google's warrant. Shares or cash for the top-up, and how much?
3. A new lease on 2027 power: Odessa, Reveille or Ulysses (477 MW outside ERCOT's batch). Tenant, term, rent per MW.
Also check:
• Unrestricted cash at 30 Sep and the updated funding plan. Was the $150M convertible upsize used?
• The 30 Sep balance sheet won't include October's convert (settled 16 Oct). Look for it in subsequent events.
• Strip out the warrant mark before calling an EPS beat (see below).
━━━━━━━━━━━━━━━
MYTH-BUSTING
❌ "$16B of contracts, so it's 5x undervalued"
That's gross rent over up to 20 years. Yearly NOI is ~$793M, and $6.7B of debt gets paid first. On market cap plus debt it's ~1.7x, not 5x.
❌ "Google is backing Cipher"
Google backstops up to $1.4B of Fluidstack's rent at one site. It also holds warrants with a $430M floor that Cipher must top up.
❌ "It has $4.5B of cash"
$3.7B of the 30 Jun total was restricted to construction and reserves. Unrestricted cash was $832M.
❌ "Barber Lake started paying in October"
Not confirmed. The 25 Sep release says first rent is expected in Q4, with halls phased to Q1 2027.
❌ "The fundamentals haven't changed"
Since August: Barber Lake phased later, a $359.3M first-loss on overruns, and an equity raise.
❌ "26% short, squeeze coming"
Possible, but part of it is hedging against ~$2.15B of convertibles. Days to cover is only 2.3.
❌ "Q3 EPS beat = the business is working"
The share price fell from $24.50 (30 Jun) to $15.83 (30 Sep). That shrinks the Google warrant liability, booked as a non-cash gain. A GAAP "beat" could be mostly that.
❌ "Insiders are loading up"
The CEO sold ~$26M in late June. V3 Holding sold ~$78.5M.
❌ "It's still just a bitcoin miner"
Revenue was 100% bitcoin through June, but 700 MW is leased to three big tenants. Q3 is the first rent quarter.
━━━━━━━━━━━━━━━
THE BOTTOM LINE
Cipher has done the hard part: signed long leases with some of the biggest tech companies in the world, and financed the builds with fixed-rate project debt.
But the equity sits behind ~$6.7B of debt, a $430M Google make-whole, cost overruns and a pipeline that needs more money. The price no longer pays for the 4.4 GW pipeline at full value. It does assume the signed leases start paying on time and that funding doesn't dilute further.
Monday tells us how much rent has started, when Barber Lake begins, and what the Google top-up costs. Watch those. Ignore the GAAP headline.
Not investment advice. I don't hold a price target. Do your own research.
━━━━━━━━━━━━━━━
SOURCES
• Cipher FY2025 and FY2024 10-K, 10-Qs Q1 2025-Q2 2026, 2026 proxy (DEF 14A)
• Cipher business update decks (Nov 2025, Feb, May, Aug 2026) and call transcripts (Q3 2025-Q2 2026)
• Q3 call date: globenewswire.com/news-relea…
• Barber Lake extension (25 Sep 2026): investors.cipherdigital.com
• Convertible pricing 8-K (14 Oct 2026): sec.gov
• ERCOT Batch Zero notice (3 Aug 2026): ercot.com
• FactSet financials, estimates and prices (30 Oct 2026)
• Short interest: Fintel
If this was useful, repost so more people read the filings before Monday.


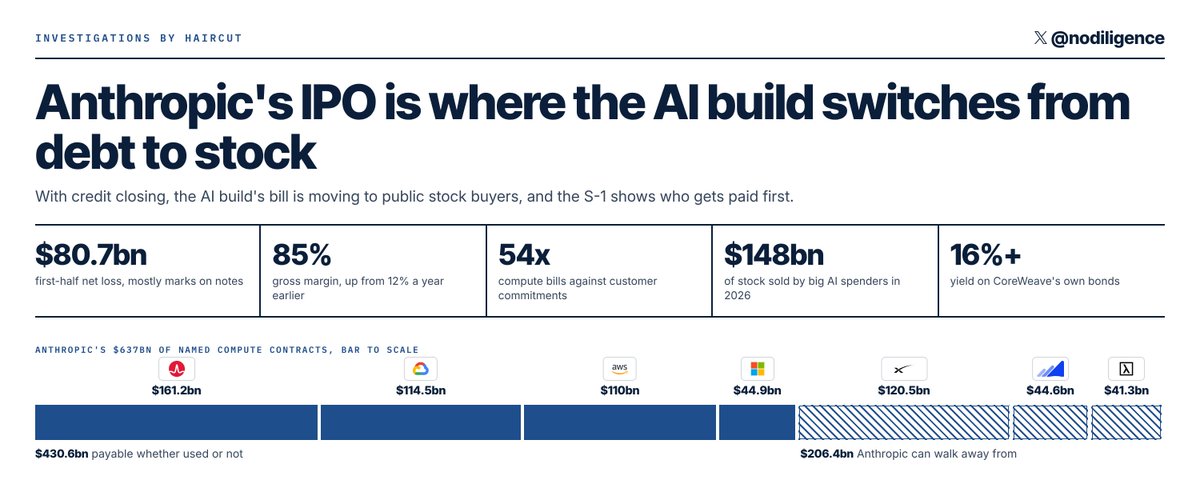
S the article below describes, in the AI buildout risk flows down the chain: hyperscalers push it to the labs, the labs push it to neoclouds on short contracts, and lenders and new equity buyers hold what's left. The landlord with a 20-year lease and an investment-grade backstop sits outside that flow. That's why I like $WULF @TeraWulfInc @PaulBPrager

anthropic is probably the best business in AI right now and i still wouldn’t touch it on day one. the whole thing is set up for suppliers and insiders to sell into the index buying.
2
304
Cheat sheet based on Sridhar Ramaswamy’s excellent analysis. Full original post below


1/16 the ai industry is making an unusual bet: buy compute for years, sell intelligence by the token. banks, commodity merchants, airlines, utilities and cloud providers each explain a different part of the risk.
1
169
Serenity now, Serenity now!
@aleabitoreddit


The S&P 500 returns Nov -> Jun following midterm elections apparently:
- 21/21 times were positive
- Avg. index gain was 16.6%.
High-beta stocks historically outperformed even more…
Very interesting, with Nov 3rd coming up, do you think 2026 will be an anomaly?

135

This is why you invest in good Management when making long term investments. They got your back @TeraWulfInc @PaulBPrager 👇

we have projected $10-12 million per MW. We will be there. We signed phenomenal FLUOR as EPC with a GMP structure so not worried about our ability to execute on price and schedule. Kentucky particularly great place to build as sensible permitting, availability of skilled labor, clear regulatory framework. We have the commitment for an investment-grade credit backstop so debt will be competitively priced.
2
198
I've been wondering why the market seems to be more removed from fundamentals than it did in the past? I have two thoughts:
1. Dodd-Frank and post-2008 capital rules sharply constrained primary dealers' ability to warehouse inventory on bank balance sheets. In response, non-bank market participants and leveraged quantitative hedge funds stepped in to provide critical market liquidity and relative-value risk absorption.
While this structure can improve day-to-day execution efficiency, it shifts systemic risk warehousing to entities funded primarily through short-term repo leverage and prime brokerage capacity. Because non-bank providers face no formal duty to make markets, periods of elevated volatility can trigger margin calls and forced de-leveraging—temporarily reducing market depth when liquidity is needed most and therefore, exacerbating moves.
2. The rise of quantitative trading strategies and systematic multi-manager pods has fundamentally altered short-term price formation in financial markets.
Rather than pricing assets on long-term cash flows or fundamental valuation models, quantitative models focus heavily on cross-asset statistical arbitrage, order flow toxicity, factor risk-premia, and short-term momentum signals. As a result, when large systematic portfolios rebalance or execute risk-limit unwinds, institutional capital flows can drive significant short-term price action completely independent of underlying corporate or economic fundamentals.
While market prices ultimately converge toward fundamental reality over longer horizons, the growing dominance of algorithmic execution means that short-term asset prices are increasingly dictated by quantitative market mechanics, liquidity constraints, and factor positioning.


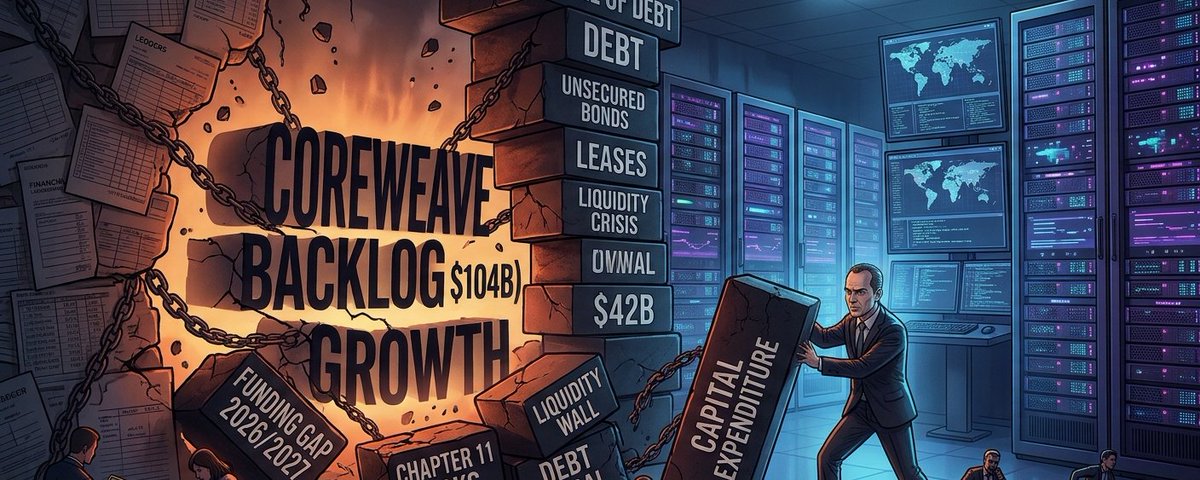
Now don't get me wrong, although I'm very confident, Like Bernstein, that $GLXY would continue collecting rent if $CRWV were to ever enter CH11, I do think the probability that could happen is ver high. Here's an article I wrote explaining why 👇👇
teapawt.net/brad_D6/status/2113626…

364