

Ph.D. Economist, 24 years writing about PBMs, currently writing about the shift toward Rx management at the EHR PoC led by Epic Systems.
North Monterey Co. CA. USA
Joined November 2010
- Tweets6.8K
- Following581
- Followers1.1K
- Likes3.7K





Pinned Tweet
@baseten deep-stack LLM router / harness/ post-train bespoke customer owned open weight models / multi cloud deployment with current AAR reportedly $600 M but mostly from first stack LLM router with little to even negative margins ( justified as CAC). Still worth $30 B valuation due to future margins down stack. These full stack companies need a new name for what they do. My suggestion “MCMaaS” - Bespoke Model Creator and Manager as a Service. @FireworksAI_HQ @Modal @MenloVentures #Ai

Likely negative margins — marketing costs - to get scale and show accelerating ARR to get more funding. A flywheel effect with no value creation :(

$PLTR faces big headwinds in form of substitution of capital for labor: company owned capital via @baseten @modal @FireworksAI_HQ post-trained open weight LLM substituted for 10x more expensive $PLTR forward deployed engineers

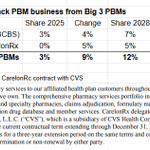
My napkin math: (1) $CVS #PBMs Caremark loses BCBSs business so RemainCo 2028 EPS is $6.00 not your $6.70 (2) valuation multiple is Cigna 9.1 not blended with Elevance to get 11.5 (3) Continued headwinds for drugstore traffic due to 1 day $amzn deliver and AI driven patient Rx choice like @HeyEpic Prescription Marketplace at PoC. So RemainCo = $6.00*9.1 = $54.6B + Retail about $10B not your $15B Total $CVS value 2028 will be $64.6B -- 20% from today.


Some napkin math on $CVS with the stock now at ~$80.
RemainCo is Aetna plus Caremark and the PBM comprises about half of earnings. The PBM comp is Cigna at ~9.1x 2027 earnings. The diversified insurer comp is Elevance at ~14.3x. Blend them by earnings weight and you get ~11.5x and on RemainCo’s ~$6.70 of 2028 EPS it's worth ~$77 a share.
The stores are a retailer and will trade like one. Sycamore paid ~6.5x trailing EBITDA for a much weaker Walgreens, Kroger’s at ~6.8x, Albertsons ~4.5x. I use 6x on ~$6.2B of 2028 EBITDA and hand them 2x of debt (TBD on debt split) and get ~$19 a share. Take off ~$4 for separation costs and the opioid tail and you’re at $92 - 15% upside to today so not very interesting yet - call me at $65-70.
The whole bull thesis will be oriented towards the MA book inside of Aetna. Aetna is ~40% Medicare Advantage by revenue and that book made almost nothing in 2024-25 and only turns profitable this year - so a credible path to 3-4% margins is ~$2B of pretax earnings that isn’t in the run-rate yet. The market pays for that when it believes it - Humana is at ~24x trough 2027 EPS because the Street has underwritten its 2028 margin bridge which works out to ~15-16x normalized. Aetna’s problem is that Humana’s stars are going up into 2028 and Aetna’s just went down, from 81% to 69% of members in 4-star-plus plans, with ~$2B of bonus revenue at stake and management promising the high end of its growth plan anyway. I take half the hit and get Aetna to $7.2B in 2028. If they actually bridge it, RemainCo is ~8.4x at $80 and the stock is flat-out cheap.
Probably credibly worth ~$100-$110.
There's an entirely separate discussion on the strategic merits of this transaction particularly in light of the Tennessee's and Arkansas' regs + Hawley/Warren bill. Net net though, particularly with Midterm results in hand, this is a good strategic move by CVS.
Post from 4 years ago. Small independent pharmacies have a better chance now with the elimination of spread pricing and death of 12,000 sq ft combined front store and Rx fill in back. Retail Rx needs to get paid more for fill as now more than ever in the age of AI, there is value-added when real people are there to answer questions. Plans and government need to mandate that #PBMs pay more for Rx fill !!!


Expect $CVS to sell Pharmacy Unit to PE similar to Walgreens sale to PE Sycamore Partners -- about $10-$12 B in cash plus DAR (Divested Assets Rights) to sale of mail order to a big Rx distributor. Two questions remaining: (1) what retailers are there left who will pay for customer Rx records these days? $WMT ? regional grocery chains? (2) how will PE get rid of long term leases on 1000s of 12,000 sq ft. stores? ( calling all Dollar Trees, Dollar General, Family Dollar Store and 99 Cents Only Store :(

Competition senses $CVS management will be preoccupied with divestiture over the next two years. Caremark (and ESI ) #PBMs vulnerable to BCBSs finally ending contracts for adjucation, rebate management and mail order in the next 2 years. BCBSs, not small startups, biggest threat to PBM 80% market share over the next 2 years.

Post from 4 months ago. $CVS will sell retail business to private equity who will close 12,000 ft stores and move Rx retail to small 3000 ft stores.

Smart move by $CVS. Retail and mail order Rx fill margins no longer covering front store losses. My napkin estimates of value unlocked. Market cap before $100B = $120 B Aetna #PBMs Caremark, but - $20B Pharmacy. Market cap after $120B Aetna / PBM and give away pharmacy to PE who will sell mail order to Rx distributors and declare bankruptcy for retail like Rite Aid

Ads like these from the leading full stack inference provider @baseten will do more to blunt the pricing power of the frontier lab duopoly than the @FTC or the @dojphofficial Yea, startup AI infra market makers


$EVGN worth 10-20x just for its accumulated data to be used to fine-tune other LLM drug discovery models of well funded US startups and public Pharma. Witness $GOOG buying bankrupt Spirit Airlines just for its data. Could also split data buyout into drug discovery and ag chemical discovery . Easily data alone worth 20x current valuation
My counterfactual to assumption economic institutions can't keep pace with Tranformational AI:
Full Stack Inference Providers : @baseten , @modal , @FireworksAI_HQ and others
My Taglines:
"Turning stateless workflows into stateful capital"
"Creating competition for the frontier lab duopoly"
"Greatly reducing procurement transaction costs via marketplaces" #econtwitter @econD47

Markets and price signals deter AI monopolization. It is startup inference providers with LLM price transparent choice routers, not the Chinese, who have turned inference into a commodity, calling into question the sustainability of @AnthropicAI @OpenAI 60% -80% margins. Kudos to @baseten @modal @FireworksAI_HQ @daytonaio With 10+ fast followers, only moat how deep the stack - router, harness, post-training.. cloud sandboxes and VM. Example below of @daytona sandbox pricing

Suggestion for DtC cash pay healthcare: more emphasize on low cost - walk in UTI urine test, followed by fast Dr. video and appropriate antibiotic Rx if positive

Entrepreneurial alert: massive shortage nationwide of Estradiol due to FDA reduced side effects in black box warning that has greatly increasing demand.

#econtwitter There is starting to emerge within economists circles two schools of thought on the ability of economic institutions to adapt to transformative AI (TAI) - what I call “The Stanford School” and “The Hayek School” Below is lede to @DigEconLab recent post announcing new monograph.
Here is my reply
A counterfactual to @DigEconLab @erikbryn premise that “TAI advances faster than economic institutions can adapt”>> rapid rise in startups success of @OpenRouter @baseten offering auction market design routers-harnesses-post-training low transaction cost competition between frontier
LLMs and open weight LLM.

A counterfactual to @DigEconLab @erikbryn premise that “TAI advances faster than economic institutions can adapt”>> rapid rise in startups success of @OpenRouter @baseten offering auction market design routers-harnesses-post-training low transaction cost competition between frontier
LLMs and open weight LLM.

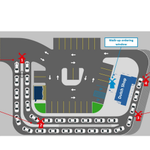
A big frustration of users of GLP-1 and other self-injectables is having to refrigerate continually when traveling. The Big 3 #PBMs have no solution. @heyepic is likely to solve that with recently announced Prescription Marketplace via Rx fill routing and re-routing in MyChart at Point of Phone (PoP) See my mock-up>>>
