

Netflix VP, hobbyist stock picker, Past: Rippling CPO, CIO@JPM CIB, EVP @lyft & Googler, I walk a lot. I live to eat, I restrict hours. Dabbling in calisthenics
San Francisco
Joined July 2008
- Tweets20.1K
- Following1.2K
- Followers1.2K
- Likes3K




Pinned Tweet
This is an excellent post by my former boss @RamaswmySridhar.
I encourage everyone to read it carefully and fully appreciate the various industries and business models he outlines, all of which have some type of risk of ruin.
However I am going to take the other side of this debate and make the ominous "this time is different" argument.
Before I start I would to qualify my position, the most likely scenario is a serious market gyration due to an air pocket where supply of AI h/w overshoots demand. The sooner we get there the better but I still think this is very different than 2000 tech bubble and a downturn will be short lived if at all.
The two core differences IMHO are
1) Circular financing offered by massively profitable (over-earning) vendors could be a feature not a bug
2) Digital goods in general and more so Tokens (intelligence) have ~infinite elasticity of demand
The 2nd one is quite obvious not just because of Jevon's paradox but rather because of the rapidly growing ecosystem of businesses (new and old) that consume tokens to enhance existing services or create new ones. This is especially true because it's still the case that one of the easiest ways to get better outcome is to brute force N attempts in parallel and pick a winner.
However (1) is the more interesting one, obviously controversial and admittedly I'm on Hopium as I type this.
The scariest part of this CapEx cycle is the fact that GPUs go through rapid cycles of improvement, hence they are perishable goods, so unlike the Dark fiber that was lit up 15 years later, and old GPU is worthless. Given we have plenty of A100s in production it's obviously more complicated but the risk is very legitmate.
Before focusing on GPUs/Memory, let's remember that the CapEx bill includes many other components, most of which have far longer lifetime, so one can argue that only 50% of the BOM is perishable.
Back to vendor financing, if you look at it from the Chips sector perspective, they obviously want to plan for success and like many others assume that oversupply situation is merely temporary so given they have extremely high gross margin (SK Hynex just reported 80%), they have many ways of handling the air pockets scenarios.
The easiest one would be to lower pricing and not hold their customers into the LTA they signed, because most of them are too big to fail and the vendors have no interest seeing the industry collpasing.
While "extend and pretend" is often mocked on X, it's a completely logical approach for lenders in commercial real estate.
Back to Chips, given the perishable nature and high gross margins, the vendors can keep prices high and offer "trade-ins" for the older equipment.

I think it’s due to the SPCX deal, nearly $3B of costs in Q4
fool.com/investing/2026/10/1…


$GOOGL on call: "Given the supply constraint environment, we started utilizing third party compute capacity at the end of Q3 and will ramp usage in Q4. We expect margin headwinds in the near term as we utilize this capacity. Moving to investments, our full year 2026 CapEx guidance range of 195 to $205 billion remain unchanged. We continue to expect our CapEx to increase significantly in 2027, and will provide further details on our Q4 call."


Eisar Lipkovitz retweeted

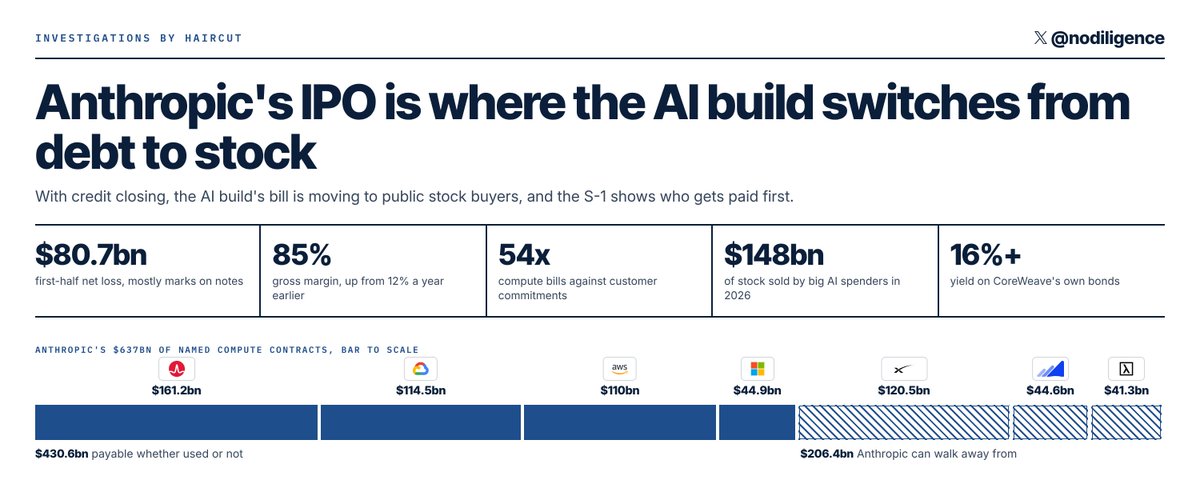
anthropic is probably the best business in AI right now and i still wouldn’t touch it on day one. the whole thing is set up for suppliers and insiders to sell into the index buying.
Interesting discussion, IMHO we are so far from getting there, not because of the quality of the Tech, but what needs to change in adoption and human behavior for the question to be even relevant

I’ve been thinking about this a lot. This will ultimately come down to Lucas and Hayek. Lucas because people will strategically adjust behavior to the expected policy (the behavior of AI). Counter is AI will be perfect forecasters, so they’ll anticipate adjustment, but you’ll get into infinite regress. Hayek because will AI be able to adjust for local and private information? The beauty of the price system is that it reduces all of that complexity, including the issue of strategic responses, into a finite set of statistics that clear the market. I think the only way that an artificial intelligence would be able to do. This is to have an actual structural model of every individuals behavior, including how they adjust to changes in economic environment.
Eisar Lipkovitz retweeted

A few ways to look at Anthropic inference gross margins (Q2 '26):
1) 88% -> most lenient: revenue - inference costs
2) 71% -> middle ground: revenue - inference costs - channel partner costs (mostly distribution fees paid to $AMZN, $GOOG, and $MSFT)
3) 35% -> most punitive: revenue - all compute costs (inc. training & free tier) - channel partner costs
All numbers are estimates given limited disclosures in the S-1.
$ANT

I found what @thespencerwalsh surprising and indeed on the earnings call this came up as a question.
Via
techcrunch.com/2026/10/28/mi…
sec.gov/ix?doc=/Archives/edg…
"For the three months ended September 30, 2026, we recorded revenue from commercial arrangements with OpenAI, inclusive of revenue-sharing payments, of $10.0 billion. "
On the call GS analyst asked
"Gabriela Borges, Analyst, Goldman Sachs: Hi. Good evening. Thank you. Satya, I want to stay on this topic of breadth because you had a comment in the prepared remarks talking about how MAI can now be comparable to leading models within 3-6 months of their release. At the same time, you have OpenAI at 11% of revenue in the quarter. Maybe just take a step back and give us your latest thinking on how you think token mix and token value is going to evolve between the frontier MAI, and maybe what some of your more sophisticated enterprise customers are doing from a proprietary AI strategy standpoint. Thank you."
investing.com/news/transcrip…


So $MSFT Azure revenue from OpenAI is ~$10B growing ~133%? And Azure revenue ex. OpenAI is ~$23B growing ~29%?
Eisar Lipkovitz retweeted

Reviewing futures tonight and its interesting to see Russell futures making highs of week here now +0.6% with Nasdaq down -1% on the GOOGL miss.
Rotational action maybe tomorrow with Russell small caps now confirming a bullish reversal pattern this week and 8/21 EMA bull cross as well on $IWM with 80% rule on the month which can target 290 but maybe into early Nov


Eisar Lipkovitz retweeted

Microsoft $MSFT CFO Amy on what drove Azure's 48% YoY growth:
“Foundry rev more than tripled YoY”
“...efficiency gains across our GPU fleet, that allowed us to allocate additional capacity to customers, as well as higher rev per token...”
“Across our CPU fleet, engineering work enabled us to identify and monetize underutilized capacity this quarter, helping us serve more of the growing demand with our existing capacity.”
“We had higher token pricing than we expected in the quarter.”
“Token pricing will create a little bit of variability.”
“...we still have demand that exceeds supply.”


Eisar Lipkovitz retweeted
Well, well:
Moonshot and DeepSeek are turning to OpenAI's GPT-6 Astra as a distillation target after Anthropic cracked down on such practices.

Eisar Lipkovitz retweeted

Israel 2026 Elections Update by the CEC (additional 100,705 votes have been added):
5,147,946 votes counted
11,757 polling stations
As it stands:
Netanyahu Bloc: 53 seats
Change Bloc: 48 seats
Arab Parties: 19 seats
Chart by @BNews_Network


Israel 2026 Elections Update by the CEC (additional 171,490 votes have been added):
5,047,241 votes counted
11,542 polling stations
As it stands:
Netanyahu Bloc: 53 seats
Change Bloc: 48 seats
Arab Parties: 19 seats
Chart by @BNews_Network


Eisar Lipkovitz retweeted

I want to give a shout out to @parkerconrad at @Rippling . We've been squeezed by @Workday for years. And the antiquated platform that @Workday had which we put in place in the process towards going public led to a ton of broken processes and extra staffing of workday consultants and vendors on top. Millions of dollars of total burn on a system which we used 30% of. I was told we would be forced to renew for another year with Workday 2 weeks ago. Gun to our head. No choice. I reached out to @parkerconrad on a saturday afternoon on linkedin and had a response back from him in less than 30 min. It was amazing. We moved over to @Rippling today. We are going to save money, time and brain damage and streamline our operations dramatically in finance and HR as a result. Thank you @Rippling team and @parkerconrad for showing us how a large company can move fast when its founder led. @aneelb your team should take note. $BETR
Eisar Lipkovitz retweeted

New: spending on Anthropic models on OpenRouter hit a new peak last week, up 47% from the summer high during the week of June 8.
Opus 5.5 was the top model by spend over the last 7 days across 20 of the 29 task categories we currently track.
openrouter.ai/rankings#task-…

Eisar Lipkovitz retweeted

WHY ON EARTH ARE WE TALKING ABOUT THE DEFAULT RISK OF ANTHROPIC?
A prediction market is taking real money on an Anthropic bankruptcy by 2028. Look at the balance sheet before you take the other side. Anthropic holds $112bn of cash and cash equivalents plus $19bn of short-term investments, $132bn in all. That is the third-largest pile in corporate America, behind Berkshire and Alphabet, ahead of Amazon, SpaceX, Meta and Microsoft.
Two things about that cash that nobody has priced. First, it earns. $132bn at a 4% bill yield is roughly $5bn a year of interest income, and that is before anyone counts a token of revenue. The company turned an operating profit of $974m in Q2. Add the yield on the cash and the cash-flow-positive story is not even close; it was already there, and the income on the pile was never part of the calculation.
Second, the burn. Over its entire lifetime Anthropic has burned under $13bn of cash, less than a tenth of what it holds today, and the worst year was 2025. So let me make the burn timeline, in a risk scenario, for the people on the other side of that contract.
At the Q2 run-rate the pile does not fall at all. At $25bn a year, twice the worst year so far, the cash lasts to 2031. At $50bn a year, four times the worst year, it lasts to 2029. At $100bn a year, the entire compute bill with zero revenue, it lasts past 2027.
And in all of this, we haven't even considered that they are about to raise even MORE cash.. The credit/default risk panic around AI is absolutely hysterical.

