

Concentrated Global Quality Growth | Pricing Power | FCF Growth + Barriers to Entry | Linearity | Book: https://teapawt.net/t.co/MEzmc2pDnx
London, UK
Joined January 2022
- Tweets9.1K
- Following574
- Followers83.4K
- Likes11K





Pinned Tweet
If you're looking to grow as an investor, then I have written a book and have created a spreadsheet of quality growth companies that features quality, linearity and valuation metrics.


Long Equity retweeted
Here are a couple of corporate finance case studies that investors would benefit from understanding.
1. SBC isn't the whole story.
Qualys consistently maintains their stock based compensation at around 20% of their operating cash flow. For many investors this is too high. But what many overlook is that this high SBC rate isn't actually causing any dilution. In fact, their shares outstanding are consistently and significantly coming down. So instead, their SBC should be seen as just another cost of doing business. If we look FCF/share, we see that it is consistently going up. Plus their FCF-SBC margin is also consistently high. In other words, look beyond just a high SBC % and consider what does this actually mean for the business. Is it just another expense or is it actually being used to dilute the interest of shareholders?

Here are a couple of corporate finance case studies that investors would benefit from understanding.
1. SBC isn't the whole story.
Qualys consistently maintains their stock based compensation at around 20% of their operating cash flow. For many investors this is too high. But what many overlook is that this high SBC rate isn't actually causing any dilution. In fact, their shares outstanding are consistently and significantly coming down. So instead, their SBC should be seen as just another cost of doing business. If we look FCF/share, we see that it is consistently going up. Plus their FCF-SBC margin is also consistently high. In other words, look beyond just a high SBC % and consider what does this actually mean for the business. Is it just another expense or is it actually being used to dilute the interest of shareholders?
3. Revenue growth isn't the whole story. Hamilton Lane has significantly and consistently grown its revenue over the last 10 years. However, their FCF has been relatively flat. That's because they've seen their profit margins come down and have consistently issued new stock, making their FCF/share quite volatile.

1
1
1,551
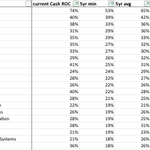
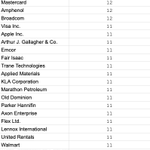
I sorted the S&P 500 constituents by the lowest their cash return on capital has been over the last 5 years.
The lowest Adobe's Cash ROC has been was 53%, while it's currently 74%. Will this continue?
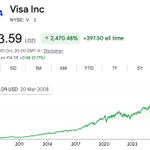
From this list I own Mastercard, Visa, KLA, Fortinet, Lam Research and Cadence.


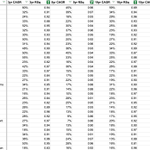
Looking for linear compounders? Here's a list of US equities with high share price growth with low volatility.


LONG EQUITY PORTFOLIO - OCTOBER 2026
--
YTD = 27.2%
Cash return on capital = 32%
FCF per share CAGR (5yr) = 25


In my 15 years of investing, each time I've learnt a new concept, I've distilled it into a single slide.
I've compiled a 17 private slide deck covering:
• Markets
• Capital allocation
• Pricing power
Want the full 17-slide PDF?
Like & Bookmark this post.
Reply "SLIDES" below.


Here’s the link to download the slides:
subscribe.longeq.com/long-eq…
Let me know what you think!

1
2,551