

maxvol retweeted

"A Breakthrough": White House Says Strategic Bitcoin Reserve Announcement Is Imminent zerohedge.com/crypto/breakth…

maxvol retweeted

It's a thoughtful, important question, and ultimately it's the #1 question investors still have as it relates to terminal value.
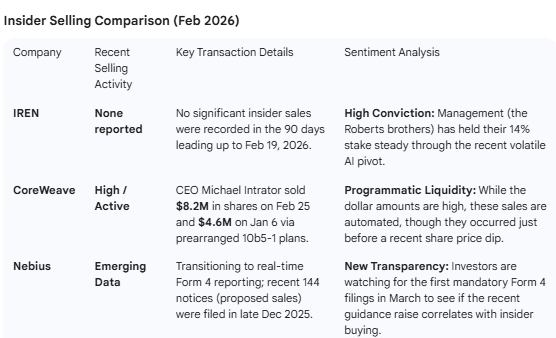
First let's level set on the #'s: $NBIS is targeting 3GW+ of secured power by the end of 2026 (which would put them in-line with what $CRWV has today). $IREN already has ~4.5GW secured today and that excludes the "multi-GW, international pipeline".
This is the most important datapoint that investors miss because IREN is intentionally conservative about the size of their pipeline. We know (i) they've said they could have additional sites in TX approved in batch zero, (ii) we know they're investing aggressively in ads in Australia (which they wouldn't do if they didn't have a site or sites), and (iii) we know they typically target 1GW+ whenever they can. If we assume just one additional GW in TX and one additional GW in Australia, which we could find out about as soon as this year, that would put them at ~6.5GW which is over 2x NBIS and also more than NBIS and CRWV combined (sit w/ that for a second). And I've seen credible estimates from @Agrippa_Inv @FransBakker9812 etc. that suggest the true size of the secured + pipeline portfolio could be as high as 10 GW+, which wouldn't surprise me since IREN has been aggressively pursuing secured power since before 2020. If it's truly 10 GW+, that would put IREN on par with the hyperscalers themselves in terms of the size of their GW portfolio. Sit with that for a second and remember that as we peel this question apart further below.
(As an aside, IREN trades for less than half of what NBIS and CRWV are valued at today. The GW per market cap disparity alone should be eye opening for a potential re-rate but let's stay focused on the question.)
The lead times to secure power, long lead parts, labor, etc. make building a portfolio as large as IREN's a 5+ year proposition. Absent significant M&A, NBIS will not catch IREN in the race to secure the most power & land. Which brings us to what actually happens once it is secured.
A huge difference between investors' perceptions of NBIS vs. IREN today stem purely from what each has chosen to talk about to-date. NBIS has done a phenomenal job locking up contracts and building / delivering a software solution that attracts clients. But they haven't actually built all the GW nor have they secured nearly as many as IREN (and a huge chunk of NBIS portfolio is 3rd party leased so they pay colo fees eating into their margins that IREN does not pay). IREN has been focused on securing GW of power and now building out a vertically integrated construction capability. The question that I think investors are missing about NBIS is this: can NBIS actually build out the GW they've contracted and how many more GW can they actually secure to continue scaling their business? That's a real question mark and if NBIS has execution fumbles on owned sites or third party leased sites, that is a major headwind that could dampen investor (and customer perception).
With IREN, investors are actually asking the opposite question. The question we're talking about here is: "Holy crap, IREN has a massive GW portfolio and they appear to be able to build it. What happens long term if that competitive advantage goes away because GW are no longer scarce?" Fair question, but let's be clear that it's different than NBIS questions for a reason.
Let's say hypothetically that IREN can build out the full 4.5 GW by 2030 (a stretch) and let's say they have another ~5 GW from there to build out. The existing ~4.5 GW would produce a ton of cash flow (particularly if they can re-contract powered shells that don't need to be rebuilt) and enterprise value that could be used for M&A to acquire additional capabilities. IREN already has a software solution that they're discussing w/ customers - it's just not a capability they've advertised heavily since most large scale compute customers want bare metal. But let's assume for a second they don't have that capability. M&A is always an option, and what they have today is the most scarce, in-demand resource that nobody else has at the same scale, and that gives them a lot of optionality to acquire capabilities even further up the stack (e.g., could they buy Fireworks or Together AI?). Just because NBIS has certain capabilities today (while relatively lacking the really in-demand resource which is secured GW), does not mean those capabilities can't be developed/scaled in-house or acquired over the next five years. And it's no accident that IREN just hired a senior M&A professional.
Which brings us to the ultimate question: re-leasing risk if GW are no longer as scarce post 2030 as that's the source of cash flow that gives them post 2030 optionality.
First off, the hyperscalers have been growing their own GW portfolios for their own cloud offerings for two decades now and the demand for cloud has only gone one direction. So there's nothing to suggest that cloud demand won't be there post 2030.
Second, we know that the hyperscalers themselves don't want to sign cloud contracts and prefer colo, because cloud is more expensive (which @danroberts0101 noted in the recent IREN X Space with @FransBakker9812 and @bitcoinbutcher1). That's a pretty good sign that it's the right market to be in as the cloud businesses of the hyperscalers are high margin and a huge source of their own enterprise value.
Which makes me think the obvious answer to "How do we know IREN can monetize their GW post 2030?" is this: IREN will become a hyperscaler themselves and sell cloud compute directly to enterprises (i.e., serving the same set of end customers as the hyperscalers' own cloud businesses). That is literally what @mikealfred has been saying the long term opportunity is so I have no reason to doubt it's on the potential strategic roadmap. And it's clear they're already pursuing it: why else would they be advertising so aggressively in San Francisco and Australia? There are only a handful of hyperscalers and they already know about IREN - the only logical explanation for the ad blitz is to attract the direct attention of prospective enterprise cloud customers.
Now, let's hit a few specifics around this topic.
We know from channel checks (@ShanuMathew93 posts some of the best) that enterprise cloud deployment sizes have expanded from ~10 MW to ~60 MW of late. If we assume there's not a single frontier lab or hyperscaler buying from IREN and no enterprise needs more than ~60 MW (highly doubt that), across a ~10 GW portfolio globally, that requires ~167 enterprise cloud clients. Are there that many globally by 2030 with the explosion of growth we'll likely see from AI (and other exponential growth vectors)? Probably. But the reality is, there will be much larger consumers of compute that should prefer IREN's cloud offerings over hyperscalers. Why?
Generic enterprises will at some stage be wary of the hyperscalers training their own models on customer data. Legal agreements can say one thing, but at some stage you have to ask yourself do you really want your most sensitive data on a hyperscalers' cloud if they directly benefit from using your data to train their own model? As models become more powerful, this will increasingly be in the back of enterprise customers' minds and it's an easier FUD vector for IREN to sell into over time.
The natural response to that is a shift back towards on-prem, but AI cloud compute is a much higher degree of difficulty than cloud storage, and so it makes sense to have a cloud provider who doesn't have a model themselves to fill that gap. IREN fits that gap perfectly and it perfectly positions IREN to capture cloud demand from enterprise clients who if not for the complexity of managing AI cloud compute would otherwise prefer moving back to on-prem.
But that's not all, there's another massive non-hyperscaler customer base for AI cloud compute that we shouldn't set aside: frontier labs themselves. OpenAI has built a large compute portfolio but they still need to continue scaling. And Anthropic is deeply short compute right now with their current outage issues - @DavidSacks laid this out on the latest @theallinpod episode, specifically that Anthropic has scaled ARR exponentially but is now running hard into real world linear constraints around compute (echoing what @danroberts0101 has been saying since IREN was founded).
If Anthropic and OpenAI buy compute from the hyperscalers and the hyperscalers are trying to compete with their own models, the hyperscalers can throttle the compute of the frontier labs to advantage the hyperscalers' own models, which @chamath clearly laid out. That drives Anthropic and OpenAI to either (i) build their own compute (not a core competency) and/or (ii) directly into the arms of IREN who can scale compute faster and manage it for them while not having an incentive to throttle said compute to advantage their own model.
And all of the above matters greatly to $NVDA, $AMD, etc., who all have an interest in the success of all neoclouds (including CRWV, NBIS, and IREN) to reduce their own customer concentration with the hyperscalers. And similar to the software capability discussion, it's worth nothing IREN likely has access to the same strategic financing levers with NVDA that CRWV and NBIS do which @danroberts0101 alluded to last earnings.
Finally, let's play out a 2030 scenario where demand for GW slows and IREN is competing with other neoclouds on price. First off, between now and 2030+ there's plenty of time to acquire additional capabilities to ensure that's an apples to apples fight (while others are fighting to secure GW in the next five years, IREN can take the time to develop / scale / acquire other capabilities if needed). But the more important point: IREN actually owns all its land and power so they can undercut on price because they don't need to pay colo fees. So even in the downside scenario, they have a competitive advantage to bring to bear and they can spread their opex over a larger GW portfolio which requires less of an overhead markup on their compute pricing.
(I also think as an aside that it's interesting NBIS investors tout the software capability as a differentiator when the whole goal is literally to build ASI that might make any and all software capabilities obsolete and the only thing that enterprise cloud clients might need in the future is land / power / shells / compute since the software layer itself could be ubiquitous. It's amusing to me that the question IREN faces is whether the only thing ASI can't make (e.g., land / power / shells / compute) will be less scarce, whereas competing neoclouds aren't faced with the counterfactual: what if ASI blows out the differentiation you claim in your software stack?)
If I boil all this down, the question investors are struggling with is "What happens if GW become plentiful post 2030 and IREN can't sell to hyperscalers and they have to compete on more than just bare metal?" And the answer in short is:
IREN can become a hyperscaler themselves and has spent the last 7+ years acquiring the scarcest, most in-demand resource while building the most vertically integrated capability set to scale it - they've done the hardest work up front that others haven't and now for the next 5+ years can compound that advantage. That gives them a portfolio of GW that potentially rivals the hyperscalers themselves and now over the next 5+ years it is time to become a hyperscaler by selling directly to enterprises that if not for the complexity of AI cloud compute would otherwise now prefer on-prem (vs. the hyperscalers' cloud offerings) as well as frontier labs that desperately need to avoid the hyperscaler chokehold. And while competing neoclouds (e.g., NBIS, CRWV, etc.) scramble to secure GW to compete with IREN (and likely won't be able to secure them at the same pace or scale) and avoid paying co-lo fees, IREN can take the next 5+ years to not just scale their own massive GW portfolio, but also bolt on additional capabilities above and beyond bare metal by scaling / developing their in-house offerings or simply acquiring them through M&A.
And if IREN can do that, the re-rate potential would be absolutely enormous since it would address the #1 overhang on terminal value in many investor models today.