

Founder, CEO, Chief Analyst @MoorInsStrat. Co-founder of @TheSixFiveMedia and @Signal_65. Ex-AMD CVP & Fellow, Compaq and AltaVista dot-com bomb participant.
Austin, TX
Joined May 2008
- Tweets73.1K
- Following4.8K
- Followers69.6K
- Likes74.1K




Pinned Tweet
Microsoft and Oracle last reported more than $1.3 trillion of signed contracts they haven't delivered yet. Both say demand is outrunning supply. The AI question isn't demand. It's how fast they can build. Thursday I'm on @YahooFinance right after $INTC reports. It's The Week Ahead In Technology for October 26, 2026.
$MSFT, $GOOGL and $AMZN report back to back. I care less about beats than backlog becoming revenue.
@Oracle hosts AI World and its investor day. It expects about 13% of its backlog to become revenue within a year; Microsoft, about 30%.
$INTC: the 14A customer-commitment window is open. Customers set the clock.
$KLAC, $SKHY and $NOW report. ServiceNow: agents in booked revenue, not pilots.
I'm in New York for @cloudera EVOLVE26 to talk sovereign AI.
So who turns backlog into revenue fastest?

Meta's consumer AI comeback looks real. The bill already is: last reported quarter, capex ate nearly every dollar its business generated. It's The Week Ahead In Technology for October 19, 2026.
Tuesday I'm in Washington at the @Google Public Sector Summit.
$META guided $130 to $145 billion of capex this year. Zuckerberg says it could sell compute at a big markup, but AI services earn higher margins. I want next year's number.
@NVIDIAGTC Berlin: Jensen Huang's keynote. Boardrooms want sovereign, secure data.
$SPCX, then $TSLA: I'm listening for chips and compute.
$IBM and $SAP: show me AI agents in booked revenue, not pilots.
$NOK: is the @nvidia deal paying off?
Carry-over: chip stocks fell eight days straight. I've said it's just another scare.
Can Meta's comeback pay the bill?
Traveling on Sunday for business sucks. I’m 10 hours in and still not to the hotel yet. Had a great weekend visiting family in Tallahassee. Not an easy city to get out of.
Quick take on iPhone Duo from a guy that has evaluated thousands of devices.

Quick take on Duo:
The Duo gets a lot of UI things right, better than many of its competitors. However, it’s still not perfect and I believe will still take some tweaks to get perfect. This is especially true for left-handed users or anyone who uses the front screen a lot for web browsing. A lot of the UI choices seem to push you towards unfolding the device, which I believe is a function of the smaller outer screen. I found myself unfolding the Fold8 way more often than the Fold8 Ultra which has the much slimmer and taller design.
However, the Duo like many of its other foldable counterparts still falls short in many ways against a traditional candy bar. The first and most common way is in the camera performance, Apple went for a lower resolution Center Stage selfie camera (12MP) over the rest of the iPhone line including the iPhone Air. I was told this was because it’s a foldable. The main cameras are also a sacrifice compared to the iPhone 18 Pro with no telephoto lens. Competitors like Xiaomi don’t have this problem.
Battery life is also a compromise compared to the iPhone 18 Pro Max or any high capacity Android phone. But I will say that in general foldables have become all-day so while battery life isn’t as good, it is good enough. You also lose FaceID which I believe will come in the next generation. But all of these pitfalls aside, the experience of having a large screen whenever you need it and being able to easily run two apps side by side is so great that many are willing to sacrifice the pitfalls. I also believe that this is why Apple implemented Handoff so that you can easily use your phone with the better camera along with the foldable.
Additionally, I believe that Apple cleverly figured out that implementing a matte texture to the screen helps with reducing the visibility of the crease. While the crease is not entirely gone, it’s mostly imperceptible to the average person unless they really look for it and the user won’t notice it at all. Ignoring that aspect, many of Apples competitors are in a similar state and will likely add Matt coatings to their next generation to help with create visibility.
Ironically, the $2000 price is actually quite good and competitive with the rest of the market. I believe that Apple would actually be more expensive, which leads me to believe that it wants to capture market share from more than iOS users who have been waiting for a foldable iPhone for the last 10 years. I think the Duo is a good buy for anyone that’s been looking for a foldable but didn’t because they we’re all Androids. But foldables do have a price problem, prior to the chip crunch and memory price increases foldables were starting to get into reasonable and attainable territory thanks to flip phones. I believe that Samsung has the right three-tier strategy to properly serve the market and I expect that Apple will go that path as well, in fact for quite some time flip phones were the highest volume foldables.
I have been testing this phone for the last few days and played with it at launch. I think the biggest delta between those two experiences was finding apps that haven’t been optimized yet. It has been fascinating to watch how quickly apps are getting updated for Duo, but I believe it will be a few months before the majority of apps are properly optimized. I also expected that Apple would drive this kind of rate of improvement and overall visibility for these issues in foldables which I believe will be a rising tide for the whole foldable market. I haven’t done extensive performance testing yet, but all signs point to it being on par with expectations, even if some reviewers have noted some heating.
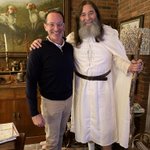
My younger brother and his wife love throwing Halloween parties and goes all out on costumes. So, is this Jesus or Gandalf?


Seems like common sense to lock the gate to the wild animal agent cage. But what do I know.

new from me: OpenAI has begun cutting off internet access for its most capable artificial intelligence models during the training process in response to prior incidents in which its systems breached other companies, including @huggingface.
cc @Techmeme
bloomberg.com/news/articles/…

The harness makers suck at setting up a 2nd or 10th device. Every single instance, add custom end points, MCPs, memory, etc.
I’m looking at you @openclaw and @NousResearch.
I thought the Nous Portal would fix this but nope. Nous did, of course, make it easy on their cloud to buy paid model access through them. 🤔
Enjoyed chatting with Mercedes F1 Chief @totobossf1 and HPE CEO @AntonioNeri_HPE about tech’s impact on racing.


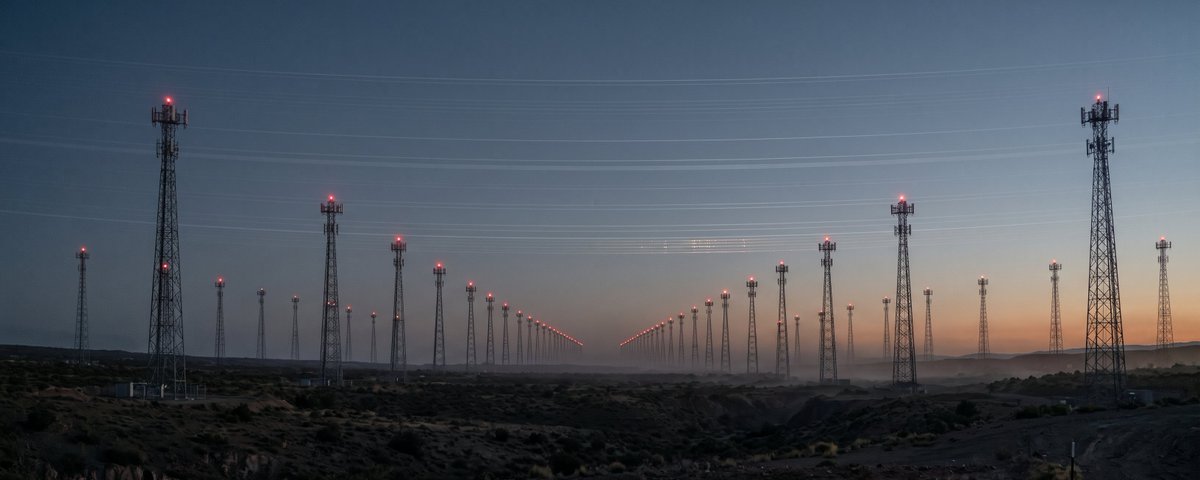


. @Intel_Foundry has the first major truss in at Ohio One, and Arizona Fab 62 tool install is fully underway for operations by the end of 2028.
The headlines say Ohio is five years late. I said back in 2024 that the original date was overly ambitious for a first fab in a new state. Pacing it to customer demand is the right discipline.
What matters now: Ohio is designated for 14A and beyond, and @intel says it can pull the schedule in if customers commit. We are inside the 14A decision window @LipBuTan1 laid out, the second half of 2026 into the first half of 2027.
The truss is the shell. Customers set the clock. $INTC

Building semiconductor leadership requires both innovation and the manufacturing capacity to bring it to scale.
In his latest piece, Naga Chandrasekaran highlights Intel Foundry’s growing U.S. footprint, including progress on our Ohio site.
Read more: ms.spr.ly/6010avfyk
#IntelFoundry
$NOK Q3: BEAT, and down ~11% at midday anyway. It's trading on cash, not demand: lower cash conversion, €400M more in working capital, and a beat partly pulled from Q4 that didn't raise the year.
The numbers:
-Net sales €5.15B, +9% at constant currency, vs €5.05B est: BEAT
-Non-GAAP (comparable) EPS €0.09 vs €0.06 est: BEAT
-Comparable op profit €605M vs €453M est: BEAT, €93M over the top estimate
-FY26 op profit guide held at €2.1B to €2.6B, above midpoint, vs €2.40B est: MEET
Ten takeaways beyond the numbers:
1. Non-consensus: the old business carried the quarter. Mobile finished €132M above the street estimate: BEAT, helped by radio deliveries pulled from Q4. Network Infrastructure, the AI engine, was €7M short of its estimate: MISS.
2. The pull-in costs Q4. Hold the €2.40B street number and Q4 profit expectations fall about €150M. My math.
3. Cash is the "problem" investors are trading on. Free cash flow was negative €99M; conversion was cut to 35% to 55% from 55% to 75%. Q4 has to generate €1.0B to €1.5B to get there. My math.
4. Nokia says the extra €400M is 2027 IP and optical capacity, not pre-buying on price. On Oct 1 I wrote that Micron's customers were prepaying. This cycle pays parts makers first and leaves system vendors holding inventory.
5. AI & Cloud orders were €1.5B, +118% YoY, but down from €2.8B in Q2. Lumpy, not broken: €5.3B booked this year against €1.4B of sales, and most ship within 12 months. My math.
6. 2027 is the number: Optical plus IP up 25% to 30%. Nokia tells me the AI & Cloud slice is essentially in backlog, mostly hyperscaler, so little credit risk. Telco still has to be won, and the math counts only secured supply. Same backlog-to-revenue test I set for Broadcom in September.
7. A year after @nvidia put $1B into Nokia for AI-RAN, the AI money lands in IP (+43%) and optical (+18%), not RAN. NVIDIA is investor, partner and data center competitor. Same co-opetition I flagged with Cisco in June.
8. AI growth dilutes before it pays. Network Infrastructure gross margin fell 150bps to 41.2% on AI & Cloud ramps in IP; Nokia guides a Q4 recovery. Mobile still earned €420M of operating profit to Network Infrastructure's €216M.
9. @justinhotard called the supply squeeze a structural cost increase, not just a shortage: chips, memory, circuit boards. Server shortages helped cut Core Software 13%.
10. AI-RAN is on the timeline my colleague @anshelsag laid out in September: commercial in 2027. Q3 added a live T-Mobile call, 19 operators and 20%+ spectral efficiency gains, and Nokia says live-network work runs about two months ahead of plan.
At $8.22 as of 12:09pm ET. AI selloffs come in waves, as I said Oct 15: five since DeepSeek by my count. Nokia says customer behavior has not changed.
$NOK

NOKIA $NOK Q3’26 EARNINGS HIGHLIGHTS
🔹 Net Sales: €5,154M (Est. €5.04B) 🟢; +10% YoY
🔹 Adj. EPS: €0.09 (Est. €0.06) 🟢; +50% YoY
🔹 Comparable Gross Margin: 44.6%; -20 bps YoY
🔹 Comparable Oper Profit: €605M (Est. €442M) 🟢
FY26 Guide:
🔹 Comparable Oper Profit: €2.1B-€2.6B
🔹 Network Infrastructure Growth: 12% to 14%
🔹 FCF Conversion: 35% to 55%
🔹 CapEx: €750M-€850M
Segment Net Sales:
🔹 Network Infrastructure: €2,158M; +17% YoY
🔹 Mobile Infrastructure: €2,902M; +5% YoY
🔹 Portfolio Businesses: €96M; -1% YoY
Other Q3 Metrics:
🔹 Comparable Oper Margin: 11.7%; +220 bps YoY
🔹 AI & Cloud Net Sales: +123% YoY; cc
🔹 Optical Networks: +18% YoY; cc
🔹 IP Networks: +43% YoY; cc
🔹 AI & Cloud Order Intake: €1.5B
🔹 Reported EPS: €0.03
🔹 Net Cash: €2,584M; -14% YoY
Key Updates:
🔹 Dividend per Share: €0.03
🔹 Infinera Integration: On track for completion by the end of 2026, one year ahead of plan
🔹 AI-RAN Call: Completed with T-Mobile and NVIDIA in a live operator network
Comments:
🔸 “In Q3, we grew net sales by 9% and improved comparable operating margin by 220 basis points.”

Looking forward to the conversation today.

Today, @PatrickMoorhead and @danielnewmanUV are at the @F1 US Grand Prix, speaking with @TotoWolff_ and @HPE CEO @AntonioNeri_HPE about the Mercedes-AMG PETRONAS F1 partnership.
From AI and advanced computing to real-time data, they're exploring the technology driving performance on and off the track.
Stay tuned for exclusive conversations from the event!

Enterprises and governments want multi-model based services. This was clear 3 years ago. Google leads with Gemini (which they should), added Anthropic, and now OpenAI plus hundreds of open models.

Today, we're bringing OpenAI models to Google Cloud's model garden.
We're now the only hyperscale cloud provider offering access to all three leading closed source LLMs—alongside 200+ other models—on a unified enterprise platform → goo.gle/4zJ0VZQ

So @Muse has camped out right near my condo for F1. A hospitality area. I was wondering who was playing music until 11 last night.


