






Wonder why google glass was creepy by meta ray bans are not! Early to market or new ones are creepy too?
Grok Bot, Instinct, Muse, Fo, Town, and a growing list of AI agents are hitting the market, all promising to get things done: book a table, buy tickets, compare products.
Under the hood they're probably very different. On the surface, they all look the same.
So who wins? 🧵
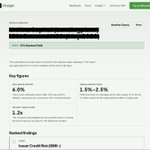
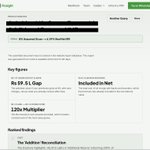
I've felt this building Finsight, an agent that spots mis-selling in financial brochures.
My bet: people would share non-private docs with a proactive "immune system" against bad products.
Progress is slow. Few want to trust an unknown agent on WhatsApp.

This is a problem for LA-X - mutual fund, insurance etc. Revolving facilities were easier to renew, with TL it is a fresh cycle. This is rough for fintechs in the space.

RBI proposes a draft that removes on-demand loans by NBFCs.
Means: No more overdraft like facility from NBFCs. This is important, because NBFCs could take security (like stocks, mutual funds etc) and give people a loan facility that behaves like a bank overdraft.
Meaning, you get a facility for 50 lakh, and you can draw any amount, say 10 lakh for a few days, repay it back, then take it again etc. You get charged interest only for the time that you have taken money, but the facility itself lasts a year or more, so you can do this many times over. Effectively, it's on-demand credit repayable anytime, without new loan agreements each time
This is a great facility, mostly because it can be used for temporary liquidity in a very short period of time, without needed to sell the stock or mutual funds you own. Now, if RBI's rules go through, only banks can do this. For you and me, this is a no brainer; banks have a 1 cr. limit on such overdrafts against securities. It hurts those that use such facilities to borrow more (only NBFCs can give higher value loans than 1 cr).
By restricting this to only banks - it will massively reduce the playing field for such loans. And it will have to change the business model for loan-against-mutual-funds startups to move to pure term loans (fixed term loans, repayable in EMI or bullet, no repeated taking of loan once returned)
Since this is an on-demand loan, the section pertaining to "demand/call loans" goes away. Meaning no loans that are flexible repayment whenever you want, etc.
This still leaves some hope - that if you need money, you can quickly digitally get a loan, with a digital pre-approval perhaps. But it has to have a fixed tenure and repayment plan, with perhaps a zero prepayment penalty. (Or just use a bank)
Also this hurts NBFCs that might on-lend to other NBFCs by taking securities as collateral. Don't know the impact of this yet.
I think it's a little regressive, this rule. Perhaps they could restrict the scale of this to say 5 cr. per borrower instad of removing it outright from NBFCs. Banks need competition to do better for customers.

Nothing wrong with sun drying but I agree it looks bad for a premium apt like Hiranandani. It is the builder issue because they are not mindful about making space, utility areas are just enough to fit a washing machine. Alt is people hanging clothes inside in passage ways - worse

Meet Finsight: Your AI Financial Guardian on WhatsApp 💡 #shorts youtube.com/shorts/KWg9Epn4U… via @YouTube

raghavb retweeted

Ship OAuth so I can build LLM features for my web apps that get billed to my user's existing OpenAI accounts
raghavb retweeted

Ok builders, here’s your playbook.
Prototype your product with the best frontier model. Cost be damned.
Validate the user experience.
Then, 6-8 weeks later when open-weight models catch up - move your production workloads there, and to smaller models where possible.
In that order. Don’t start with the cheapest model.

📢Meet Qwen3.8-Max — our most capable model to date.
Next week, the open weights of Qwen3.8-Max will be released, and Qwen3.8-27B is also going open-weights to meet you all!🎉
Qwen3.8-Max, a new bar for coding and cowork at 2.4T parameters:
- Autonomous coding: 10+ days of self-evolving development, from empty folder to production without hand-holding, complete project trace in the GitHub:github.com/qwen-code-dev-bot…
- Real work, real results: Production-quality deliverables across hundreds of professions.
- Long-horizon mastery: System-level autonomous planning with closed-loop adaptive learning, driving 500+ turns of chip design optimization and 365 days of e-commerce strategy.
- Native multimodal intelligence: Vision isn't just input — it's a continuous feedback loop for planning, execution, and self-correction.
💰Pricing:
Input: $2.0 / M tokens
Output: $6.0 / M tokens
Implicit Caching: $0.25 / M tokens
Start building with Qwen3.8-Max! 🚀
📖 Blog: qwen.ai/blog?id=qwen3.8
✅ Qwen Studio: chat.qwen.ai/?models=qwen3.8…
⚡ API: qwencloud.com/models/qwen3.8…

We spoke to 111 people who pay on time via UPI yet still can't get a loan. 78% had been rejected, often without knowing why.
Credit access is broken. Credit score awareness is low.
Legacy systems take time to change. Until then, we'll keep building.
Link in next tweet


raghavb retweeted
Tragic, what a way to finish. All my sympathies with this phenomenal Croatian team. I also had my career attacked by a computer! 🇭🇷
Thanks for Flue @FredKSchott was able to build Finsight Analyse on web using flue workflow. Fun to build. For the main agent we built our own harness, had not seen Flue project then.

Try a sample on the web heyfinsight.com/analyse
You get a shareable report that's live for 90 days.
PS: The web is slightly slower, we optimizing Finsight on WhatsApp to be fast.
