





Pinned Tweet
I'm a momentum and swing trader, and an investor.
I don't trade opinions. I read the data — and I trade what it says.
My charts stay simple:
• EMAs — 9, 21, 50, 100, 200
• Volume profile
• Anchored VWAPs and trendlines, when they matter
Every idea starts with a deep dive: where is the money positioned, where does price want to go, what breaks if I'm wrong?
Momentum tells me when. The levels tell me where. The data decides — I just follow it.
$TSLA is no longer just a car story in my eyes. The chart is breaking out just as the next chapter — driverless rides and robots — starts to look real, not theoretical.
Tesla just named Las Vegas, Phoenix, Jacksonville and San Antonio as its next Robotaxi cities, after logging 3.1 million autonomous miles with zero people injured. Dallas Cybercab rides start next month.
My take: if that rollout scales, the earnings path on the chart stops looking crazy.

• $V EPS: $3.48 vs $3.44 expected — beat
• Revenue: $12.14B vs $12.09B expected — beat
• Payments volume +9%, cross-border volume +14% — the consumer is still swiping
• Guidance: FY2027 revenue growth in the low double digits, EPS growth low double digits to low teens
• Stock reaction: −1.1% after hours to $397.26, after closing down 0.6% at $401.86
My take: a clean beat on both lines that still got sold — the bar was high after a ~15% run this year. I read this as profit-taking on a record year, not a crack in the consumer story. Visa also raised its dividend 16%.

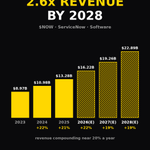
$NOW is breaking out of a tight flag just as it becomes the quiet backbone of enterprise AI. Companies aren't just buying software anymore — they're handing whole workflows to its agents.
The proof is in the demand: AI contract value already passed $1 billion and is tracking ahead of its $1.5 billion year-end target, with net new AI deals up more than 40% in a single quarter.
My take: this is a compounder, not a trade — the kind of name you hold while the AI story turns into revenue.

$PLTR is quietly turning into an AI infrastructure company, not just a government contractor. Its software is becoming the layer companies use to actually run AI on their own data, and the growth is following that shift.
The proof is in the U.S. commercial business, which grew 149% last quarter as enterprises rushed to deploy its AI platform, with total revenue up 93% in the same quarter.
My take: if that commercial ramp keeps compounding, the 2028 revenue trajectory on the chart is the story to watch.

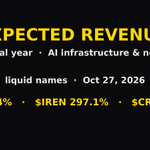
Fastest expected revenue growth, next fiscal year — AI infrastructure & neoclouds
• $NBIS +531.4%
• $IREN +297.1%
• $CRWV +150.8%
• $CORZ +111.8%
• $MU +106.9%
• $NVDA +90.6%
• $CLS +66.3%
• $AVGO +65.9%
• $APLD +56.6%
• $WULF +53.6%
• $MRVL +47.3%
• $TSM +46.5%
• $ANET +40.8%
• $HUT +27.3%
• $CIFR -2.8%
My take: the neocloud names sit on top because analysts expect their buildout to turn into revenue fast, while the chip giants grow slower off much bigger bases. I'm watching whether the smaller names actually deliver those numbers before trusting the top of the list.

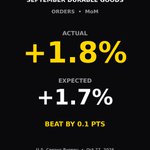
September Durable Goods Orders are out — a small beat on the headline.
• Actual: +1.8% MoM, to $345.4B
• Expected: +1.7% MoM
• Prior month: +0.1% (August)
• Ex-transport: +0.5% — a touch softer than the ~+0.6% expected
• Ex-defense: +2.2%
• Transportation led the gain: +4.6% to $119.8B
• Orders are now up in six of the last seven months
• Market reaction: stock futures were pointing higher into the print, with the 10-year near 4.98% — eyes now turn to tomorrow's Fed decision
The bull case: factory demand is holding up, and the headline beat keeps the growth story intact.
The bear case: strip out transport and the gain is modest — the underlying trend is steady, not booming.
My take: a solid, not spectacular print. I wouldn't chase anything off this one — tomorrow's Fed decision matters far more. What's your call — does this change anything for you?

$QCOM - If you don't know what is RS, Please look at QCOM.
It has got all the ingredienst for a move to 190$ and 200$, I am expecting a bazooka move on this.
185 c 10/30 at 1.8

• $VZ EPS: $1.31 vs $1.27 expected — beat
• Revenue: $34.31B vs $34.8B expected — miss
• The surprise: 406,000 postpaid phone adds vs ~195,300 expected, its best Q3 in five years, plus a $2B+ AWS dark-fiber deal
• Guidance: raised for a third straight quarter — FY26 EPS $5.04-$5.06
• Stock reaction: -3.5% on the day
My take: the market cared more about the revenue miss than the raise. I think the subscriber momentum is real, but the stock needs revenue to re-accelerate before it re-rates.

$ORCL is quietly becoming the AI cloud company. Management's own roadmap has its cloud infrastructure business going from $18B last fiscal year to $144B by fiscal 2030 — an 8x run.
The demand is already contracted, not hoped for: Oracle sits on $664B of remaining performance obligations, revenue customers have already signed for.
My take: this is the most underappreciated AI infrastructure story in the market.

$ALAB is quietly becoming one of the picks-and-shovels winners of the AI buildout. Its connectivity chips sit between the GPUs inside every AI data center, so as those buildouts scale, its revenue scales with them.
Analysts expect that to show up fast: revenue more than doubles in 2026 alone, to $1.91 billion, on the way to $3.83 billion by 2028 — 4.5x where it stood in 2025.
My take: this is the kind of compounding growth story I want to own before the market prices it like one.

$CEG is quietly becoming the AI power trade. America's largest nuclear fleet, now combined with Calpine's gas plants, sits directly in front of the data-center power boom.
The proof is in the earnings path: analysts see adjusted EPS climbing from $9.39 in 2025 to $16.80 by 2028, a 79% jump, as hyperscaler power deals scale up.
My take: the power behind AI is a better bet than another AI chip name — this is the bottleneck trade.

Fastest expected revenue growth, next fiscal year — fintech
• $GPN +60.4%
• $MELI +44.9%
• $SOFI +36.3%
• $AFRM +28.9%
• $FIS +27.9%
• $FICO +27.1%
• $HOOD +19.1%
• $AXP +18.5%
• $V +14.5%
• $MA +13.7%
• $XYZ +7.8%
• $PYPL +4.7%
• $COIN -21.8%
My take: the top of this list is all payments and marketplaces still compounding, while Coinbase is the one name analysts expect to shrink. I'm watching whether the big expected jumps actually show up in reported numbers before I trust them.

Most-shorted liquid stocks — short interest as % of float, as of Friday's close
• $WOLF 85.23%
• $CHWY 65.35%
• $LCID 60.35%
• $IBTA 43.11%
• $ONDS 42.85%
• $CRK 39.78%
• $SOUN 39.63%
• $RH 38.41%
• $BTDR 38.15%
• $FLNC 37.97%
• $UWMC 36.57%
• $CAR 35.37%
• $SAIL 34.83%
• $IEP 34.22%
• $UPST 34.15%
My take: crowded shorts cut both ways — good news can squeeze these fast, but the crowd is usually short for a reason.

$NBIS – Technical Scenarios + Long-Term Fundamentals
I'm watching two possible scenarios for NBIS on the weekly chart. Both point toward potential upside longer term, but the path could be very different.
🟣 Scenario 1 (Pink Line): 140–145
NBIS could pull back toward 140–145 before bouncing toward 200–220. We might see some consolidation along the way before eventually moving toward 300.
🟡 Scenario 2 (Yellow Line): 95–100
If 140–145 fails to hold, I believe NBIS could see a deeper correction toward 95–100 before recovering toward 180–200 and potentially 280–300 over time.
Now Look at the Fundamentals:
- Q2 2026 Revenue: $582M, up 454% YoY.
- AI Cloud ARR (Annual Recurring Revenue Run Rate): $3B as of Q2.
- 2026 ARR Guidance: $7–9B.
- Contracted Power Target: 5 GW by year-end 2026, supporting future expansion through 2028–2030.
Why I'm Bullish Long Term:
With AI infrastructure demand continuing to grow, NBIS has the potential to scale significantly over the next several years. If the company executes on its capacity expansion and converts its growing ARR into actual revenue and cash flow, its business could look substantially different by 2028 and beyond.
My View: I'm bullish on NBIS long term, but that doesn't mean the stock can't experience a major correction first.
These are possible technical scenarios, not guaranteed outcomes. I'll be watching 140–145 closely, with 95–100 as the next major downside zone if support breaks.
Patience is key. The next 2–3 years could be very interesting for NBIS.

$SPY – Two Scenarios I'm Watching on the Weekly Chart 👀
I expect SPY to eventually test one of these two key levels:
🟡 Scenario 1 (Yellow Line): 725–730
This is my first downside target. A pullback into this zone could provide support and set up another rally toward the highs.
🟣 Scenario 2 (Pink Line): 697–700
If 725 fails to hold, I believe SPY could head toward 697–700, potentially sometime next year, before making another meaningful move higher.
Both scenarios point to a potential pullback before the next leg up. The big question is how deep that pullback will be.
I'm not saying this happens tomorrow or next week, but these are the levels I'll be watching closely.
Things could get very interesting over the next few months. 🍿

Great wins with small losses and big winners. Most big winners sold at 100–150%, only runners left riding.
keep losses small, let winners run.
Free whop link : whop.com/therip/the-rip-free…
$0, no payment at checkout — claimants get the free channels (free trade ideas and community chat)


For many, the last few weeks in this market have been tough. Conditions were not easy, and a lot of traders struggled through it.
For us it was different. We navigated it with less risk and proper sizing. Right entries, small risk on every trade — that is the whole game. And we don't take 20 trades in a week — very few trades, only the right entries. That is what I have been doing.
The results show it. CRM +54%, while our losses stayed tiny at -1% and -6%. When the entry is right and the size is right, the losses never hurt you.
We have been doing the same thing for the last few weeks, and the results keep showing. CRM was the first closed trade of my $10K Challenge — many more to come, the same way.
