

Fractional CTO for Indian MSMEs & East African banks · Founder, DT Alpha · SME/nano-cap investor sharing my trades & IPO notes. Not advice. DMs open.
Kenya
Joined July 2009
- Tweets9.2K
- Following64
- Followers2.1K
- Likes19.7K





Pinned Tweet
SME promoters & founders: what tech problem is holding your business back?
1 ERP/Tally can't keep up
2 App that never shipped
3 IPO-ready systems & controls
4 Need a CTO, not a CTO salary
Reply with a number. I'll answer the top asks free, in public.
dtalpha.co/india?utm_source=…

Happy Diwali 🎇🎉 to all my friends and followers . May this year bring you all immense wealth and happiness 🙏

Venkatram retweeted

🫱 BEEZAASAN EXPLOTECH FY27 H1 RESULTS. H1FY27 RESULTS. Rs. 775 was at 87.6p/e. Now SAME 🫱
Valuation is purely on expectation of capex completion which is delayed. Out of around 30Cr only 12Cr is spent. And there can be further delay since approvals are not fast for explosive segment. Take good care of some part profit!
H1 FY27 Vs.H2 FY26
REV:Rs. 128Cr Rs. Vs Rs. 112Cr 👍
PAT:Rs. 8.4Cr Vs Rs. 5Cr 👍
(May Compare with H1FY26 Rev=Rs. 101Cr & PAT=Rs. 8.4Cr ) OKAY 🫱
TTM Vs FY26
REV:Rs.240Cr Vs Rs. 213Cr 👍
PAT: Rs. 13.4Cr Vs Rs. 13.4Cr🫱
SME IPO was in March 2025 at Rs.175

📌 Beezaasan Explotech Ltd informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #BEEZAASAN 📄🧾


Venkatram retweeted

Someone rightly said: "𝘐𝘯𝘥𝘪𝘢 𝘪𝘴 𝘧𝘶𝘭𝘭 𝘰𝘧 𝘣𝘶𝘴𝘪𝘯𝘦𝘴𝘴𝘦𝘴 𝘯𝘰𝘣𝘰𝘥𝘺 𝘩𝘢𝘴 𝘩𝘦𝘢𝘳𝘥 𝘰𝘧 𝘶𝘯𝘵𝘪𝘭 𝘵𝘩𝘦 𝘐𝘗𝘖."
This is one of them.
𝗠𝗮𝘅𝘄𝗲𝗹𝗹 𝗘𝗻𝗴𝗶𝗻𝗲𝗲𝗿𝗶𝗻𝗴 𝗦𝗼𝗹𝘂𝘁𝗶𝗼𝗻𝘀: a global manufacturer of aftermarket components for underwater pelletizing and extrusion systems.
In plain words: almost every plastic pellet in the world is cut against a die plate by knives spinning under water. Maxwell makes those 𝗱𝗶𝗲 𝗽𝗹𝗮𝘁𝗲𝘀, 𝗸𝗻𝗶𝘃𝗲𝘀 𝗮𝗻𝗱 𝗰𝘂𝘁𝘁𝗲𝗿 𝗵𝘂𝗯𝘀 in Vadodara, and ships ~𝟴𝟰% of them abroad. Germany and the Netherlands are its biggest markets.
FY26 revenue ₹𝟮𝟵.𝟱 𝗰𝗿, PAT ₹𝟭𝟭.𝟵 𝗰𝗿
EBITDA margin 𝟱𝟮% in FY26, 𝟯𝟲% in 4MFY27
The company operates in a 𝗻𝗶𝗰𝗵𝗲 𝗺𝗮𝗿𝗸𝗲𝘁 and is a 𝘃𝗲𝗿𝘆 𝘂𝗻𝗶𝗾𝘂𝗲 𝗽𝗹𝗮𝘆𝗲𝗿 for the listed markets.
𝗪𝗵𝗮𝘁 𝗜'𝗺 𝘄𝗮𝘁𝗰𝗵𝗶𝗻𝗴: whether margins recover after the dip, and whether it can make die plates of up to 𝟭.𝟲 𝗺, against 0.5 m today.
Found it interesting and tried to decode the business, report in the link:
drive.google.com/file/d/1reR…
𝘋𝘪𝘴𝘤𝘭𝘢𝘪𝘮𝘦𝘳: 𝘈𝘭𝘭 𝘴𝘩𝘢𝘳𝘦𝘥 𝘤𝘰𝘯𝘵𝘦𝘯𝘵 𝘪𝘴 𝘱𝘶𝘳𝘦𝘭𝘺 𝘧𝘰𝘳 𝘪𝘯𝘧𝘰𝘳𝘮𝘢𝘵𝘪𝘰𝘯𝘢𝘭 𝘱𝘶𝘳𝘱𝘰𝘴𝘦. 𝘐𝘯𝘷𝘦𝘴𝘵𝘮𝘦𝘯𝘵 𝘪𝘯 𝘚𝘔𝘌𝘴 𝘤𝘢𝘳𝘳𝘺 𝘳𝘪𝘴𝘬 𝘰𝘧 𝘤𝘢𝘱𝘪𝘵𝘢𝘭 𝘭𝘰𝘴𝘴. 𝘐'𝘮 𝘯𝘰𝘵 𝘚𝘌𝘉𝘐 𝘳𝘦𝘨𝘪𝘴𝘵𝘦𝘳𝘦𝘥, 𝘋𝘠𝘋𝘋.


Venkatram retweeted

🪔 Stock Market Trading Holiday & Muhurat Trading
📅 Sun, 8 Nov: Muhurat Trading
⏰ 2:20 PM – 3:30 PM
✅ Mon, 9 Nov: Market open
❌ Tue, 10 Nov: Market closed
SME BULK DEALS on 06/11/2026
🇳 • AGARWALTUF • Agarwal Toughened Glass India Limited
🟥 • A M LODHA & SONS (HUF) • SELL • 168,000 SHARES • ₹169.03
🟩 • VAIBHAV RAJENDRA DOSHI • BUY • 177,600 SHARES • ₹169.63
🟥 • VAIBHAV RAJENDRA DOSHI • SELL • 174,000 SHARES • ₹169.78
🇧 • 544800 • ANUBHAV • Anubhav Plast Ltd
🟥 • LONGTHRIVE CAPITAL VCC - TRENDVIEW CAPITAL FUND ⚓ [👥 Sep 2026 - 225,600] • SELL • 84,800 SHARES • ₹43.98
🟩 • SANJAY AGARWAL • BUY • 56,000 SHARES • ₹44.00
🇳 • APSISAERO • Apsis Aerocom Limited
🟥 • KASHMIRA AJAY PATEL [👥 Sep 2026 - 171,600] • SELL • 160,000 SHARES • ₹468.18
🟩 • SOLIDARITY MICRO CAP EMERGING LEADER AIF • BUY • 94,600 SHARES • ₹468.00
🇳 • EXIMROUTES • Exim Routes Limited
🟥 • EXPERTPRO REALTY PRIVATE LIMITED [👥 Sep 2026 - 268,800] • SELL • 221,600 SHARES • ₹71.66
🇳 • GREENASIA • Green Asia Impex Limited
🟩 • AIKYATA ADVISORY LLP • BUY • 137,600 SHARES • ₹72.00
🟥 • M7 GLOBAL FUND PCC - AERION [👥 Oct 2026 - 523,200] • SELL • 139,200 SHARES • ₹72.00
🇳 • HGSINDIALT • HGS (India) Limited
🟩 • ROHAN GUPTA • BUY • 234,000 SHARES • ₹163.36
🟩 • VIJIT GROWTH FUND ⚓ • BUY • 122,400 SHARES • ₹163.29
🇧 • 545021 • JOHNSONCAB • Johnsoncab Electricals Ltd
🟥 • LRSD CAPITAL PRIVATE LIMITED • SELL • 93,000 SHARES • ₹238.50
🟥 • RAJASTHAN GLOBAL SECURITIES PRIVATE LIMITED • SELL • 93,000 SHARES • ₹238.50
🟥 • RGSL INVESTMENT LVF 1 • SELL • 92,400 SHARES • ₹238.50
🟥 • SMC INDIA OPPORTUNITIES FUND • SELL • 54,000 SHARES • ₹238.66
🟩 • SUNRISE INVESTMENT OPPORTUNITIES FUND • BUY • 272,400 SHARES • ₹238.50
🇧 • 544641 • KVTOYS • K. V. Toys India Ltd
🟩 • SHINCHO ASIA CAPITAL (INCORPORATED VCC SUB-FUND) • BUY • 47,400 SHARES • ₹213.37
🇧 • 544925 • SPEEDEX • Maharaja & Speedex India Ltd
🟥 • YUGA STOCKS AND COMMODITIES PRIVATE LIMITED [👥 Sep 2026 - 305,400] • SELL • 82,800 SHARES • ₹245.94
🇳 • MARUSHIKA • Marushika Technology Limited
🟥 • MANSI SHARE AND STOCK BROKING PRIVATE LIMITED [👥 Sep 2026 - 120,000] • SELL • 99,600 SHARES • ₹120.13
🇧 • 544373 • NAPSGLOBAL • NAPS Global India Ltd
🟩 • RADHESHYAM MAKHARIA [👥 Mar 2025 - 48,000] • BUY • 22,400 SHARES • ₹89.78
🇳 • RAPPID • Rappid Valves (India) Limited
🟥 • ASHOK KUMAR DHARIWAL • SELL • 34,200 SHARES • ₹385.00
🟩 • MARWADI CHANDARANA INTERMEDIARIES BROKERS PRIVATE LIMITED • BUY • 50,400 SHARES • ₹384.84
🇧 • 545020 • VECTRAS • Vectras Enprocon Ltd
🟩 • CARE WEALTH ADVISORS LLP • BUY • 192,000 SHARES • ₹106.00
🟩 • PARESH S SHAH (HUF) • BUY • 188,400 SHARES • ₹106.01
🟩 • RAJGOR RAHULKUMAR MOHANLAL • BUY • 102,000 SHARES • ₹106.00
🟩 • SHREE GAUTAM ENTERPRISE PRIVATE LIMITED • BUY • 174,000 SHARES • ₹106.00
🟩 • SUNRISE GILTS AND SECURITIES PVT LTD • BUY • 172,800 SHARES • ₹106.85
🟩 • SUNRISE INVESTMENT OPPORTUNITIES FUND • BUY • 262,800 SHARES • ₹106.00
🟥 • VBCUBE VENTURES FUND II • SELL • 133,200 SHARES • ₹106.00
🇧 • 545010 • WISCON • Wiscon Industries Ltd
🟩 • MINERVA VENTURES FUND • BUY • 784,200 SHARES • ₹204.00
🟥 • NIRAJ RAJNIKANT SHAH [👥 Nov 2026 - 199,800] • SELL • 224,400 SHARES • ₹204.00
🟥 • YASH HITESH PATEL [👥 Nov 2026 - 280,500] • SELL • 169,200 SHARES • ₹204.00
👨💼= Promoter ⚓= Anchor ⚖️= MM 👥= SHP Entry
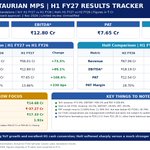
#Beezaasan strong results 💪H1 FY27: Revenue ₹127.0 Cr (+26% YoY), EBITDA ₹14.67 Cr (+10%), PAT ₹8.36 Cr (+1%). PAT margin fell to 6.59%.Margin to be watched. HoH improved sharply vs H2 FY26, while CFO stayed positive at ₹3.46 Cr but cash conversion remained moderate.

📌 Beezaasan Explotech Ltd informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #BEEZAASAN 📄🧾
#Anawil Poor results 🔻H1 FY27: Rev ₹154.0 Cr (+272% YoY), EBITDA ₹36.3 Cr (+246%), PAT ₹14.39 Cr (+539%). PAT margin rose to 9.34%. HoH revenue +51%, but PAT -57% vs a very strong H2 FY26 base. CFO ₹28.28 Cr; strong YoY growth with healthy cash generation. Disc- Exited due to poor execution
🤖 Made with AI

am going to gift 1 idea for Diwali this year, No levels or suggestion. Look into #SJlogisitics and given we recently had the results from its peer #Sadbhav and look into the PE - Once results come this will change
#HGSIndia nice listing not too high or too low Tailwind sector who will benefit from rare earth exploration and mine site determination phase though the use is insignificant once mining starts. Added, will keep track, no recommendation. DYOR


#Maxwell learned from past experience refined my model and saw value at 90% listing, entered will see how this goes. No recommendation DYOR.


Venkatram retweeted

Aditya Infotech : CPPLUS Guidance raised.💡
Look at the slide even keeping the same Ebitda margins PAT margjns raised as debt repayment will help in less interest payment .


Venkatram retweeted

#SME #Susan #SusanElectricals #SusanElectricalsIndiaLimited
Susan Electricals India H1 FY27 Concall Highlights:
👉H1 FY27 & Future Outlook :
▫️H1 FY27 revenue from operations ₹202.06 Cr vs ₹69.67 Cr in H1 FY26 (+190% YoY); first half-year results since listing
💠Operating profit ₹23.78 Cr (+160% YoY); EBITDA margin 11.77% vs 13.13% in H1 FY26
💠PAT ₹13.15 Cr vs ₹4.53 Cr (+191% YoY)
💠Cash flow from operations turned positive
▫️Margin trend: H1 FY26 included one-time gains from abnormal aluminium and copper price movements
💠Q2 FY26 EBITDA margin was 18.18% on those gains; underlying margins have stayed at ~11.5-12%
💠FY26 EBITDA margin 11.91%
💠Mix shift toward winding wire and HT cables is expected to lift EBITDA margin ~2-3% above current levels by the end of FY28
▫️Margin and growth targets
💠PAT margin ~6-7% now; target 8-9% in FY28
💠Top line to grow ~40-50% in each of FY28 and FY29
💠Team is being given EBITDA-margin targets rather than sales targets
▫️H2 FY27 expected to be significantly stronger, backed by better execution capability, capacity additions and order pipeline
💠H2 priorities: commission the CCV line, scale up HT, MVCC and winding wires, complete capacity expansion on schedule, and convert receivables into cash
▫️Revenue mix shift (Q2 FY27): HT & MVCC ~30%, winding wires ~33%, LT cables ~31%
💠H1 FY27 mix: LT cables & conductors 47.83%, winding wire 29.10%, HT cables & MVCC 19.36%, others 3.71%
💠H1 FY26 mix: LT 46.76%, winding wire 40.37%, HT & MVCC 0.75%, others 12.12%
💠HT & MVCC sales rose from ₹0.52 Cr in H1 FY26 to ~₹39 Cr in H1 FY27; FY26 share was 8.57%
💠FY27 mix target: HT & MVCC ~40-50%, winding wires ~40%, LT cables 10-20%
💠FY28 mix target: LT cables 5-10%, winding wires and HT & MVCC ~45% each
▫️Winding wire sales +109% YoY in H1 FY27; margins are better than LT cables
▫️Volumes: Q2 FY27 vs Q1 FY27
💠HT cables & MVCC 518 km vs 176 km
💠LT cables & conductors 1,498 km vs 3,641 km
💠Winding wires 937 tons vs 554 tons
▫️Trading is only ~1-2% of revenue; no plan to repeat last year's aluminium trading
👉Order book / projects and pipeline:
▫️Order visibility ₹347 Cr as of 30 Sep 2026
💠Unexecuted order book ₹147 Cr; a significant portion is expected to be executed within the next 3 months
💠Active order pipeline ₹200 Cr
▫️Order book split (₹147 Cr):
💠HT cables & MVCC ₹54 Cr (more than a third)
💠Winding wires ₹69 Cr (almost half)
💠LT cables ₹24 Cr
💠HT cables and winding wires together are more than 80% of the order book
▫️Q2 FY27 order flow: ~₹107 Cr executed and ~₹111 Cr of new orders won, so the order book still grew
▫️CCV (continuous catenary vulcanisation) line:
💠Installed; to become operational within ~10 days
💠CCV technology is mandatory for most HT cable projects, widening the range of projects Susan can bid for
💠Helps meet technical requirements for supplying HT cables to state utilities and government departments
💠HT cables currently go up to 33 kV; plan to go above 33 kV soon, with BIS approval taking ~2-3 months once applied
▫️Cable capacity expansion:
💠Raised from 7,500 km to 11,000 km; further expansion to 16,000 km per annum planned (+5,000 km)
💠Commercial production targeted for Mar 2027
💠Existing plant can expand up to 16,000-20,000 km; existing land has room up to 22,000 km per annum
▫️Winding wire capacity expansion:
💠Raised from 3,307 to 4,200 tonnes; further expansion to 5,500 tonnes planned (+1,300 tonnes), an overall increase of ~66%
▫️New land:
💠Possession expected by next month; approximate value ₹22 Cr
💠Funded through internal accruals plus bank loan
💠FDs of ~₹48 Cr currently given as collateral for CC limits to be released once the land is offered as collateral
💠Expansion at the existing plant to cover needs up to FY28 (31 Mar 2028)
💠Construction on new land to start between FY28 and FY29, with a production start thereafter
💠Existing factories at Site IV Industrial Area to shift to the new land; land cost there is ~₹1 lakh per sq yard vs ~₹10,000 at the new site
▫️Roadmap: expand HT, MVCC, LT cable and house wiring capacity and geographic sales, ramp up aluminium conductors, explore railway and defence electrification
💠Operational in Uttar Pradesh, Telangana, Rajasthan, Madhya Pradesh, Jharkhand, Bihar, Haryana, Punjab and Gujarat
💠Expanding to Kerala, Tamil Nadu, Uttarakhand, Karnataka, Maharashtra, Andhra Pradesh, Chhattisgarh and rest of India
👉Q&A :
▫️Product portfolio:
💠No new products planned (capacitors, insulators etc.) for the foreseeable future
💠Current range of winding wires, HT cables, LT cables, conductors and MVCC is not matched by any other cable company; 12 BIS licences held
▫️Raw material price risk:
💠Orders come with price-variation clauses; ~90% of EPC contractor orders carry PV
💠Only firm-rate orders are those supplied within a month
▫️Customer mix and collections:
💠Earlier ~90-95% government; now ~50% EPC
💠EPC customers pay faster, mostly via LC or advances, in ~20-30 days
💠Government MSME payments come within ~2 months
💠More preference being given to EPC customers this year
▫️Freight: included in pricing; share of cost is small as products are volume-heavy
▫️Finance cost:
💠Not expected to rise: major capex is funded by IPO proceeds, borrowings already incurred and operating cash flow
💠Term loans are repaid regularly through EMIs; no large repayment due and no bank limit increase needed
💠Finance cost may even come down
👉 Others :
▫️Receivables:
💠~₹95 Cr, of which ₹25 Cr was billed in the last week of September
💠₹44 Cr collected in October
💠Only ~5% (~₹4 Cr) is older than 180 days, of which ~₹3.5 Cr has been received
▫️Debt (30 Sep 2026): total borrowings ₹122 Cr (short-term ₹115 Cr, long-term ₹7 Cr)
💠Cash and equivalents ₹61 Cr; net debt ~₹60 Cr, similar to March 2026
▫️Unit-wise capacity and utilisation:
💠Unit I (winding wires & strips): 4,200 tonnes, 75%
💠Unit II (LT cables): 6,000 km, 80%
💠Unit III (LT & HT cables): 5,000 km, 80%
▫️FY26: revenue ₹269.36 Cr, EBITDA ₹32.08 Cr, PAT ₹18.25 Cr (margin 6.77%)
💠RoE 64.64%, RoCE 29.05%
▫️Certifications: ISO 9001, 14001 and 45001; type-test approvals from CPRI, ERDA and National Test House
💠Positioned among India's top 20 wire and cable players; the industry has 500+ small players


Venkatram retweeted

Marine Electricals #Marine
Blockbuster Results By Marine.💥
Was Expecting 360 Crore Revenue But It Exceeded Now Waiting For The Order Book I Think They Crossed 5000 Crore Order Book.


