




PJ retweeted

VIRTUAL VS PHYSICAL CRYPTO CARDS
How much does it cost to get each one?
1. @wirex_one - Virtual: Free | Physical: Premium+ (delivery varies)
2. @KASTxyz - Virtual: Free | Physical: Free + $40 delivery
3. @EthenaPay - Virtual: Free | Physical: Not listed
4. @avici - Virtual: Free first Platinum / $10 next; Signature: $30/year | Physical: $50 Platinum / $75 Signature
5. @PulsarMoneyApp - Virtual: Free | Physical: Not listed
6. @Krak - Virtual: Free | Physical: Free
7. @RedotPay - Virtual: $10 | Physical: $100
8. @ether_fi - Core: Virtual: 1 free (or $10, depends on the region) | Physical: $50. Higher tiers include free cards within set limits.
9. @trustee_io - Virtual: $10 | Physical: €25
10. @oobit - Virtual: Free issuance | Physical: Free issuance
11. @Bybit_Official - Virtual: Free | Physical: $0-$29.99 depending on region
12. @KoloHub - Virtual: Free
13. @xplaceapp - Virtual: Membership-based | Physical: Price not disclosed
14. @solcard - Virtual: $10
15. @JupiterExchange - Virtual: Free / $25 for Claynosaurz edition | Physical: $13.13 + delivery
16. @Plasma - Virtual: Free | Physical: Free on Platinum
18. @SolidYield - Virtual: Free | Physical: Not listed
19. @falconfinance - Virtual: Free | Physical: Not listed
Which one offers the best deal?


How much does a physical Crypto Card cost?
Card fee and delivery, checked in the apps and docs:
- @TheAvaxCard : free card, free delivery
- @useTria : free card and delivery on Pro and Max
- @Krak : delivery from $5
- @wirexapp : free card, delivery from €5 in Europe
- @Plasma : free card, $20 delivery, free on Platinum
- @jup_mobile : $13.13 card, delivery from $7.50 to $75
- @coca_card : $1 card, $26 DHL delivery
- @KASTxyz : free card, $40 delivery
- @ether_fi : $50 card on Core, free delivery
- @avici : $50 Platinum, $75 Signature, delivery free or $50
- @Solayer_Pay : $59.99 with delivery
- @RedotPay : $100 card
What did you pay for yours?

PJ retweeted

Almost 2 decades of #IPL, more than 10 teams (including the exits), two 5 time champion teams and yet NO TEAM was EVER remembered for playing a specific BRAND OF CRICKET. And then, #PatCummins arrived at #SRH, a team nobody took seriously even after winning one title, and he made a specific brand of cricket the 'core identity' of #SRH, that too in his very first season. Him at the helm of #SRH did not just redefine the way cricket is played in the IPL, #SRH redefined how T20 cricket is played across the world. Whether he's leading #SRH or not, whether he's a part of #SRH or not, I will forever be indebted our skipper as an #SRH fan. Warner won us the title, but Cummins got us the identity that we did not have even after winning a title. 🙏🏻🔥🧡🦅
PJ retweeted

4 Schengen🇪🇺 countries that I think are great options for Indian travellers applying for their first-ever Schengen visa.
This is based on each country's overall travel experience, how straightforward its visa documentation requirements are, its refusal rates, and how long visa processing typically takes.
1. France 🇫🇷
France is probably my personal favourite. Paris, with the Eiffel Tower and its overall charm, makes for a fantastic first European experience.
You can also explore places like Nice (South) and Normandy (North), although most first-time Indian travellers usually don't venture to these places on their first trip.
From a visa perspective, France is relatively straightforward when it comes to documentation.
The refusal rate is around 13-15%, and France receives over 2 lakh applications from Indian travellers. In my view, some refusals are also because people assume France is lenient and end up submitting poorly prepared applications.
Processing is usually quite fast too, with most visa applications getting processed within 4-5 days, barring exceptional periods such as the Paris Olympics.
2. Switzerland 🇨🇭
Switzerland is another obvious favourite among Indian travellers. In fact, it has now overtaken France to receive the highest number of Schengen visa applications from India.
Together, France and Switzerland account for around 40% of all Schengen visa applications from India.
And there's a reason for this popularity. Switzerland offers some of the most beautiful landscapes in Europe. Interlaken, Lucerne, Zurich, Lauterbrunnen, etc., are all fantastic places to explore.
Of course, for many Indians, Switzerland also has a special connection with Bollywood. DDLJ made these landscapes incredibly popular, and many travellers still want to visit the locations they've seen in the movie.
From a documentation standpoint, Switzerland requires the least. Its checklist doesn't specifically require a cover letter or a detailed day-wise itinerary, although you can certainly submit one.
The refusal rate is broadly comparable to France. However, processing has slowed down considerably. Since September, many applications have been taking 15-20 days or even longer, making it noticeably slower than France. In any case, processing hasn't been as fast as France.
3. Germany 🇩🇪
Germany is worth considering, particularly if you're looking at visa refusal rates.
It has a refusal rate of around 10%, which is the lowest among the four countries covered here.
Processing timelines can vary, but applications have often been processed within a week in recent months, particularly since July.
Make sure your application is thorough, and all the supporting documents are in order. Germans are very process oriented.
In terms of travel, Berlin and Munich are popular destinations. But if I were comparing the overall tourism experience, I'd personally rank Germany much below Switzerland and France.
4. Spain 🇪🇸
Spain is another excellent option for a first European trip.
You have plenty of choices, from Barcelona and Madrid to Malaga, Seville and Ibiza. There's a good mix of architecture, beaches, food, nightlife, and culture.
The refusal rate is broadly comparable to France, while processing is much faster if you apply via Mumbai Embassy (4-5 days)
Spain is particularly popular among younger travellers and groups of friends. I see a lot more bachelors choosing Spain for their Europe trips, compared to families, although it's equally worth considering for a family holiday.
It's also a good destination if you're planning a longer European holiday of around 15-20 days, given the number of places you can cover.
Do feel free to DM me if you have visa or itinerary-related queries.
A final point
Don't pick a country purely because you think its visa process is easier or its refusal rate is lower.
You must apply through the country where you genuinely intend to spend the maximum number of nights. If you're visiting multiple countries and spending an equal number of nights in each, you should apply through your main destination.
PJ retweeted

IF YOU DON'T HAVE THESE 10 APPS ON YOUR PHONE, YOU'RE STILL A NOVICE!
1 • Blackhole
To download videos from Instagram, TikTok and other supported platforms without watermarks. Just copy the video link, paste it into the app and save.
2 • LocalSend
To transfer photos, videos and files between Android, iPhone and computers over the same Wi-Fi network.
3 • Universal Copy
Have you ever tried copying text from an app but discovered that the app doesn't allow you to select or copy it?
Universal Copy solves that problem. It lets you select and copy text from apps that ordinarily don't support copying. It can also extract text from images.
4 • Bluetooth Microphone Live
To turn your phone into a wireless microphone and amplify your voice through a compatible Bluetooth speaker. Useful when making announcements at small gatherings.
5 • KDE Connect
To connect your phone to your computer wirelessly. You can share files, copy text on your phone and paste it on your computer, receive phone notifications on your PC and even use your phone as a wireless mouse.
6 • The Hora World Clock
To add multiple cities and instantly see their current times. Perfect if you work remotely with people across different time zones or have friends and family abroad.
7 • Google Lens
To identify objects, translate text, scan documents, copy text from pictures and search for products simply by pointing your camera at them or uploading an image.
8 • MacroDroid
To automate repetitive tasks on your phone without knowing how to code. For instance, you can make your phone automatically turn on Wi-Fi when you get home, activate silent mode at bedtime or perform certain actions when you connect your Bluetooth earphones.
9 • Bitwarden
To securely store your passwords. Instead of struggling to remember dozens of passwords or using the same password everywhere, you can save them in an encrypted vault and retrieve them when needed.
10 • AccuBattery
To monitor your phone's battery usage, estimate its battery health and track how much battery wear occurs during charging. It also has a charging alarm to remind you when to unplug your phone.
You don't need to install all 10 immediately, but I guarantee some of these will change how you use your phone.
Which of these apps are you just discovering?
Stay informed
And
Stay sharp! 🪒

PJ retweeted

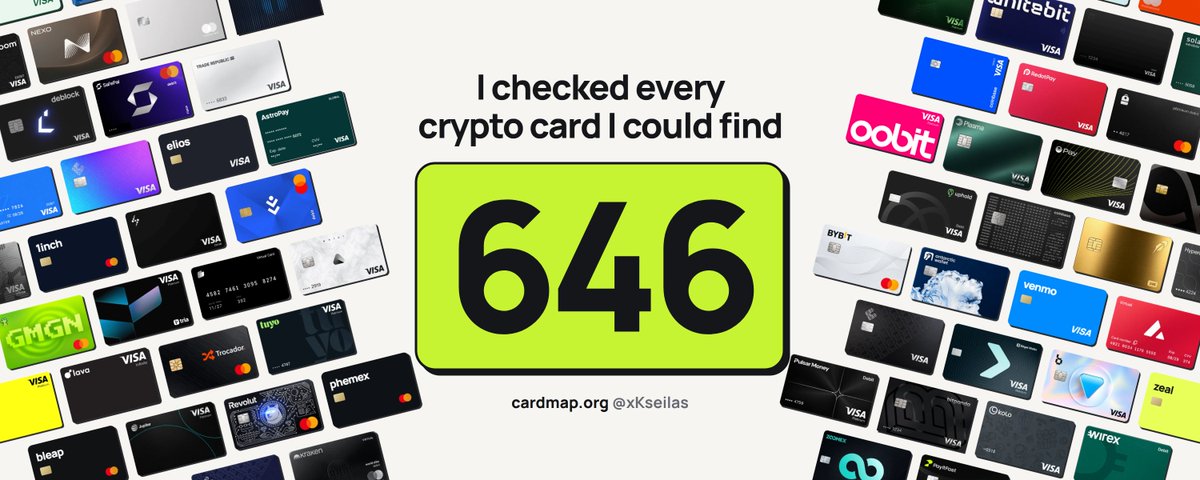
I checked 646 crypto cards.
Only 256 are live cards you can actually get. I scored 109 on cost, cashback, safety, access and daily use. 4 made my S tier.
Best to worst, plus 6 I'd avoid right now:
PJ retweeted

I have dedicated a post regarding crypto taxation and it was much loved by community.
So now I will break it down to you, how to request payout in your bank account. (USD/INR method)
Most firm mostly give payout through rise and very few through direct bank transfer.
I will cover direct bank transfer some other day, today it will be from rise.
As soon as you recieve payout on rise there's 2 option available to withdraw.
1. Directly in USD: Rise send USD from their bank account directly in your bank.
2. Directly in INR (Rise converts Usd-> Inr and send amount through NEFT/bank transfer)
Detailed breakdown:
1. Directly in USD:
For that you need
-Bank account number
-IFSC code
-Swift/Bic code
You can use swift code universal for your bank eg: HDFCINBBXXX is for HDFC for any part of the india, if its ending in XXX it means, it's universal and can be used in any remote region.
It takes 24-48 hours to reach your bank and from there it takes 24-48 to credit.
Purpose code if you are propfirm service provider: P1006
After receiving payout, you can request FIRC certificate from bank, because bank has converted your USD->INR not rise, HDFC provided me FIRC without even asking and for free after 24 hours my payment was credited.
2. Directly in INR
You just need two things:
-Bank account number
-IFSC code
It's a local bank transfer from rise and you receive it under 1 minute.
As RISE converted your USD to INR, now Rise will provide FIRC certificate, not your bank.
As soon as payment is completed, you can open rise support and request your FIRC certificate from them.
Only issue is, it takes them week to deliver (heard someone take month over) it to you and FIRC is one important thing that proves that you recieved legitimate fund.
I took in INR because it was urgent and opened support ticket to request FIRC from them.
So my take, I don't take unnecessary risk and always approach to be strong on paper.
So I will use USD transfer as from bank we receive FIRC in least time as compared to rise.
Now I will try @skydo_official platform.
Here we get USA virtual account in your name.
You add this account in your rise withdrawal and from their request USD.
Skydo will process that USD->INR conversion on live market rate rather than less rate which both bank and rise does.
So it removes those time gaps and 99% of the time it is processed within 24hours.
And provide FIRC within 14 days, so I am chasing fast process along with better rates than skydo is the platform.
(I am neither partnered nor took money lool 🤣, if they have any issues i will adress them too, their onboarding took less than 5 minute for me)
I will share my experience soon, I already have a payout probably upcoming week, will try them with small amount first and share how it was handled.
Let me know in comments if you have any doubts and DMs are open now 💪.
PJ retweeted

What happened in crypto cards this week? #6
KAST ends points for Pioneer Units, OKX opens a US card, Bitget lands in Nigeria, and November cashback heats up.
Here are 9 updates worth knowing—and the conditions behind them. 🧵
1/ @KASTxyz
KAST's CEO said there will be no token.
On 2 Nov, KAST said points earning ends on 30 Nov 2026. In the first week of December, eligible points convert into KAST Pioneer Units issued by a KAST-linked SPV.
The units can't be sold, transferred or traded and have no guaranteed cash value; miss the in-app acknowledgment and the balance is cancelled.
2/ @okx
On 2 Nov, OKX said its OKX Card is live in the US: a virtual Mastercard issued by WebBank. It excludes Massachusetts, New York and the US territories.
3/ @BitgetWallet
On 3 Nov, Bitget Wallet said its card is live in Africa. Bitget Wallet's press release names Nigeria: a virtual Visa with Google Pay.
The launch campaign runs 3–13 Nov, with a welcome bonus of $2 up to $20 for early tasks.
4/ @ether_fi
On 31 Oct, etherfi said members have borrowed $150M against crypto without selling it.
On 30 Oct, it added ZCHF support: spend with the card for cashback, borrow USDC against it, or buy stocks, aimed at Swiss members, with Frankencoin and Mt Pelerin.
Until 31 Dec, Luxe, Pinnacle and VIP get bank deposit fees refunded (ACH, wire, SEPA, PIX, Faster Payments and more), up to $150,000 a month on VIP.
5/ @coca_card
From 2–30 Nov, new COCA sign-ups get 8% back on their first 3 card purchases, with nothing to stake or pay. Rewards are paid in USD or EUR.
6/ @cashi
On 5 Nov, Cashi added 2% a year asset rewards on balances up to $100,000, with no lockups, paid every Monday.
7/ @PulsarMoneyApp
On 3 Nov, Pulsar launched Beyond Friday: double cashback in Points for Pro users at rotating brands all November (week one Amazon, eBay, SHEIN, Temu; later weeks cover fashion, gaming and grocery apps). Pulsar says Pro can reach up to 8% at those brands.
8/ @Plasma
On 3 Nov, Plasma One offered 11% cashback for 11.11, up to $30, on direct eligible merchant spend only. Terms apply.
9/ @kardpay
On 30 Oct, Kardpay said physical cards are finally available for everyone, with worldwide shipping starting the following week. Fees, rewards and eligibility weren't in the announcement.
Which update changes your card shortlist most?


PJ retweeted

->Democrats win & 🇺🇸 stock market crash.
->Democrats won't be able to stop frontier AI models.
->Impact on Crypto?
->What will happen now: rate cut or Rate Hike?
->What will happen to the bond market?
->Many more...
PJ retweeted

Crypto Cards Are Getting Bigger. Here's What October 2026 Looked Like.
Crypto cards are no longer just a niche way to spend stablecoins.
Some projects are already moving hundreds of millions of dollars every month.
I looked at 24 crypto cards and neobanks to see how much volume they reported in October.
The biggest players ($50M+)
@RedotPay - $423.5M
@ether_fi - $141.9M
@KASTxyz - $121M
@wirex_one - $54.8M
@Karta_Personal - $53.6M
The next wave ($5M–$50M)
@Plasma - $30.2M
@KoloHub - $20.5M
@useTria - $15.8M
@xplaceapp - $9.97M
@jup_mobile - $8.57M
@coca_card - $7.82M
@gnosispay - $6.08M
Smaller players worth watching
@Gate - $3.79M
@avici - $3.68M
@MetaMask - $3.38M
@EthenaPay - $3.1M
@avax - $2.8M
@itstuyo - $2.1M
@BitgetWallet - $1.8M
@Exa_App - $1.71M
@Solayer_Pay - $1.29M
@bfinancepay - $1.14M
@SolidYield - $689.7K
What caught my attention?
RedotPay is still miles ahead, but ether.fi and KAST are already showing serious scale.
Meanwhile, projects like Kolo, Tria and COCA are building their own share of the market.
And this is what makes the crypto card space interesting to me.
It's not just about who offers the highest cashback anymore.
It's about who can turn crypto into something people actually use every day.
Which crypto card do you think will grow the most in 2027?

PJ retweeted

I bought a Mumbai Local Train Ticket with CRYPTO (USDC)
- Open Mumbai one app and select your ticket.
- Scan UPI QR with @goatdotcash
- Enter INR, and scan QR.
- USDC Deducted, paid in UPI.
Try it out now!
🤝 Paid partnership
PJ retweeted

How to move your US stocks from Vested/INDMoney (and similar apps) to a real broker? (without selling and buying your holdings again)
If you are worried about your holdings after the recent Stockal fiasco. Here’s the clean, step-by-step way to transfer your holdings out of apps like Vested/INDMoney and into a proper US broker.
1️⃣ Step 1: Open an account with a real US broker
Create a new brokerage account with a full-service broker that actually provides direct US market access - Interactive Brokers (IBKR), Charles Schwab, etc. Not another “fintech wrapper” like Vested/INDMoney that isn’t the broker of record.
Good news: these brokers usually support fully online, remote onboarding.
2️⃣ Step 2: Find your current broker + account number
Your US stocks aren’t held “inside” Vested/INDMoney - they’re held at the underlying custodian/broker (often Apex Clearing, DriveWealth, etc.).
Check your statements for your Account Number / Account ID. If you can’t find it, ask support specifically for:
- Your clearing broker/custodian name
- Your exact account number there
Once you have that, move to Step 3.
3️⃣ Step 3: Initiate an ACATS transfer (full account transfer)
After your new account is active (IBKR/Schwab), submit an account transfer request via ACATS (Automated Customer Account Transfer Service).
It’s typically a simple form where you enter:
- Current broker/custodian (e.g., Apex/DriveWealth)
- Your account number
- Your personal details (name, address, passport, etc.)
ℹ️ Critical: your details must match your existing account exactly, or the transfer can get rejected.
Also:
- Some brokers charge an outbound transfer fee, ensure you have enough cash to cover it.
- Choose “Transfer ALL holdings & cash” unless you intentionally want a partial transfer.
4️⃣ Step 4: Wait for settlement + cost basis
Most transfers take ~4–7 business days for positions to appear. Cost basis often updates a few days after that.
If it stalls or fails, it’s usually due to mismatched details or an incorrect account number.


PJ retweeted

Discovered something very useful ! 🔖
You can track ALL your UPI AutoPay subscriptions in ONE place. You can view, pause or cancel them through a single portal.
How to check:
- Login using your mobile number.
- Open the Subscriptions section.
- View all your active mandates.
- Pause or Cancel unwanted subscriptions.
🔗 Official NPCI Portal: upihelp.npci.org.in/
Worth checking once. You might be paying for subscriptions you no longer use! 🔥

PJ retweeted
India just found the crypto card Indians aren't allowed to have.
@RedotPay doesn't block India from its app. Users can register, pass KYC and hold a balance.
But there's a catch.
RedotPay's Card Issuance Restrictions, updated August 28, explicitly say Indian residents are NOT eligible for virtual or physical cards.
India is also banned as a billing address.
Yet people were using these cards to:
> Book flights
> Recharge phones
> Pay Indian merchants with stablecoins
In August, a Bengaluru research group reportedly obtained a RedotPay card, tested payments inside India and submitted its findings to the authorities.
Now things are getting interesting.
Indian users have recently reported failed card payments, while India's central bank and financial intelligence unit are reportedly examining offshore crypto cards.
And what happens to the money already sitting on these accounts?
RedotPay's terms allow it to:
> Request additional ID before returning funds
> Choose the refund method and currency
> Charge withdrawal or maintenance fees
> Forfeit unclaimed funds after 3 years under specified conditions
> Suspend accounts without compensation under its stated terms
Disputes also go through arbitration in Hong Kong.
Meanwhile, @RedotPay hasn't publicly addressed the India situation on X.
Imagine passing KYC, loading your card and using it for months, only to discover your country was never eligible for card issuance.
This is exactly why I track country restrictions and issuer rules on Card Map.
Is your crypto card actually issued for the country you live in?
cardmap.org

PJ retweeted

$BTC: In the event of a World wide global cyber attack that targets banks and the entire infrastructure as a whole, the only asset I want to hold in such a time is Bitcoin. It’s offline, can’t be hacked and its value will keep increasing as people will flee the Fiat and buy Offline Value.
PJ retweeted

Explaining Bitcoin simply is incredibly hard. Great work by the @tether team.


PJ retweeted

Possibly the best Bitcoin explainer video for kids and adults 🧡
by @tether
PJ retweeted

I don't think people realise how big a deal this is.
If you have cancer, or somebody you know has cancer, there is a company in Hyderabad that wants to build a personalised cancer vaccine for you.
Try approaching any big pharma company and asking for a personal vaccine. If they even reply to your email, this is the response you'll get: we don't do that here.
PopVax, on the other hand, takes your tumour sequencing data (or a sequence you've designed), designs candidate neoantigen vaccine sequences with their AI pipeline, produces the mRNA, encapsulates it in their LNP formulation, fills vials, and runs QC, all in 8 to 10 weeks. They’re publicly committing to capacity for 100+ of these over the next 12 months and asking people to email them their cancer type/stage and sequencing details.
What a time to be alive.
