





Pinned Tweet
Fundamental equity research in software is challenging due to limited alternative data to support a thesis and complement your research mosaic.
That's changing.
repvue.com/data

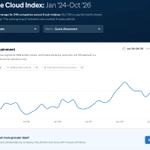
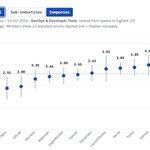
Excited to launch our new RepVue Cloud Index tool - a more dynamic and granular way to keep a pulse on the vibes and execution of Software sales.
Check it out: repvue.com/cloud-index
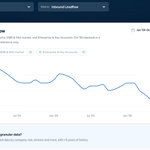
Couple of takeaways - execution metrics and sentiment metrics are heading in different directions...
Quota Attainment - modest improvement


Quotal No.5 4/6 · 5 letters
⬛⬛⬛🟨⬛
🟨⬛⬛🟩⬛
⬛⬛🟨🟨⬛
🟩🟩🟩🟩🟩
repvue.com/quotal


$BRZE sales reps had ranked $CRM their #2 competitor the face most frequently in head-to-head deals, behind Iterable.
$CRM sales reps have named 44 different companies as competitors (#1 $HUBS #2 $MSFT #3 $NOW #4 Anthropic #5 Zendesk) ... not one of 1,292 competitive votes named $BRZE
In our Marketing Tool benchmark for Q3, $BRZE ranked #1 in Product Market Fit, Future Outlook, Culture and Leadership sentiment from its sales reps.
Braze was selling hard against Salesforce and doing a good job at it.
If you can't beat em, buy em.
Nice pick up for $CRM.


Why is average tenure in tech sales 18-24 months?
Well its really hard.
$NET


based.

Five quick SaaS takes:
1) $WCLD is now +72% in the last six months (!!) which is by far the biggest run in % terms since the pandemic.
2) The dispersion is violent- cyber/infra names like $TEAM, $OKTA, $GTLB, $SNOW, $CRWD, $DDOG et al are up 150%+, while companies without clear AI stories yet like $KVYO, $HUBS, $PCOR, $ZM, $TYL etc. are up <20% (some are down!).
3) I don't know how else to put this, but if you find yourself more bullish on SaaS overall than six months ago, something's not right with your process/investment mindset. Aside from a quarter or two of on-trend results, absolutely nothing has changed- if anything, the SaaS bear case has strengthened materially as AI model improvements have continued. You can now effectively one-shot simple SaaS apps. A big question for the future is whether infra is next- I'm skeptical but it isn't impossible to imagine a world in 2-3 years where someone can one-shot, say, Datadog and replicate it based on their current set-up. P(weird) in software has definitely, definitely gone up in the last six months.
4) So far, the most relevant cut is apps vs. infra (cyber counts as infra given how it is packaged/sold). Even Five9 (!!) is up 81% YTD now. In general, pure app vendors have done fine results-wise but have no answer for driving real AI acceleration yet. Their business models need to be re-architected for it (switch to consumption pricing, etc.) and tbh most productivity improvements have driven value for OAI/Ant vs. the app layer, even if the app layer hasn't lost relevance per se. The big test for the next year is whether some app vendors find their legs or not- I don't think the lack of progress so far is dispositive, but in a year that will be a different story.
5) As far as I can tell, while there is dim awareness of this, this mean reversion hasn't impacted sentiment/interest in software in Silicon Valley in the slightest. Interest in anything resembling traditional software remains remarkably low and skepticism remains high, in part because of the pace of model improvements. The valley is anchored to AI optimism and (to them) that naturally leads to software pessimism. The good news for the public/mature names is that there isn't a wave of well-funded competition coming- but it remains nontrivial for SaaS companies without clear AI stories to get funded, even if their public comps have done well in the last six months.
