

Author: The Investor's Mind, Framing Business Uncertainty | https://xitter.cf/t.co/B2IsdWeoo8 | https://xitter.cf/t.co/bDKgZLuYEH
Greener outside of London
Joined November 2016
- Tweets31.4K
- Following230
- Followers16K
- Likes38.9K




Pinned Tweet
When everyone is pumping the CDMO narrative, don't ask who is a CDMO. Ask who would still be a CDMO if the word disappeared from the presentation or annual report ...


Between the Lines: Sona Comstar Q2 FY27
A company that is already excellent at its core should be able to build new businesses large enough to make the core smaller. Think about Laurus Labs: what looked like an ARV company in 2017 looks very different now that CDMO has become a much larger part of the business.
The Q2 FY27 call is the first meaningful evidence on the thesis, for or against. What follows is a close reading of the call: what management said, as closely as the transcript allows, and what I hear underneath.
antifragilethinking.substack…


Not many read the rules of engagement. They were always free and never behind a paywall. The whole point was to judge the thesis against conditions written down before the evidence arrived. The share price was never the test.
antifragilethinking.substack…

Ather has a lion's plans and a fox’s frugality. Intent is confirmed, but Ather is still capacity-limited.
#AtherEnergy
Ather built like a fox. Now it has to scale like a lion.
₹9cr EBITDA.
−₹33cr operating profit.
+₹43cr other income.
The gap is where the interesting story begins.
Ather Energy: Five Fables, One Inflection Point
What the numbers say about the next eighteen months.
Five fables. Three reality checks. Three weighted scenarios.
The full eight-frame analysis is available to paid members
antifragilethinking.substack…
#AtherEnergy


Tech Mahindra and Tata Elxsi: What would they do if it were true?
antifragilethinking.substack…

Nifty pharma index gave breakdown exactly when random person became super bullish last month. Common sense is uncommon
Pinned X was timely warning
#Lupin crossed ₹2500 crore of PAT in FY17. It took eight years to get back above it.
In 2015, the market was paying ~40x earnings.
When the valuation is that high, “profits will grow” isn’t an assumption. It is the investment thesis.
Profits did grow. Just too late. The stock is still below its 2015 level.
Lupin is a case study for today’s “hot” themes: CDMO, aerospace, AI/semiconductors, defence.
Great stories. High multiples. Profits that have to arrive on time.
History often rhymes.

“CDMO wale sir”
That’s a strong branding. Pinned X since September 2026. X is not f(X) is the framework to deploy across aerospace, semiconductor, defence … and most narrative heavy and cash flow low stuff out there


Invert. Always.
Instead of asking, “Are valuations high?"
I’d ask: “ At what valuation would I consider a high-quality management team dirt cheap? ”
Recent history gives us a useful reference point. There was a stock that traded at 0.5x sales and eventually reached 15x sales.
I was super bullish on this. Publicly. Repeatedly. Despite being mocked, I stayed bullish. Publicly.
That rerating alone was a 30-bagger.
The other 30x alpha on base capital came from the growth in sales, taking the total return to roughly 60x.
So, are valuations high?
I don’t know.
Are they dirt cheap?
Clearly not.

Make small mistakes.
Don’t perish.
Survive to fight another day.
#Heuristics: X is never the same as f(X).

#Heuristics
My portfolio is also bleeding.
And yet, a slow, Chinese-water-torture-style correction may help wash away the last remaining survivors of the COVID-era fast-recovery expectations.
Slow bleed, longer bleed …
Sometimes, you don't need to become stronger.
You just need to survive. Datey Raho!

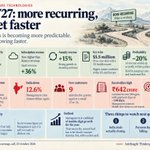
#Newgen, Q2 FY27: more recurring, not yet faster
Open to all subscribers, including free subscribers.
antifragilethinking.substack…

Listening to others talk about drawdowns is a simulation. Living through your own is the clinical trial.
That’s where most investors fail.

People who refuse to read, think and understand will often call what they cannot see “cryptic”.
That is less a criticism of the message than a confession about the reader :)
Solara Active: I trust Sandeep Rao and the team, and I see Q2 as a positive performance delivered amid an unusually challenging operating environment. The bigger question is not whether Solara had a good quarter, but whether the capabilities being built can compound into better economics and cash flow over time.
The community questions have been thoughtful and challenging, which is exactly what I hoped for. I’m working my way through them as quickly as I can and will respond to as many as possible.
antifragilethinking.substack…
Disclaimer: This is my personal analysis, not investment advice. I own shares in Solara and may be wrong!

~30+ Q&As ... quality of the questions speaks volumes.
#SolaraActive

In 2018, Biocon traded at nearly 10x sales. I sold.
My wife refused to sell more than half.
We were both partly right.
A shareholder’s reflection after 22 years 👇
#Biocon: Beyond the Balance Sheet
antifragilethinking.substack…

My “guidance” is what I published on Substack yesterday after the earnings call.
For general investors, I’d suggest that they assume the worst case scenario and then work out their exposure and capacity to suffer.
Useful mental model: X is not f(X)
| Solara Active

@unseenvalue Solara business story is clearly improving. Still not at Eureka Moment The cash story isn't there yet. belive things to watch are working-capital conversion in H2 and the Ibuprofen review . guidance needed