





Maximus retweeted

Thursday, November 5th, was a day of extremes:
•US long/short Hedge Fund net leverage declined by 5% day over day, the 5th largest single-day decline since 2010. Net leverage is now in the bottom decile since 2010.^
•Long/short fund active gross flow since June has amounted to a -10.7% reduction relative to their gross market value at the end of June, the most in at least 10 years.^
•Hedge Funds are now underweight AI stocks* relative to market cap weights, but AI is still a very large percent of absolute exposures at 32%.^
•Levered ETFs had the largest amount to sell on data going back to 2007, bringing $57bn of US equity supply.
•Retail selling of US equities in the first 90 minutes, based on MS QDS estimates using public data, was the second largest going back to 2016.
•Equities are now starting to trade in a more correlated fashion, often signaling that risk reduction is broadening out.
^Sourced from MS Prime Brokerage.
*AI stocks defined as the constituents of the MSXXAI Index, made up of AI tech beneficiaries, AI power names, and key hyperscalers


Maximus retweeted
Today’s equity selloff is expected to create significant supply.
Levered ETF rebalancing today should create $52bn of US equity for sale if prices at November 5th, 1pm, hold through the close on MS QDS estimates – that’s second only to the $55bn sold on June 5th, 2026. Semiconductors will bear the brunt of that supply, where there should be $21bn for sale, with NASDAQ 100 seeing another $15bn for sale.

Maximus retweeted
Yesterday we highlighted that the volatility market was pricing a small potential move in the S&P 500. The index ended up 1.6% on Nov 4th, well beyond the 1.2% move implied by the volatility market.
The Momentum factor* fell more than 6%, placing in the bottom 1% of all daily returns in at least a decade. Prior winners fell almost as much as prior losers rallied. Semiconductors fell below July lows while Consumer Discretionary outperformed Energy by over 9%.
Remarkably, the Beta factor* is down almost 3% despite the sharp rally in equities. This comes on the back of its worst month in 15 years, with Beta falling 22% in October.
YTD stats are striking. Beta is down 11% and Momentum 14%, while the S&P 500 is up 12%.
The simultaneous selloff in Beta and Momentum has echoes of July, but the drivers are different.
July was the worst month for Momentum in 15 years, driven by a positioning unwind as investors sold prior winners. October was the worst month for Beta in 15 years, driven by a broader macro shock as tightening financial conditions punished high-volatility stocks.
* Morgan Stanley Institutional Equity Division is measuring Momentum here as the performance difference between the top 200 outperformers vs. the bottom 200 underperformers of the Russell 3000 over the past 12 months with a 1-month lag. Beta is measured as the performance difference between the top 15% of liquid Russell 3000 members based on 6 and 24-month betas and the bottom 15% on the same metric.
Maximus retweeted
Implied volatility markets are not pricing midterm results to be a big event.
The forward volatility market is implying just a ~1.2% move in the S&P 500 Index tomorrow. That’s below what was implied one day ahead of 3 of the last 4 midterm elections. And it’s below what the S&P 500 realized after the 2018 and 2022 elections.

Maximus retweeted
Today marks only the 2nd day this year that retail investors have been net sellers.
MS QDS estimates, based on public data, that retail investors sold $1.4bn of US equities today — their first net sale since April. This is after retail has bought more than $1 trillion of ETFs and stocks YTD.

Maximus retweeted
The unwind in Hedge Fund equity exposures this year has been the biggest since at least 2017.
Active de-grossing (reduction in long + short positions) by global hedge funds has now hit over 8% of total gross exposure since June, according to the Morgan Stanley Prime Brokerage Content team.
This has taken gross leverage for US long/short funds down to the 10th percentile versus the last year.

Maximus retweeted

The PPI-CPI Gap Is Wide, and It Rarely Stays That Way
Producer prices are surging, and it’s unlikely firms can absorb this through margins.
Headline PPI +1.3% m/m, the strongest in 4+ years, and +6.4% y/y. Core PPI (ex food, energy & trade services) +0.5% m/m, +5% y/y, the fastest since 2022.
The PPI/CPI link is loose, but core PPI this hot rarely fails to pass through to core CPI.

ALT #inflation #macro #real estate #economy #fixed income #equities #fx #dollar #FedFund #mortagaes #Fed #ECB #BoE #BoJ #rates #volatility #TIPS #VIX #SuperCore #earnings #assets #liabilities #balance sheet #options #calls #puts #spreads #swaps #recession #gold #payrolls #unemployment #wages #fedfunds #silver #Trump #tariffs #Lutnick #Bessent #Warsh #S&P #Tech #Semiconductor #CPI #PPI
Maximus retweeted
At Morgan Stanley Equity Derivatives, deep, trusted, long-standing partnerships with the world's top investors are the hallmark of what we do.
Iliana Bouzali, Global Head of Derivatives Distribution and Structuring, sits down with legendary investor Stan Druckenmiller at the TomorrowX Summit on November 17-18 in Austin to explore macro, markets, the thinking behind the trades, and what the future may hold.

Taking the stage at @TomorrowXSummit: Stan Druckenmiller (@standuquesne), Chief Executive Officer of Duquesne Family Office, and Iliana Bouzali (@ilianabouzali), Global Head of Derivatives at Morgan Stanley (@MorganStanley) $MS.
November 17-18 at the Moody Center in Austin. Hosted with @GavinSBaker and @atreidesmgmt, @antoniogracias and Valor Equity Partners, @rbiscardi and @iconnections_io.
Registration link below.

Maximus retweeted
In an AI world, the most valuable investing skill will be … “creativity." Justin Lubell of @Citadel talks conviction and the role of human judgment. Watch his full Break the Playbook conversation with @MorganStanley Derivatives. mgstn.ly/4imYQgm
Maximus retweeted
The goal is “intellectual conviction as opposed to emotional conviction.”
@Citadel’s Justin Lubell joins Break the Playbook to discuss finding top talent, backing ideas with intellectual conviction, and why investing remains a deeply human business.
Watch the trailer:
Maximus retweeted
The rally in S&P 500 has the index hitting the peak dealer gamma wall of $24bn near 7845 in spot, per MS QDS.
But much of that dealer long gamma expires today. Absent new customer supply, that stabilizing force gets smaller, leaving the market freer to move.
Maximus retweeted
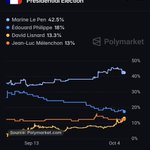
Thank you for this. However I would caution against falling in the easy “Le Pen vs Melenchon” narrative which is not representative of what the betting markets are telling us.
David Lisnard has been making huge strides lately and is fiscally very conservative/responsible. He’s the French Milei (and so is @knafo_sarah but unfortunately she is not running).
He’s just not polled (yet) bc started from too low.

Maximus retweeted

1/ There's a scary chart going round on X: junk bonds ($HYG) at a 52-week low while $SPY sits 1.4% off its record.
Scary, because credit markets are usually much better at sniffing out trouble than equity markets.
Anyway, I pulled it apart.
BlackRock runs a version of $HYG with the Treasury risk hedged out ($HYGH). Over the past year HYG is down 4.1%. HYGH is down 0.4%.
So about 90% of HYG's damage came from duration. The part that prices default risk has barely moved, and junk spreads sit 13bp from 3-year tights
So the scary chart is mostly bond maths. The basement of the junk bond market is a different story however 👇🏻

Maximus retweeted

The 15-month rate of change in FINRA debit balances, a proxy for margin-driven speculation, has dropped back below 60%.
In prior cycles, this has coincided with major market tops.


Maximus retweeted
Watch @davidein’s full conversation for Break the Playbook, a series from @MorganStanley Derivatives with investors who challenge conventional thinking. David talks everything from how he plays poker, the signal from macro and fiscal risks, the future of AI and more.
mgstn.ly/4j928oj

Maximus retweeted
From poker investing lessons, to what he's changed his mind about, how he invests in AI, and the personality trait that has made (and lost) him the most money, @davidein and Iliana Bouzali cover a lot of ground in the next episode of Morgan Stanley Derivatives' Break the Playbook series. Full interview coming soon.
Maximus retweeted

Anthropic's new threat report reveals that a cell in northern Yemen (highly likely Houthi-linked) used Claude Code as a substitute for an entire missile engineering team.
They ran multiple Claude instances simultaneously — one writing code, one researching, one reviewing — to develop guidance software for a tactical guided rocket, a 2,000+ km ballistic missile, and a hypersonic glide vehicle variant called "R2000."
The specific tasks: integrating open-source autopilot onto a phone-class flight computer, writing navigation and control software, running six-degree-of-freedom trajectory simulations, and using reinforcement learning to tune flight-control algorithms.
They compiled everything into a standalone offline executable so they could keep working without Claude.
They actually test-fired a guided rocket in Yemen.
It appears to have failed.
Within hours they were back in Claude doing post-test failure analysis on the telemetry data.
Anthropic's safeguards blocked many requests but the operators evaded them by hiding the end use, splitting work across many sessions, and using other workarounds.
Linked accounts were banned.
Anthropic says there's no evidence they fielded an operational weapon — but they already had an offline toolkit that no longer needed Claude.
This is one of six conventional-weapons cases in the report (three China, two Russia, one Yemen), alongside cyber ops, influence campaigns, a Mali-linked mass surveillance platform, bio-misuse attempts, and Chinese labs illegally distilling Claude.


Maximus retweeted

US corporate profits are now way above their long-term trend.
They’re about 20% above the trend since 2000, the largest divergence on record.

