
Private biotech
Joined February 2016
- Tweets2.5K
- Following481
- Followers229
- Likes2.2K




This is amazing

I have sadly betrayed the puffy vest community...
This post made me laugh out loud... well done to "Chad Whitlow, Founder and CEO, Vestibule AI"
I'm zipping my vest up right now.
inpreparation.substack.com/p…
27
Ebenezer retweeted

wtf now my agents found the first bacteria to use new stop codons!!
After this TAG result, a chat w/ friend inspired the question: do any bacteria use other stop codons?
Overnight, my guys found myxobacteria that stop at TTA, normally read as an amino acid.
Evidence:
1) These bacteria lost the tRNA that normally reads TTA as leucine.
2) Their RF2, the protein that recognizes stop codons, has two changes: one in its codon-reading tip (SPF → SPY) and one nearby (L → F). No other species in GTDB has both.
3) We compared the same genes in these bacteria and their closest relatives. Where a relative's gene ends at a normal stop but the gene here keeps going, the very next codon is TTA 11% of the time (252 of 2,339 genes). In the relatives, it's 0.05% (1 of 2,025).
4) TTA swaps with the normal stop codons. Where one of these genomes ends a gene at TTA, another genome from the same group ends that gene at a normal stop 78% of the time.
Method:
Claude agents on my Mac mini scanned all 199,923 bacterial and archaeal genomes in GTDB for amino-acid codons unusually common near the ends of genes, where a hidden stop would sit. In 4,599 genomes, they then matched each gene to corresponding proteins and checked which codon sits exactly where the known protein ends.
Closest prior work:
TTA works as a stop in some mitochondria and plastids (Barcytė et al. 2025), and CGA was proposed as a stop in Asgard archaea (Melnykov 2026, PNAS), but none in bacteria until now.
One of these bacteria, 1-FT3.2, is kept alive in Finland (Demina et al. 2025). Possibly its proteins can be measured to confirm this.


Ebenezer retweeted

Introducing Helios: measuring 1,000+ protein biomarkers from a drop of blood to help you live younger, longer.
Here’s how it works:
• Self-collect blood at home with a painless, needle-free device
• We measure the proteins carrying signals from cells and organs throughout your body
• Your Helios AI agent explains your results, highlights risks, and offers personalized guidance
Proudly backed by Y Combinator and Formation VC.
Join the waitlist at myhelios.com
Ebenezer retweeted

You mean you don't appreciate when your biotech holding with fantastic data is up 40% in the premarket with 50% more upside to fair value, and then gets crushed to flat at open because risk at a large MM market sold a pod's holdings for blowing up on a MRNA short position, and then a quant momentum strategy shorts it because of the big pullback, and then a quant fund piles on the selling pressure by hedging their AI long trade by shorting interest rate risk out with a SMID cap biotech short, and then the stock is down 15% and no one knows why so an analyst publishes that obviously the stock is down because (pick random datapoint that doesn't matter) but in reality was just persuaded on a call with a pod PM to be bearish because they had a short position they needed to press and then that narrative gets entrenched and you're sitting here wondering why this company swung 60% down on great data and is financed through CF+ and trades at a big discount to some other biotech company and the world moves on to the next company with data tomorrow and no one cares to re-visit your company because it's a "catalyst desert" for 3 months? And pharma then passes over it and buys an undifferentiated pre-clinical private China asset instead of your company, which blows up on them a year later and they write it down but now your company needs to finance at a discount to the prior data?
How could you not love that?

Ebenezer retweeted

13F season is back, which means another round of “BUFFETT BOUGHT X” or “CITADEL LOADED UP ON X” headlines.
Most are familiar with/ the 45-day lag, quarter-end snapshots, and the multitude of positions types/ exposures excluded from filings. One thing I’ve noticed gets far less attention is that 13Fs reflect aggregate holdings across a firm's various funds and strategies.
This is particularly relevant for multi-strats like Citadel, which have dozens of underlying strategies, PMs, and quant-driven books. Even healthcare/biotech specialists, which tend to offer a somewhat clearer picture, often manage several strategies beyond their original flagship fund, ranging from long-only and crossover to private/venture.
Redmile is a good example. Looking at its Form ADV gives you an idea of how many different pools of capital can sit behind a single manager's 13F. Something to keep in mind when interpreting quarterly position changes or trying to infer a manager's conviction in a particular stock.

Ebenezer retweeted

$ACRS unfortunately another anti-TSLP failure in AD:
Anti-TSLP Monoclonal Antibody Bosakitug (ATI-045) ADMIRATION Trial Did Not Achieve its Primary Endpoint
TSLP key role in activating Tregs may be the problem, I continue to be wary on this target
investor.aclaristx.com/news-…

Ebenezer retweeted

Happy #JefferiesHealthcare to all who celebrate

NEW from @FT: Johnson & Johnson is poised to buy privately held eye disease drug developer Ollin Biosciences for up to $3.4bn, the latest in a glut of bolt-on acquisitions in the biotechnology sector.


Ebenezer retweeted

Comprehensive list of hedge funds blowing up this week, getting large redemptions, or shutting down PMs:
- Axebrook
- Walleye
- Engineers Gate
- Lone Pine
- Millennium internal pods
- Verition pods
- Samlyn
Letter from Walleye closing internal funds below

Ebenezer retweeted
AI hyperbole has consequences. "AI will take 50% of jobs" & "AI will cure cancer" are both overstatements. The positive overstatement promotes investor excitement, & the negative fear in citizens.
Combination is dangerous concoction driving a simultaneous bubble & revolution.

‘“That’s complete BS,” said Jeff Leiden, executive chairman of Vertex Pharmaceuticals. Vertex has used roughly 50 AI companies to comb through its data set of 10,000 drug compounds, Leiden said. Not one managed to generate a working drug.’ 👇🏼
wsj.com/tech/ai/silicon-vall…

Great breakdown

16 big pharmas. 2,000+ M&A comments since 2024.
Where they said they were looking vs. where they’re looking now.
The stage split: Sanofi, BMS and Regeneron are now open to commercial-stage assets. Biogen, Pfizer and Amgen moved earlier, toward Phase 1–2 and platforms.
China is now a named deal source for 11 of 16.
Immunology is being carved up by sub-area: IBD combinations (Gilead, Merck, AbbVie), dermatology and respiratory (Sanofi, AbbVie, GSK), and in vivo CAR-T and immune reset (Lilly, J&J, BMS).
The obesity buyers have mostly bought. Novo says obesity is no longer at the front of its BD, and AbbVie wants a partner drug for its amylin.
1. Sanofi set up a big late-stage deal in one quarter. Oct 30 is the sharpest pivot in the set.
Stage: “early, early” deals became “later-stage commercial assets”.
Urgency: “not chasing growth” became Dupixent’s loss of exclusivity as the “top priority”.
Areas: neurology was dropped, and non-core areas may be out-licensed.
Firepower: EUR 15B+ became “not in a position to give you an amount”.
Rating: “AA” became “strong investment-grade”, with external financing mentioned.
Hint: refusing to size firepower while loosening the rating language buys room for something bigger than EUR 15B, possibly debt-funded. The mid-December update is the tell, and they said a deal “can be communicated at any time before”.
2. Vertex’s “no change” lasted five weeks. Asked on May 29 whether its appetite for bigger deals was changing, the CEO said “No”. On July 6 it agreed to buy Crinetics for about $10B, its first debt-funded deal, double its previous record. It bought before Phase 3 data because it “didn’t want to wait… or potentially see another bidder”.
Hint: a company’s denials about deal appetite are weak evidence. Watch what it pays, not what it says.
3. Gilead says “no more deals this year”, then keeps dealing, and cash returns are slipping. In August it said it did “not currently anticipate pursuing additional sizable M&A transactions this year”. By Q4 it had $1.4B of new upfronts, including an oral IL-23R for IBD. Shareholder returns ran about 40% of free cash flow through Q3, against an “at least 50%” commitment. It also admitted a 2027–29 pipeline gap after saying in 2024 “we have what we need”.
Hint: deal spending is crowding out shareholder returns.
4. Merck’s urgency drained out.
Language: “top priority… with urgency” (Q3 2025) became “We are not desperate to do any deal”.
The script: BD slipped from “high priority” to “important priority”, and the CEO’s prepared remarks didn’t mention it.
Size: going above $15B is now “harder”.
Hint: after Verona, Cidara and Terns, Merck is digesting. A mega-deal looks less likely now than a year ago.
5. Lilly is moving cash from buybacks into risk.
Capital: buybacks fell from $2.4B in Q1 to $0.4B in Q3, while acquired IPR&D hit $4.57 a share, against $0.71 a year earlier.
Cell therapy: from “nothing going on in cell therapy” (2024) to in vivo CAR-T as “a huge opportunity”.
Neuroscience: an explicit build into sleep, psychiatry and pain.
Scope: BD is now “not solving for any one given therapeutic area”.
Hint: the incretin cash machine is funding the most aggressive diversification in the group. Dec 7 is likely where Lilly frames it.
6. Novo narrowed on size but widened on areas.
Size: “$20–40B, we could afford it” (January) became bolt-ons only.
Areas: “we are really good when we focus” became new Blood & Endocrine, Liver and Cardiovascular segments, plus Consumer Rx, pain and addiction, and women’s and men’s health.
Obesity: BD there is “not at the forefront”.
Hint: expect many small deals outside obesity, sourced partly from China, rather than one big one.
7. Biogen reversed its stage preference within eight months. In early 2026 it wanted Phase 3 or launched assets up to about $5–6B; now it “always hated having to go buy assets in later stage” and wants development candidate to Phase 1b.
Hint: Apellis filled the near-term gap. Biogen is out of the late-stage bidding pool until its debt is paid down at the end of 2027.
8. Regeneron contradicted itself on deal rationale. In March 2026 IR said M&A would never be driven by commercial synergy; on Oct 30 using its commercial reach is a stated criterion. At the same time it calls itself a “net out-licensor of innovation” after handing four antibodies to the Sanofi alliance, and it says “No aversion whatsoever” to a deal of size.
Hint: it’s openly hunting a commercial-stage asset and repeatedly says it lost auctions on price. That makes it the most likely surprise buyer among the “not done anything big” names.
9. AbbVie signaled an obesity partnership. After Apogee it says “more bolt-on additions. Versus a large transformational deal like Allergan”, but its CSO is now open to a partner drug, possibly from the incretin class, to co-formulate with its amylin drug.
Hint: watch for an incretin licensing deal rather than an acquisition.
10. Smaller tells worth noting:
J&J: the CEO says of the AAA rating, “We are not married to that”. GLP-1s and pulmonary hypertension are explicitly off the table, and its 2030 target assumes no deals.
Takeda: it said nothing about BD on its Oct 29 call. Strategy is deferred to the Dec 11 Capital Markets Day.
AstraZeneca: it says it prefers early-stage deals, yet every 2026 deal was late-stage or commercial and sourced from China. Soriot floated an Alexion-size 10–20B deal, “even 20–30B”.
Pfizer: it now flags political risk from Beijing as well as Washington while calling China its main source of deals.


56


Ebenezer retweeted
Surprise 1: Anthropic acquired a one-person biotech
.
.
.
Surprise 2: that person is me
Surprise 3: I’m here to tell you all about it
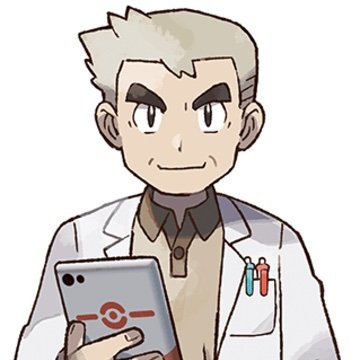
Yes, this is what you think it is; after 6 yrs of increasingly loose anonymity: the Professor Oak reveal post
…and yes, it has gotten so boring around here that I’m literally doxxing myself to spice up the timeline
-------
Ok, allow me to introduce myself. My name is Cody Tranbarger. I mostly tweet, but occasionally find time to dabble in drug dev & starting/building biotechs. My past lives span the VC, crossover, startup continuum; Prof Oak has been my way of keeping a digital foot in those worlds, despite having my physical feet planted elsewhere.
The past 18 mo, ‘elsewhere’ was Mithril Medicine, a co. I founded to develop bsAbs for LAMA2-CMD & other ECM-related genetic diseases.
Mithril was born out of hands-on building with @MikeNGladstone, @JasonPaulRhodes, @LifeSciVC, & team @atlasventure. Somehow, I made enough half-decent calls along the way (even a broken clock is right twice a day, eh?) to convince them Mithril/I warranted a small seed. While I can hardly rationalize such an outrageously cavalier bet, I’m grateful for it, & I'd partner with Atlas again in a heartbeat.
In typical AV fashion, Mithril’s primordial form was virtual, decentralized, & ultra-lean. This stage tends to be short-lived, but for Mithril, it worked surprisingly well, for surprisingly long, thanks in part to the rapid maturation of the AI tools I used liberally.
Eventually, Mithril became a bit of an experiment itself - to find the upper bound of how far it could scale as a single operator + a bunch of Claude (+ a stellar bench of part-time consultants).
In parallel, I started spending time with @nc_frey, @an1lam, & @CoefficientBio team; and promptly experienced, for the 1st time, AI at the frontier. Soon thereafter, Mithril stopped looking like an experiment, & started looking like a preview of an entirely new operating model.
From that spark came “Pipeline-in-a-Person.” The idea immediately resonated when we shared it here back in April; and it was central to the shared vision that led to Anthropic’s acquisition of Mithril, & my joining the team.
Why join Anthropic? Three reasons.
(1) For Mithril, the programs continue, with more resources & infrastructure behind them, and as much Claude as I can put to work.
(2) For me, the chance to start several more programs, & find out how many one person can actually run in parallel - an almost unprecedented luxury for a curious drug hunter.
(3) For our mission, a path to institutionalize & scale this new way of working, then put it in the hands of all of biopharma, all over the world - which, candidly, I find the most energizing.
Will AI x Bio cure diseases? Unequivocally yes, imo… but not by the route that gets the most airtime. Rather than timeline acceleration & compression, I see orchestration & parallelization as today's low-hanging fruit.
Most drug hunters see a handful of go/no-go calls in a career, & spend entirely too much of the rest trading emails (my inbox can attest).
Give them the bandwidth to run several programs at once, and the time to focus on scientific judgment, and I’m willing to bet they’ll make better calls. And at scale, better calls translate to more drugs, higher hit rates, broader patient impact, & likely, a disease or 10 or 100 cured. I couldn't be more excited to build toward that future @AnthropicAI.
Finally, a heartfelt thank you to BioTwitter/X. The end of anonymity is bittersweet, but if anyone’s earned a proper introduction, you all have.
It’s difficult to overstate how much this app has done for me: a decade of education, plenty of friends, many job opportunities, several mentors, a few investors, even a co-founder (fmr). It was the generosity of this community that inspired me to start posting 6 years ago, after just as many years lurking. I hope I’ve been able to pay it forward, in my own small way.
But, to be clear, Prof Oak isn’t going anywhere. Same beat, same themes, and now, a front-row seat to drug development at the frontier. Stay tuned for dispatches from the trenches; and remember...
Gotta Cure 'Em All
Ebenezer retweeted

“infinite compute can’t help you simulate a system that’s never even been observed or measured”
the most eloquent explanation to why ai ain’t solving aging in the current status quo

Am I missing something?
Where do the inputs to train this simulation come from? Compute is not the bottleneck in biology.
It’s estimated we have only sequenced genomes for 1% of eukaryotic species, and DNA is just the beginning.
Infinite compute can’t help you simulate a system that’s never even been observed or measured.
Ebenezer retweeted

I’m not sure I understand how this would work. If you put limitations on investments from US entities, doesn’t that just channel those investments through non-US entities?
Either way it doesn’t prevent those molecules from entering US trials and outcompeting US-funded ones

This could put a damper on China pharma deals (and other investments) in an unexpected reversal endpoints.news/treasury-prop… probably will be viewed as positive for $BBC and $XBI
Ebenezer retweeted

One month (or so) on @X , a platform unlike any other. Energy, speed, smarts and stupidity.
-The best thing in BioX - Rapid and divergent takes on new clinical data, on balance usually right..wisdom of crowds
-The worst thing on BioX - Shameless replies and reposts pumping your own book, praying for M&A about your favorite name, plane stalking…do people actually think this is how a real drug company or serious investor makes decisions? Maybe it just makes you feel like you have some agency, then ok.
Some really good insights here.
One thing I'd add is EU pharma loses the bid almost 100% of the time the process moves through the Nov/Dec holiday, mainly through lack of contact with lawyers, bankers, and targets. VTYX was the most recent example

2024 to present, went down a rabbit hole of proxy documents from all the mergers and acquisitions in bioland after @daphnezohar tweet. To try to see if I can find any insights into what the turnaround period could be or what the outcomes may look like. I&I , Onco , rare disease and neuro been the hottest areas, will that continue?
Nephrology have the most parties interested 16 per deal n=2. (Also why $vera m&a will have legs) Actually read below with the graphics in the subtweets that will be easier and better.
Findings:
The first mover usually loses once a second bidder appears. In the 18 competitive deals the first party to name a price won only 44% of the time. $nvs took $trml, $rgls and $mor from earlier bidders; $pfe took $mtsr from $nvo; $mrk took $cdtx from Company D and Terns from Party C.
•Competitive processes run on a clock the company sets. Process letters with bid deadlines ($dcph, $akro, $cdtx, $trml, $mrus) and a best and final round are the standard tools. $cdtx committee added a rule that the winner had to clear the next bid by 5% or the top two went another round.
•Single bidder deals price the gap with CVRs instead.CVRs appear in a larger share of single bidder deals; with no second bidder, the contingent payment is how the board closes a valuation gap (Poseida, $etnb , $verv, $bpmc, $aclx, $apls).
•Exclusivity is a prize, not a default. It is granted in a similar share of both groups, and when it is granted it is usually short and bought with a price step ($dawn got $1 more for 8 days; $mor got $57 for exclusivity to Jul 11; $swtx got $50 instead of $49). Deals that refused exclusivity entirely did not give up any bump.
•Competition does not make deals slower from first price. Median first price to signing is similar in both groups. What stretches competitive deals is the longer run up: more parties approached and more diligence before the board lets prices crystallise.
More insights below..
Deals announced in Nov would have most likely had their 1st offer late Sept or Oct.

1
68


This was very good

Dialectic 60: Patrick Hsu!
@pdhsu & @arcinstitute are combining biology, engineering, and AI to turn a sci-fi future into reality.
Patrick got expelled from college at 13, returned at 15, later worked on early CRISPR breakthroughs, and teamed up with @SKonermann & @patrickc to found Arc.
He works 3 jobs: core investigator at Arc, professor at Stanford, and venture partner at @thrivecapital. For all his intensity and ambition, he carries a lightness and boldness that is contagious.
We discuss:
- why research is 99% failure and even your best ideas kind of suck
- infinite games and speedrunning school
- the reach of GLP-1s and power laws in biotech
- what makes a good biologist
- Arc’s bet on people over projects
- lab robots that finally work
- AI-designed organisms and new forms of life
- why heart disease could go the way of infectious disease
- bro science, peptides, and biofuturism
- research taste in the age of AI
Timestamps:
(0:00) Opening Highlights
(1:39) Intro: Patrick Hsu
(4:29) Start: Boldness, Infinite Games, & Ambition
(12:54) GLP-1s and Power Laws in Biotechnology
(20:17) Expelled at 13 and Falling for Biology
(25:51) What Makes a Good Biologist, Research Taste, and Biology's Data Challenges
(37:58) The Arc Model: Full-Stack Science
(52:01) Betting on People, Style, & Learning to Simplify
(57:22) Perturbation, World Models, and Evo
(1:03:27) Virtual Cell Models
(1:09:56) Designing Life: From Stem Cells to Genome Writing
(1:18:39) Testing, Bro Science, and Human Data
(1:24:26) Can It Exist vs. Will It Exist: Science Meets Markets
(1:29:59) Biofuturism: Interoception, Peptides, Muscle Modulation, Sleep, and New Forms of Life
(1:43:47) Fun, Obsolescence, Going Slow, and the Future
@dialecticpod 60: Patrick Hsu - Speedrunning the Infinite Game - is available on all platforms, including X. Links below.
1
74