





CryptoBucky retweeted

Peanut Has Heard The Rumors
#LebronJamesOfDriving
#GTA6
CryptoBucky retweeted

Are you guys starting to realize this isn't a March where you buy, run up 200%, and sell 3 months later, right?
This is a market where you buy, hold for 3-4 years, and if you land a winner, you're up 5,000%
Now is not the time to chase the small-cap that gives you a 10x in a few months (and look, I own one, nothing wrong with having one)
Instead, the bulk of your portfolio needs to be the names you firmly believe will be the winners over the next few years
To put it simply: this isn't the time to load up on $TE $WYFI or $BRUN
Again, you can hold one, you all know my moonshot is $SIVE
But right now, your core needs to be $GOOGL $SNDK $MU $NBIS $BE $COHR $NVDA etc
Build what you'll hold for years, and thank me when we get there

The question is:
Is this 2008 🔴, 2022 🟡 or 2018 🟢?
🟢 Based on inflation, it’s closer to 2018, with a 2008-style oil shock on top
🔴 Based on long-term real yields, the cost of capital is higher than in 2018 or 2022, and near the 2008 crisis peak
🟢 Based on credit spreads, it’s far healthier than 2008 and less stressed than in 2018 or 2022
🟢 Based on GDP growth, it’s closer to 2018
🟡 Based on the labor market, it’s nothing like 2008, but looser than in 2018 or 2022
🟢 Based on S&P 500 revenue growth, it’s better than all three
🟢 Based on profit margins, it’s better than all three
🟢 Based on earnings momentum, it’s stronger than in all three, but concentrated in AI
🔴 Based on valuations, it’s pricier than at the 2008, 2018, and 2022 lows
🔴 Based on the earnings yield minus the 10-year Treasury yield, stocks are far less attractive relative to bonds than at any of those lows
🟢 Based on bank lending standards, it’s much healthier than in 2008 or 2022, and closer to 2018
🟢 Based on the yield curve, it remains positively sloped, unlike during much of 2022
🟢 Based on ISM manufacturing and services PMIs, economic activity remains expansionary, much closer to 2018 than to the contractions seen in 2008 or late 2022
🔴 Based on the federal deficit as a share of GDP, it’s bigger than in 2018 or 2022
🟡 Based on household credit delinquencies, financial stress is elevated, particularly in credit cards, but mortgage distress remains far below 2008 levels
Conclusion: The severity of this downturn is closer to 2018, but with some elements of 2022 and the unique complexities of the AI buildout
Given the 23% Nasdaq drawdown in 2018 and the 36% drawdown in 2022, and considering we're already down 18% this time, the pain may persist for a while, but the bottom may not be far off unless macroeconomic indicators deteriorate further

CryptoBucky retweeted
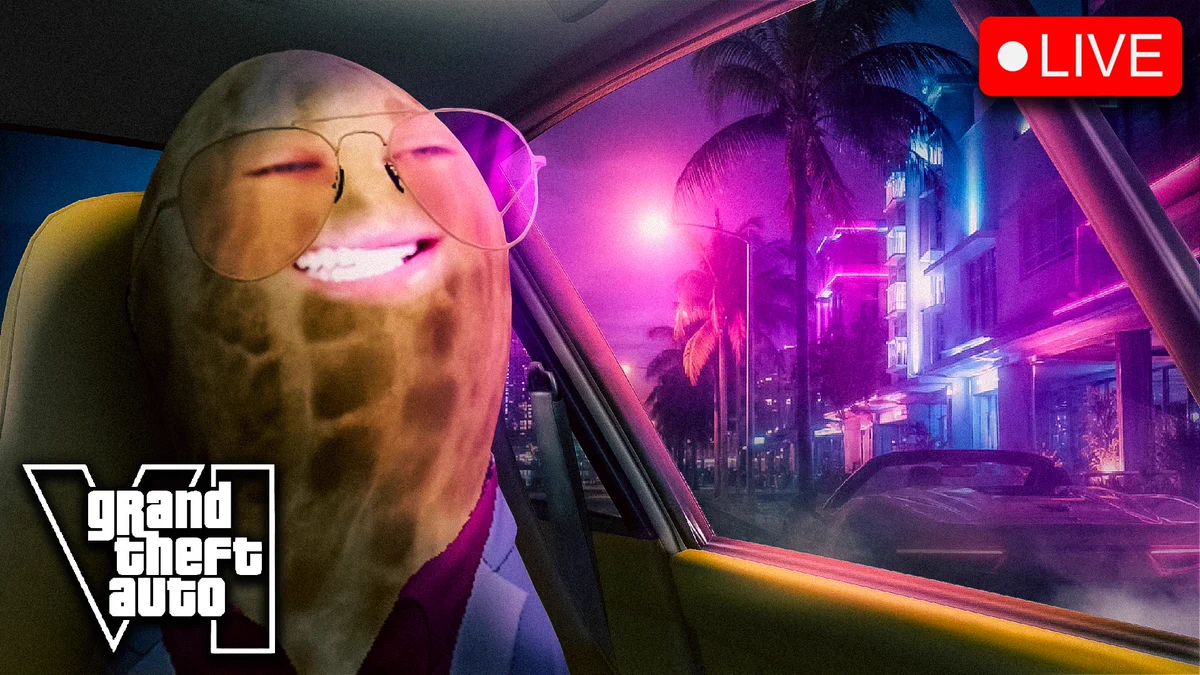
🔴Live | TheBurntPeanut | GTA 6 | #BUNGULATE teapawt.net/i/broadcasts/2XyPAREAR…
CryptoBucky retweeted

The Burnt Peanut literally just finishes saying how "that was a close one" when he almost loses his lambo and then immediately ends up in a river😭😭
"almost saw God right there. almost on his front door step. aaaaaandddd it's gone."


CryptoBucky retweeted

$MU Micron CEO Sanjay Mehrotra:
“Micron has 62,000 patents. Only US company that makes memory today”
“We are well positioned to continue to benefit from the AI revolution”
“Supply will continue to be tight, 2027 and 2028 will be even tighter”
“2027 is 75% sold out.”
“Compute performance has continued to advance more than the memory bandwidth”

CryptoBucky retweeted

$NVDA just did $65B of net income in Q3 with an enterprise value of $3.75 trillion.
SK Hynix is expected to do $65B of net income in Q4 with an enterprise value of $525 billion
Samsung is expected do so $74B of net income in Q4 with an enterprise value of $765 billion.
$NVDA looks cheap against their fundamentals… however SK Hynix and Samsung are just as profitable yet their EVs are 86% and 79% smaller.
Everyone keeps saying its peak earnings for the memory companies but its not showing up in the numbers.
If $NVDA is going to grow revs by 85% (or more) next year and then we have $AMD, TPUs and other ASICs adding to the demand picture… memory revenues will grow at least 50-60% especially when you include HBM and then you throw in 15-20% stock buybacks in 2026 2H and 2027.
Maybe I’m just delusional, but memory stocks should not be trading at 2-3x 2027 EPS if this is the backdrop for demand and hyperscaler capex holds up at $1.2T to $1.6T

Crazy to think that $NVDA might do $450B of GAAP net income next year (FY2028) and the market cap at the close today was only $3.75 trillion so the stock might be trading below 8.5x FY2028 (ie CY2027)


CryptoBucky retweeted
BREAKING: Streamer Konvy steals Rainbet CEO's Private Jet on GTA 6 then gets shot down by the Air Force
🤝 Paid partnership


CryptoBucky retweeted

"I'm struggling to make sense of these rankings."
Jake Butt points out an inconsistency in how the CFP committee treated Indiana and Alabama the last two weeks 👇
CryptoBucky retweeted

I legitimately believe that she thinks she’s informing us & has no idea how enraged she’s making everyone w this explanation
Like we just discovered a breakthrough w how valuable a loss to Arkansas is
No
It makes us want to take out the power grid
CryptoBucky retweeted

"Clearly, this is being done to boost the resume of some SEC teams."
The quartet of 4-loss SEC teams in the latest CFP rankings has Jake Butt's attention 👀
CryptoBucky retweeted

$SLNH | @jbelizaireCEO, how did Kati 2 end up here?
There's something about the Kati 2 tenant situation that I find difficult to reconcile with management's previous statements.
Throughout 2026, John Belizaire repeatedly emphasized that bankability was one of the most important considerations when selecting a prospective AI tenant.
This wasn't something management discovered recently.
In May, Belizaire explained that Soluna was evaluating tenant proposals based on several criteria, including lease economics, contract duration, expected returns and the credit support each prospective customer could provide.
In June and July, after months of discussions with potential customers, Soluna entered exclusive negotiations with a selected prospect.
Belizaire described the LOI as a "material shift" toward securing a lease.
He also discussed the importance of guarantees and whether a tenant could provide sufficient financial backing independently or through another party.
By August, the prospective tenant's technical teams were involved in design work, Soluna had engaged an investment bank to support project financing, and management was discussing construction preparations and the next steps toward a lease.
Investors were given several reasons to believe the negotiations were advancing.
Then came November.
Soluna disclosed that it had decided during Q3 not to extend the original prospect's exclusivity because management no longer expected the customer to satisfy the credit requirements for a lease of this size.
And that's where I have a serious question for John Belizaire.
If bankability was repeatedly presented as a fundamental requirement from the very beginning, how did Soluna end up spending months negotiating exclusively with a tenant it ultimately did not expect to meet those requirements?
Was there an anticipated credit guarantee that failed to materialize?
Did the prospective tenant's financial position change?
Did financing conditions fundamentally alter what lenders would accept?
Or did Soluna overestimate the candidate's ability to support the lease when it initially granted exclusivity?
These are important distinctions.
I'm not criticizing management for refusing to proceed with a tenant that couldn't satisfy its requirements. Protecting the project's financing prospects was the right priority.
My concern is how a requirement management had consistently identified as essential became the very reason the exclusive process ended without a lease.
And this matters even more now.
Soluna has announced a new non-binding LOI for 118 MW, with a prospective tenant management believes will better satisfy its credit requirements.
That's encouraging, but after the previous experience, shareholders deserve more clarity about what makes this candidate different.
I'm still optimistic about Soluna's AI strategy and the underlying value of Kati 2. But optimism shouldn't prevent us from asking legitimate questions about execution, due diligence and management's communication.
John, if bankability was always central to selecting the right tenant, what specifically changed between granting exclusivity and deciding the original candidate wasn't sufficiently bankable?
I think shareholders deserve an explanation.
CryptoBucky retweeted

Last public Chart Request Tuesday 📈
Reply with a ticker and I'll chart as many as I can today!
Unfortunately the new X algo punishes me as a spam account for posting too many public charts at once. After this, chart requests are for subscribers only, so get yours in now.


CryptoBucky retweeted

Weighing in on @MLB and @MLBPA - seeing so many people get this all wrong.
“Players are making tons of money. Guys are making $30, $40 million a year…”
Yeah, like 6 guys in all of MLB are making $40 million a year. There’s an average of less than one guy per team making $30 million a year. There’s a huge concentration of wealth at the top of the MLBPA membership. The top 100 highest paid players account for about 49% of all player salaries. About 45% of players made less than $1 million in 2026. The median salary for 2026 was $1.4 million - so more than half the league is making less than $1.5 million a year.
And those are opening day roster figures, so when you add in the hundreds of minor league call-ups over the course of the season where those players get prorated shares of the $780k/yr league minimum, you end up with most of the league making less than $1 million a year.
This massive earnings disparity among its membership is a problem for MLBPA. And at the negotiating table, it’s a fatal one. Why? Because of how the voting works.
While every member of the union gets one vote at the team level - whether they make $40+ million or $780k - only 38 actual votes are cast when it comes to approving a CBA or not. There are 30 team player representatives, one elected player rep from each team, that cast a single vote reflecting the consensus of their clubhouse. Then there are 8 executive subcommittee members - the 8 player leaders elected to the MLBPA subcommittee - who each cast an individual vote.
This structure and the massive wage disparity among members mean the union can never win a prolonged work stoppage. The guys with big money can weather a lockout a lot easier than the pre-arbitration league minimum guys and minor leaguers who make up the majority of the union’s voters. (Scott Boras can say whatever he wants… he doesn’t speak for the MLB rank and file, and the MLB rank and file are not Boras clients.)
Owners will use this as a wedge. They know they can pair significantly increased minimum salaries with a cap & floor and after a few months of lockout, the lower earners will be ready to surrender. If you’re on $780k/yr but you haven’t had a check in 4-5 months and you’re looking at a deal that will double your pay and get you to arbitration and/or free agency a year sooner… lotta guys are going to vote to take that deal. In fact, more and more guys with every round of negotiations.
The MLBPA acts like it doesn’t already know this, but it does. This is a fight they literally will never win. And both sides know it. In fact, this is how the last CBA was passed - when the rank and file clubhouses effectively overruled union leadership and 26 of 30 teams voted, against all 8 executive subcommittee members, to approve the deal and it passed 26-12.
So with owners eventually “winning” any prolonged standoff anyways, the union needs to focus on a set of objectives that are achievable. Just because “greedy billionaire” victory is assured (and it IS assured) doesn’t mean the two sides don’t have mutual interests. They have a LOT of mutual interests. And a lot of these things can get done, and many can be genuine wins for the union.
#1 - A salary cap is inevitable. It works in other sports and has for years. It helps competitive balance - yes, we know the Brewers and Rays aren’t major market cubs blah blah blah - but the data across other sports prove it’s better over time. And, critically, many fans want it. That’s never been true in previous CBA environs for baseball, but it’s absolutely true now. Fans are sick and tired of the dodgers and their $3 billion payroll with deferred comp paid through the year 2079. They’re sick and tired of the top 4 teams spending more than the bottom 22 teams on free agency - which is what’s happened over the 2022-2026 CBA period. MLBPA needs to understand that a huge portion of the fan base is NOT on their side with regard to this issue of a salary cap. 🧵 1/2

