

Myntra | Ex. Flipkart | E-com Professional | Equity markets | Investor | Chartered Accountant |
Bangalore
Joined April 2014
- Tweets1.1K
- Following284
- Followers459
- Likes1.2K



#Sansera
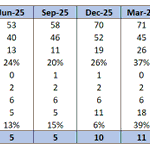
Sharing an earnings estimate for Q2 - Sansera
Revenue ₹1,062 cr (+29% YoY)
EBITDA ₹202 cr (+42%), margin ~19%
PAT ₹100 cr (+40% YoY, +14% QoQ)
The story is no longer just auto parts. 👇
Q1 set the tone: revenue +33% and a record non-auto quarter. Aerospace, defence and semiconductors (ADS) hit ₹145 cr, more than 3x YoY. That’s now ~15% of revenue, up from ~10% in FY26. These are 25–30% margin businesses, portfolio mix to aid margins. Mgmt has guided FY27 ADS growth of 75–80%.
The core auto business : ICE +21% and xEV/tech-agnostic +22% in Q1.
FY27 guidance is “high teens to ~20%” growth. At the current run-rate, FY27 sales would land near ₹4,300 cr (~+24%). (Room for a guidance upgrade)
What to watch in Q2:
ADS revenue above ₹155–160 cr = beat
Margin holding at 19%+ despite aluminium/labour inflation
Recovery of the ₹12.6 cr US tariff provision
Order book (₹5,750 cr) and semiconductor order timing
Any change to FY27 guidance
Future Growth : The bigger ADS step-up comes in FY28, when the hangar is running, a new ~1 lakh sq ft facility opens and the large semiconductor order starts in CY27.
Q2 is about proving the run-rate. FY28 is where the re-rating case lives.
Discl: Invested
Not investment advice. DYOR.

#AartiPharmalabs
Taking a stab at estimating the Q2 FY27 earnings for Aarti Pharmalabs. Expecting the PAT to be up +100% YoY at ~55-60 Cr with revenue growth of 30%. Results tmrw!

#LaurusLabs #Laurus #Q2FY27
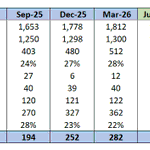
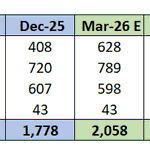
Sharing my estimates for upcoming Q2 FY27 earnings for Laurus labs. I sense the acceleration in earnings will continue and Laurus will post a qtr with 400 Cr+ PAT. Look at the non linearity from 194 Cr in Sept 25 to 400 Cr+ in Sep 26! If this happens, Laurus will be at ~8000+ Cr Rev & ~1600+ Cr PAT run rate!
PS: CDMO revenues are lumpy and Qtrly estimates are highly prone to errors. Results on Thur 29th Oct. Looking forward to the concall.

#Garware Hi tech Films - Stood out through the storm, earnings day was down 12%, closed flat by day end and the next day up 5%
Reminds of the heuristic model from Antifragile thinking - "What does not kill you makes you stronger"
@unseenvalue 🙏

#Laurus #Lauruslabs - Its yet another results day and a start to FY27. Sharing a directional view on what I expect Laurus to deliver this qtr.
This year will largely be a margin expansion story in H1 with EBITDA moving from 24% to 28%+ with a topline growth of 5-10%. This will lead to a PAT growth of a massive 50%+ even at the higher scale.
Things to watch out for - If the topline growth accelerates in H2, it can take the avg PAT / qtr to 300-350 Cr+ range (My sense is that it is highly possible in Q4FY27)
CDMO business should not be compared QoQ considering the lumpiness. Hoping for a steady qtr. Stock has run up a lot already. Not a buy sell reco.

#Sakar #Sakarhealthcare - Results Today!
Taking a stab to estimate the results for Sakar healthcare. It's a small company in the pharma oncology sector which looks interesting. Lot of capex done and now the utilization game leading to margin expansion is playing out. Important to see how this qtr goes
Expecting a PAT growth of 80-100% YoY on a conservative basis and a topline growth of ~30%. QoQ have taken slightly lower margins based on historical trends. Just an estimate, can be very off. Not a buy sell reco.

As expected, amazing set from Viyash!
#Viyash


#Laurus PAT at 279 cr vs my est of 273 cr. Pretty close. Let's see how the concall goes. Topline could have been higher tho.
#LaurusLabs #Q4FY26
Trying to take a stab at Laurus Labs Q4 earnings due on 30th April. Key metrics to watch
1. CDMO share % and growth outlook (~2000 Cr of CDMO Revenue for FY26 as guided by mgt)
2. Growth in Non ARV - Based on last qtr guidance it would be 2600 Cr (+- 200 Cr)
3. Gross Margins at 60%+ consistently
4. While Q4 PAT growth YoY will be subdued due to a 59 Cr one time gain on land sale last year, operating margins growth would be key
Revenue : For this to play out, Laurus would have to hit a topline of 2050-2100 Cr for the March Qtr (Atleast 20% Growth)
Revenue Breakup : CDMO will have to hit 600+ Cr Revenue (Refer Breakup).
Key Risks to watch out for:
1. CDMO revenue is extremely lumpy
2. Feb Export data showed 47% decline in export revenue (Hopefully this is just lumpiness and doesn't impact overall Q4 delivery)
Margins - Confident of Gross margins of 60%-61% based on the revenue mix and guidance from management in last con call. Based on the above, we can expect a PAT of ~250-300 Cr (Refer P&L breakup). This will be PAT growth YoY of ~17% (Optically due to one time gain of 59 Cr in base last year). However, underlying PAT growth would be a massive 44% normalized for it. These are conservative numbers in my view. However, FY26 PAT goes closer to 900 Cr !!!
Anything above 300 Cr PAT will be extremely good in my view. The stock has already run up in expectations and post results, i would expect it to consolidate post results.
Discl: Not SEBI registered. Only for learning purpose. No buy / sell reco. Invested personally.


Results today #Laurus! 🙂
#LaurusLabs #Q4FY26
Trying to take a stab at Laurus Labs Q4 earnings due on 30th April. Key metrics to watch
1. CDMO share % and growth outlook (~2000 Cr of CDMO Revenue for FY26 as guided by mgt)
2. Growth in Non ARV - Based on last qtr guidance it would be 2600 Cr (+- 200 Cr)
3. Gross Margins at 60%+ consistently
4. While Q4 PAT growth YoY will be subdued due to a 59 Cr one time gain on land sale last year, operating margins growth would be key
Revenue : For this to play out, Laurus would have to hit a topline of 2050-2100 Cr for the March Qtr (Atleast 20% Growth)
Revenue Breakup : CDMO will have to hit 600+ Cr Revenue (Refer Breakup).
Key Risks to watch out for:
1. CDMO revenue is extremely lumpy
2. Feb Export data showed 47% decline in export revenue (Hopefully this is just lumpiness and doesn't impact overall Q4 delivery)
Margins - Confident of Gross margins of 60%-61% based on the revenue mix and guidance from management in last con call. Based on the above, we can expect a PAT of ~250-300 Cr (Refer P&L breakup). This will be PAT growth YoY of ~17% (Optically due to one time gain of 59 Cr in base last year). However, underlying PAT growth would be a massive 44% normalized for it. These are conservative numbers in my view. However, FY26 PAT goes closer to 900 Cr !!!
Anything above 300 Cr PAT will be extremely good in my view. The stock has already run up in expectations and post results, i would expect it to consolidate post results.
Discl: Not SEBI registered. Only for learning purpose. No buy / sell reco. Invested personally.
#CNXPHARMA #PHARMA
The pharma index is setting up for a very good move it seems as we inch closer to the IND-US trade deal. Do check it out :)

Amazing Qtr from Laurus!!
As forecasted PAT in the range of 180-200 Cr and EBITDA between 400-410 Cr :)
#Laurus #lauruslabs #Q2FY26 Results today. Can we expect cdmo share to reach 38% with an overall PAT run rate of 180-200 cr
Let us see! Concall later at 5 pm! 🙂
#Laurus #lauruslabs #Q2FY26 Results today. Can we expect cdmo share to reach 38% with an overall PAT run rate of 180-200 cr
Let us see! Concall later at 5 pm! 🙂
#LaurusLabs #Q2FY26 #StocksToWatch
Taking a stab at Laurus labs Q2FY26 results due on 23rd Oct.
> Important to understand the Rev mix for Q2. Estimating CDMO growth to be strong at 100%+ YoY and 22% QoQ. This puts the management on track for 2000 Cr+ CDMO revenue.
Have assumed 0-10% growth for rest of the portfolio taking the overall growth to ~29% YoY
> Basis the sales mix and margin mix, have arrived at a possible EBITDA at ~400-410 Cr (Almost near Q4FY25). Remember Q4 is the biggest Qtr for CDMO and Laurus! The PAT increases to 180 Cr vs. 20 Cr last year ~up 9x YoY
This is a conservative estimate from my side. The management usually does not provide any guidance!
PS: Not a SEBI registered Analyst | Not a buy sell Reco | Do your own Due Diligence


#inoxwind #Q2FY26
Inox wind has been consolidating in a range for sometime now. Based on the last results / concalls, they are poised to execute 1200 MWt this year.
Usually the 1st half is 35% rev contribution and 65% is 2nd half. Margins have been conservatively assumed at 22%. Basis this, they can register a PAT of ~190 Cr in this qtr and a massive 800+ Cr for the entire year.
Q2FY26 can be a 100%+ PAT YoY & QoQ both! Keep a watch on this stock.
PS: They have accumulated losses as well which can be used to set off taxes, if they do that the PAT can be 1000 Cr+
Disc: Not a buy sell reco | Do your own analysis | Only for learning purposes

#LaurusLabs #Q2FY26 #StocksToWatch
Taking a stab at Laurus labs Q2FY26 results due on 23rd Oct.
> Important to understand the Rev mix for Q2. Estimating CDMO growth to be strong at 100%+ YoY and 22% QoQ. This puts the management on track for 2000 Cr+ CDMO revenue.
Have assumed 0-10% growth for rest of the portfolio taking the overall growth to ~29% YoY
> Basis the sales mix and margin mix, have arrived at a possible EBITDA at ~400-410 Cr (Almost near Q4FY25). Remember Q4 is the biggest Qtr for CDMO and Laurus! The PAT increases to 180 Cr vs. 20 Cr last year ~up 9x YoY
This is a conservative estimate from my side. The management usually does not provide any guidance!
PS: Not a SEBI registered Analyst | Not a buy sell Reco | Do your own Due Diligence