

Chief Market Strategist @WellingtonAltus. PhD Econ. Astute, observations and conclusions. Personal views. Not investment advice. Please do your own research.
Joined November 2019
- Tweets19.2K
- Following16
- Followers127K
- Likes16.9K




Pinned Tweet
Warsh Fails the First Test
Warsh has failed his first test: hiking into a negative growth shock. His mistake exposes a contentious thesis that will slowly become consensus: the bond market is no longer the smartest money in the room.
Hedge funds’ growing influence challenges the old conviction that credit markets and bond vigilantes deliver sober judgments about economic fundamentals. When short-term, leveraged players dominate, prices can reflect crowded trades and groupthink rather than sound economic analysis.
A Fed driven by those prices compounds the problem. Traders predict the Fed; the Fed follows their predictions. The hall of mirrors turns positioning into a policy signal and then mistakes that signal for independent judgment. Hiking into a negative growth shock is what happens when the central bank follows the crowd instead of assessing the economy.
This is not your grandfather’s bond market. The supposed smart money may now be the dumb money at the table and a Fed that follows it risks becoming the dumbest player of all.

Following the U.S. Federal Reserve’s decision to hike #interestrates, @DrJStrategy questions whether its economic strategy is enough to support the #AI-investment boom in his October #MarketInsights. #Investing ow.ly/OVPh50ZUsM1

Wall Street’s AI Whiplash
In 1998, Paul Krugman predicted that the internet’s economic impact would prove “no greater than the fax machine’s”. Wall Street should frame that quotation before declaring artificial intelligence a productivity disappointment.
The latest bearish assessment points to flat revenue per worker and profit margins across the S&P 493, excluding the Magnificent Seven, and declares “zero financial payoff” outside technology.
The observation deserves scrutiny. The verdict outruns the evidence. Revenue per employee is not real output per hour. Flat margins cannot establish what costs would have been without AI.
Meanwhile, the narrative swings from “AI will take every job, hide your children” to “AI is useless”. Add a few charts, generate some noise, rinse and repeat. Manufacturing certainty from contradictory narratives is what Wall Street does best.
Apparently, robots will never arrive, inference will never scale and businesses will never reorganise. Today’s deployment becomes tomorrow’s ceiling.
Companies must prepare data, integrate systems and adapt CPU-based workflows to exploit GPU-accelerated AI where appropriate. Not every workload requires conversion. But useful deployment requires organisational change, not merely another subscription.
Yes, adoption is a constraint. People must change habits and companies must change processes, as they did with computers and the internet. This is not profound. It describes technological diffusion, not technological failure.
Physical constraints matter too. The International Energy Agency expects data-centre electricity consumption to more than double by 2030. Compute capacity and power connections cannot materialise on demand.
None of this validates every investment. Projects will fail. Valuations will disappoint. Cheaper models may undermine suppliers while improving customers’ economics.
But declaring economic futility during an unfinished buildout is ambulance-chasing analysis.
The serious question is where AI creates value, at what cost and for whom.
Wall Street’s oscillation between apocalypse and irrelevance answers none of it. Neither do its charts.
🤖 Made with AI

AI’s financing shakeout is not an earnings collapse
This week’s earnings from Microsoft, Alphabet, Amazon, Vertiv, GE Vernova, ServiceNow and Intel will test whether AI spending fears are obscuring resilient demand and constrained capacity.
Fears that artificial intelligence spending will overwhelm technology earnings confuse marginal developers’ vulnerabilities with the economics of established businesses.
The distinction is financeability. An operator borrowing to finish a data centre faces a different challenge from a diversified platform with operating cash flow, powered facilities and paying customers.
Tightening credit can punish one without undermining the other.
If forecasts of another 800–1,000 US data centres materialise, competition for electricity, equipment and construction capacity will intensify.
But buildings are not compute. Winners must finance, power and connect their infrastructure.
This competition extends beyond commercial ambition. US-China rivalry makes computing capacity, advanced semiconductors and reliable electricity strategic assets.
That guarantees neither profits nor sensible valuations. It does make the buildout more durable than quarterly spending anxieties suggest.
Financing is evolving alongside demand. Corporate borrowing is being supplemented by lending against equipment, customer contracts and expected receipts. Securitisation could broaden funding further by pooling eligible loans or receivables for institutional investors.
These structures cannot manufacture electricity or rescue worthless contracts. They can, however, finance viable projects beyond developers’ balance-sheet limits. Weak operators restructure; useful assets move to stronger owners; investment becomes more selective.
That process could extend the cycle rather than end it. Staggered construction delays supply, while lower acquisition costs improve project economics.
Established operators with powered capacity can serve customers while competitors struggle to deliver. Suppliers need funded buyers, not universal developer survival. A failed operator does not automatically mean a lost shipment. Nor do cancelled proposals eliminate electricity constraints.
Investors should distinguish spending from returns. Capital expenditure reduces cash flow upfront; depreciation affects earnings over time. The test is whether assets earn above their costs.
Nuanced exposure is the strategy: favour financial durability, productive capacity and enforceable revenues. The weakest borrowers are not a proxy for the entire AI investment cycle.
bloomberg.com/news/articles/…

BC elects Conservative Government
Another election where Capitalism wins. Socialism loses.
Yes the West is moving back to the Right.

The win would be the first Conservative Party majority in British Columbia in 98 years and swing Canada’s third most populous province to the political right bloomberg.com/news/articles/…

James E. Thorne retweeted

Our CEO @adam3us joined @scarletfu and @JSeyff on @BloombergTV's Bloomberg Crypto to talk about where the industry goes next: security in the age of AI, Bitcoin's path to post-quantum signatures, and the steady build of institutional adoption.
This is well worth your time.👇

I spoke with @jvisserlabs this week to break down @chamath's claim that bitcoin is going to zero, the real quantum computing risk, the historic hedge fund unwind, and why AI is now smarter than all of us.
We also discuss using AI as a life coach, genetically modified war dogs, and why Eli Lilly ($LLY) could become the biggest company in America.
YouTube: youtu.be/huUoyFrZW08?si=WLzu…
Spotify: open.spotify.com/episode/68I…
Apple: podcasts.apple.com/us/podcas…
TIMESTAMPS:
0:00 - Intro
1:01 - Chamath says bitcoin is going to zero (is quantum a real threat?)
10:55 - Marc Andreessen on why people over 35 fear new technology
14:30 - The historic hedge fund unwind & what’s driving the AI sell-off
20:03 - AI is now smarter than you (using Grok to sell real estate)
23:57 - Top law schools are banning AI & what it means for your kids
28:48 - Active vs passive AI usage & running a company on AI agents
34:06 - How to use AI as a weekly life coach
39:53 - Building shared AI memory
43:28 - Warp Sciences, Palmer Luckey & genetically modified war dogs
46:21 - Why Eli Lilly will become the biggest company in America
Let’s listen to an expert on the claims that Bitcoin is going to zero. 👇

The green shoots are there. The US is escaping a long period of secular stagnation. 👇


The IMF Gets Growth Wrong
The IMF’s claim that financial repression, rather than growth, drove postwar debt reduction draws too sharp a distinction between two forces that worked together.
Cheap financing mattered. But so did the productive transformation that expanded the economies supporting those debts.
The IMF ignores the fear after WWII of slipping back into the era of the Great Depression. To escape, supply side policies help escape secular stagnation.
Postwar growth was not simply a burst of demand. Reconstruction, capital investment, technological diffusion and rising productivity expanded productive capacity, particularly in Western Europe.
Economies were producing more, not merely paying more for the same output. That distinction is fundamental to understanding how countries reduced their debt burdens.
The type of growth matters. Growth in real productive capital is the solution. This is what the IMF missed. Trump’s Hamiltonian solution does have historical support.
Financial repression lowered governments’ borrowing costs, partly at savers’ expense. But growth enlarged the income base against which debt was measured.
Suppressing interest rates and expanding productive capacity were complementary mechanisms, not competing explanations. An accounting exercise assigning a larger contribution to one does not make the other economically unimportant.
The IMF’s own research also complicates its headline: repression dominated Britain’s postwar debt reduction, while fiscal consolidation contributed most in the United States. There was no single universal formula.
The lesson is not that governments can escape debt simply by holding interest rates down. It is that affordable financing works alongside an expanding productive economy. The quality of growth matters.

How did advanced economies cut their debt roughly in half after WWII? In this Analytical Corner, Neil Shenai explains that the biggest driver wasn't growth or fiscal consolidation. It was financial repression. youtube.com/watch?v=EczVdPgJ…
Gulf oil flows already back above prewar levels (Kpler >24 mbd).
What’s left in the price is tanker rates (still 5-10x) and the geopolitical premium.
Those risk premia can evaporate overnight.
The more the Fed tightens into this now, the more they cut in 2027.


The pause that refreshes.
benzinga.com/markets/equitie…


James E. Thorne retweeted

An #AI pullback could keep the AI boom alive, says @DrJStrategy. Read more from @radhika_anilk in @Benzinga: benzinga.com/markets/equitie…

AI’s Pause That Refreshes
A natural, healthy correction in the AI space was needed. A short-term downturn in artificial-intelligence stocks could help prevent the AI boom from collapsing under its own weight. Lower valuations, tougher credit scrutiny and slower construction impose discipline, stretching investment over more years and reducing the inflationary pressure of a concentrated spending surge.
Meta illustrates the difference between investment appetite and execution. Its latest call pointed to an inability to deploy computing capacity as quickly as it wants. Yet it raised the floor of annual capital expenditure guidance from $130 billion to $135 billion, retaining a $145 billion ceiling. The constraint is deployment, not a retreat from investment.
Political resistance adds friction. Communities are challenging data centres over electricity, water and infrastructure costs. Politico reported that 157 US projects had been paused, severely delayed or cancelled since 2024. Those obstacles interrupt the rush to build everything at once.
Credit markets are enforcing greater selectivity. Hyperscaler credit spreads have widened despite relatively tight broader investment-grade spreads. Investors are demanding greater compensation for heavier borrowing, rising capital intensity and uncertain returns. Capital now requires a stronger business case.
This is the pause that refreshes: a cooling of the investment frenzy that allows AI-driven inflationary pressures to ease without extinguishing the underlying expansion. Spreading construction over more years reduces simultaneous demands on equipment, labour and electricity infrastructure. Suppliers gain time to expand. Power systems gain time to catch up.
A stock-market correction reinforces that adjustment, challenging speculative financing and forcing management teams to connect expenditure with revenues.
Falling share prices are not falling demand for computing power. Slower capex growth is not shrinking investment.
The market sees friction as a threat. The stronger interpretation is that restraint prevents excess, cools the inflationary impulse and gives the AI boom more time to run.
Trump and Carney: A Deal Is There to Be Made
Canada and Europe keep diagnosing Donald Trump as the problem. Their real problem is an economic model that assumes America will never change.
After World War II, Washington helped rebuild Western Europe. That was an investment in recovery, not a promise to underwrite allied prosperity forever.
At Bretton Woods, Keynes recognized the danger of persistent international imbalances. His proposed solution demanded adjustment from surplus countries and deficit countries alike. A durable trading system requires obligations on both sides.
Today’s reckoning extends beyond tariffs. Debt, strained living standards and fragile supply chains have undermined the old bargain. COVID exposed the danger of confusing cheap imports with economic security.
The America First era has begun.
Trump’s approach carries Hamiltonian echoes: use tariffs to raise revenue, encourage domestic production and strengthen national power.
America is pursuing reindustrialization and an escape from secular stagnation. Disputing his methods is not an excuse for denying the shift. Pax Americana is dead.
My base case remains: a deal between President Trump and Prime Minister Carney is there to be made, and will be achieved. Both are smart and pragmatic. Neither benefits from economic rupture. Preferred access to the US is a necessity for Canada. Full stop.
But Carney needs to stop putting lipstick on a pig. Repackaging Canada’s economic model will not repair it. He needs an aggressive supply-side plan built on tax cuts and deregulation, following Trump’s lead in prioritizing investment and production, and the reforming ambition of Brian Mulroney and Michael Wilson in the late 1980s.
Cut taxes. Slash regulatory barriers. Accelerate approvals. Build energy infrastructure. Give capital a reason to choose Canada. The Presidents plan is rooted in Hamilton’s America 1st strategy. Carney needs to follow Trumps lead.
“Elbows up” is a posture. Productive capacity is bargaining power.
Europe faces the same reckoning. Economic sovereignty requires competitive industries, not declarations of independence from Washington.
This is not about surrendering to Trump. It is about building the strength to negotiate with him.
A deal is achievable. But Canada must bring more than grievances to the table. And yes a recognition that there is no going back. This is business not personal, Canada needs to realize this. In my opinion, Carney does.
.@POTUS: "We're very close to a deal with Mexico... Canada is working very hard to make a deal with us — and I hate to say this, but we have all the cards in both of them."
Investors have to realize what happens when we put the Global Economy Onchain. 👇
What do the Medici’s and #blockchain have in common? Listen to @DrJStrategy and Eric Selvaggi of @ageswealth to find out:
youtube.com/shorts/KKNSsYHRo…

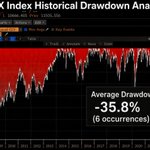
Drawdown of the SOX.
Given the historic nature of the AI buildout, the current drawdown in the Semiconductor index can easily be classified as normal, natural and healthy.
🤖 Made with AI

AI’s Pause That Refreshes
A natural, healthy correction in the AI space was needed. A short-term downturn in artificial-intelligence stocks could help prevent the AI boom from collapsing under its own weight. Lower valuations, tougher credit scrutiny and slower construction impose discipline, stretching investment over more years and reducing the inflationary pressure of a concentrated spending surge.
Meta illustrates the difference between investment appetite and execution. Its latest call pointed to an inability to deploy computing capacity as quickly as it wants. Yet it raised the floor of annual capital expenditure guidance from $130 billion to $135 billion, retaining a $145 billion ceiling. The constraint is deployment, not a retreat from investment.
Political resistance adds friction. Communities are challenging data centres over electricity, water and infrastructure costs. Politico reported that 157 US projects had been paused, severely delayed or cancelled since 2024. Those obstacles interrupt the rush to build everything at once.
Credit markets are enforcing greater selectivity. Hyperscaler credit spreads have widened despite relatively tight broader investment-grade spreads. Investors are demanding greater compensation for heavier borrowing, rising capital intensity and uncertain returns. Capital now requires a stronger business case.
This is the pause that refreshes: a cooling of the investment frenzy that allows AI-driven inflationary pressures to ease without extinguishing the underlying expansion. Spreading construction over more years reduces simultaneous demands on equipment, labour and electricity infrastructure. Suppliers gain time to expand. Power systems gain time to catch up.
A stock-market correction reinforces that adjustment, challenging speculative financing and forcing management teams to connect expenditure with revenues.
Falling share prices are not falling demand for computing power. Slower capex growth is not shrinking investment.
The market sees friction as a threat. The stronger interpretation is that restraint prevents excess, cools the inflationary impulse and gives the AI boom more time to run.
"A short-term downturn in artificial-intelligence stocks could help prevent the AI boom from collapsing under its own weight," said @DrJStrategy to @joe_stonor in the @WSJ. Read more: wsj.com/livecoverage/stock-m…
