

Founder, EPB Research. Business cycle research that helps investors separate economic noise from changes that materially alter recession and market risk.
Joined February 2015
- Tweets15.2K
- Following288
- Followers131K
- Likes13.3K


Eric Basmajian retweeted

New-home inventory stands at 8.5 months of supply, but completed new homes represent just two months of supply, compared with 5.8 months in early 2009.
Source: @EPBResearch

Eric Basmajian retweeted

The current economic situation has been confounding to me. Eric has been illuminating.


Eric Basmajian retweeted
Since late 2022, output per worker in the three most AI-intensive industries has grown 5% annually, more than double its historical pace and well above the 1.3% growth recorded across the rest of the private sector.
Source: @EPBResearch

Eric Basmajian retweeted
The stock market is valued at 34.2x corporate profits.
That’s a record, higher than the 33.4x peak in early 2000.
But valuations tell you very little about whether a recession is coming.
What they do tell you is how much damage a recession does...
1/
Eric Basmajian retweeted
Jobless Claims Look Exceptionally Strong. Why Doesn’t the Labor Market Feel That Way? open.substack.com/pub/epbres…

Eric Basmajian retweeted
Jobless claims are essentially at record lows.
But the labor market still feels weak.
Both can be true at the same time.
Here’s what's going on in the labor market.
1/
Eric Basmajian retweeted
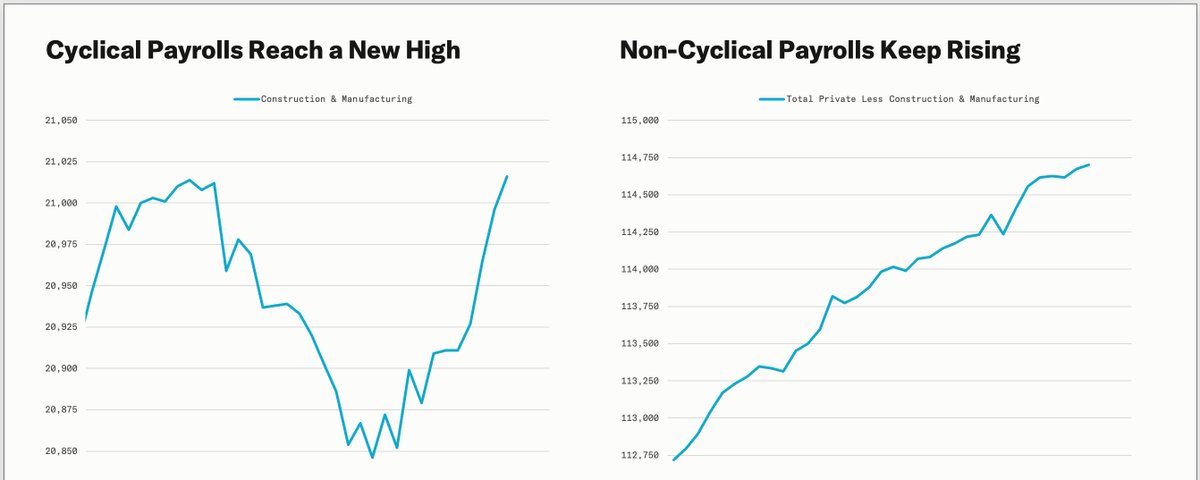
Cyclical payrolls—construction and manufacturing—have rebounded from their 2025 weakness to a new cycle high, signaling improving economic momentum despite weak headline payrolls.
Source: @EPBResearch epbresearch.com

Eric Basmajian retweeted

Again, I recommend checking Eric’s macro framework and observations. It offers a much more balanced perspective than the usual macro doom callers. Look at both sides, then form your own educated opinion.

Eric Basmajian retweeted
You can see our methodology: epbresearch.com/methodology

Eric Basmajian retweeted
Inflation usually ends a business cycle because it increases wage pressure and rate hikes drive up interest costs.
Both higher wages and higher interest expense compress profit margins and that leads to layoffs and a pullback in capex.
This cycle, despite 30%+ cumulative inflation and 500bps of rate hikes, both wages and interest expense fell as a share of corporate top-line, leading to an increase in profit margins, and thus, no end to the business cycle.

Eric Basmajian retweeted
With an increasing share of income coming from government transfer payments, slowing the economy/inflation will require an uncomfortable level of crowding out in the housing sector.

Eric Basmajian retweeted
This is the biggest problem in American politics.
For 50 years, corporate profits averaged roughly 7% of national income. Today, corporate profits account for more than 14%.
In today’s dollars, that difference is about $2 trillion per year.
There is no single explanation for why this shift occurred, and it certainly isn’t just one thing.
This isn’t all bad either. A larger corporate profit share helps explain why corporate earnings and asset prices have risen so strongly relative to the economy and to history, benefiting many people.
But the distributional effects of this shift are substantial, and they help explain why so many people feel the current system isn’t working for them.
This trend has been developing for nearly 30 years and spans political parties.

Eric Basmajian retweeted
The economy has accelerating cyclical momentum and low recession risk, so it can likely handle higher interest rates in the short term.
However, additional rate hikes will eventually collide with the ongoing downturn in housing and the longer-term constraint from high debt levels, which have reduced the real policy rate the economy can sustainably handle.
xitter.cf/EPBResearch/status/209…


Eric Basmajian retweeted
Housing has been weak for years, but the economy never entered recession.
The key is the tug-of-war inside the Cyclical Economy.
Housing is still contracting, while AI capex has offset much of that weakness.
In this video, I explain why and what would have to change for housing to become a broader recession problem:
youtu.be/5aDkYx5vv68
