

Graduated in economics/finance📈 Football ⚽️ coach of 45 little devils $OPEN long term investor 🚀
Joined April 2020
- Tweets1.2K
- Following140
- Followers452
- Likes2.4K



$OPEN My common sense says this administration is so pro AI and also wants to fix the broken housing market, that it's very unlikely that opendoor (which was designed to fix the market) faces any restrictions from the housing act. They are also in touch with the treasury about it

A few points I'd like to highlight regarding the past few days:
- I think Opendoor chose not to provide direct Contribution Margin (CM) guidance for Q4 because it is more difficult to forecast than revenue. Over the last quarters, CM has come in below management’s guidance. For Q3, the forecast was 4.0-4.5%, yet the company reported 3.3%. A similar situation occurred in Q1, management indicated it would be the strongest CM since Q2 2024, which implied a range of roughly 4.7-6.0%, but it ultimately came in at 4.4%.
That said, the company's AVG CM for the year currently stands at 4.5%, which is not bad. Even if Q4 brings that figure down and the annual average ends up closer to 3%, it would still be in line with 2025 levels while supporting a larger inventory base. The tighter the CM, the more inventory volume you need to transact.
- I believe last Friday's sharp selloff was driven by a combination of factors. In the risk section of the 10-Q, the company stated that it cannot guarantee it will not be classified as a "large institutional investor." Based on the legislation written in July, it arguably should not fall under that definition. However, the ambiguity introduced by the Treasury's draft guidance published in October has left the situation unclear, and the company itself acknowledged that it is closely monitoring how the rules are ultimately finalized.
I think retail investors are generally more comfortable with language such as "no assurance" than institutional investors and funds, even when the most likely outcome remains favorable for the company.
On top of that, stock-based compensation (SBC) continues to be a frequent point of criticism among both algorithms and investors discussing the company. Looking at the financials from the outside, it's easy to see why many people focus on the annual net loss figure, which is heavily impacted by SBC expenses. That is not to say the company is not currently losing money, but rather that the accounting presentation makes those losses appear significantly larger than the underlying economic reality.
- It's also worth remembering that the company has only been in rebuilding mode for about a year. That's a very short period of time to evaluate execution. I wouldn't even classify the major declines in the stock price as evidence of poor execution. The entire real estate sector has been under pressure due to macroeconomic conditions. This is a structural issue affecting the industry as a whole, not something unique to Opendoor.
$OPEN why to hide the negative Q4 contribution margin? Better to put out all negatives now.
Like this some folks who can't calculate will still hope for a positive margin in Q4 and get surprised badly. With a further decline of the stock price as a result...
$OPEN path to ANI profitability? Sounded more like fuck around and find out in the call than a real plan.
$OPEN We're at 2P now making 50% of sales, we have a lot of mortgages live, Doma is live. Other products and lots of improvements. So how the hell can contribution margin be negative in Q4? Would it have been -5% without those improvements? Why are we still SO bad.
@nejatian you gave us a picture at the Q1 call that you improved everything that much, that cohorts would do so well now, you told us that macro wouldn't matter anymore and now we're here and the numbers look exactly like the ones Carrie would've delivered in a market like this.

$OPEN CFO: "The higher marketing spend also reflects seasonality. Marketing in the fall and winter helps us acquire homes ahead of the spring and summer selling seasons when buyer demand is typically stronger."
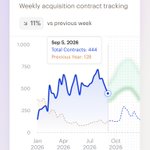
Where are those higher acq? 4x marketing for 450 contracts p week?
$OPEN another thing we learned: the great looking 7200 contracts in the accountable dashboard from June to August, turned out to be just 4800 real purchases. Implying a cancellation rate of 30%. That's why we list only 350 homes per week and it will even shrink in the next weeks.
$OPEN call much better than numbers and forecast. Probably the reason why it didn't crash yet. Let's just hope they can implement all that. As Kaz was a master of broken promises this year...
$OPEN oh my. Worse than I thought. Revenue about the same in Q4 as in Q3 (40% growth yoy, which is shit) and EBITDA loss of 70-85m in Q4 after 31m in Q3. This implies a negative contribution margin of -1%. Holy moly that's even worse than my worse fears. 💔
$OPEN caught probably the worst day to publish a bad earnings report...

$OPEN why are they clearing just 10% better than the market? It should be way more with all the software improvements and mortgage drops etc... Really disappointing! A down market is there for them to outperform relative to the market even more. But they don't. Why?

$OPEN Hovering around the bottom of the trend. Now it's the seasonal time where acquisitions should fly. But macro offsets seasonality plus operational improvements. I feel that ANI profitability won't hold in 2027 as a home takes 6 months to sell...


$OPEN Q4 rev we can track closely. But what about the margin? This will move the stock. I have a hard time to make a guess as the market got so much worse. We still have Kaz words that Q4 margin will be higher than Q3. But I really doubt it. What do you guys think we can expect?