

Stock Screener| OFF THE RADAR DIPS | Finding the next 10x | Vance Roasts included large cap pivots & high spec SMIDS moves. NFA. 📈🚀TN- Go Vols
Johnson City, TN
Joined November 2011
- Tweets12K
- Following2.2K
- Followers21.6K
- Likes199K



Pinned Tweet
The AI buildout is getting more complex, and $MTZ is right in the middle of it.
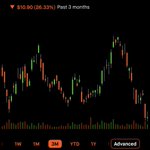
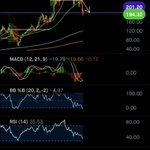
We’re close to officially bottoming. We’re sitting at 200 ma on top of volume shelf with Macd indicator close to flipping.
Don’t blink. Don’t miss.
As data centers demand more electricity, the infrastructure required to deliver it becomes increasingly important.
Q2 revenue hit $4.37B, up 23.4% YoY. Adjusted EBITDA climbed 39.8% to $384.2M, while adjusted EBITDA margin expanded from 7.8% to 8.8%. Earnings are growing faster than sales, signaling improving operating leverage.
Now look at the backlog.
$MTZ reported a record $21.39B in 18-month backlog, up 30% YoY.
Even more importantly, management reported a 1.2x book-to-bill ratio. That means new work is coming in faster than revenue is being recognized, helping replenish and expand future revenue visibility.
Now compare the competition.
$PWR (Quanta Services) reported $53.44B in total backlog, up approximately 49% YoY, alongside $33.55B in remaining performance obligations.
$EME (EMCOR) reported $17.14B in remaining performance obligations, up 43.9% YoY.
$MYRG (MYR Group) reported $3.16B in backlog, up 19.6% YoY.
$FIX (Comfort Systems USA) reported $17.82B in backlog, up substantially year over year, reflecting strong demand for mechanical and electrical infrastructure supporting data centers and other critical facilities.
Quanta leads in absolute backlog, while EMCOR and Comfort Systems are benefiting from robust electrical and mechanical infrastructure demand.
But $MTZ stands out with its disclosed 1.2x book-to-bill, 30% backlog growth, and 23.4% quarterly revenue growth.
Here’s where the valuation gets interesting.
Using approximate market caps of $13B for $MTZ, $82B for $PWR, $33B for $EME, $4B for $MYRG, and $40B for $FIX:
• $MTZ: $21.39B backlog ÷ $13B market cap = 1.65x
• $PWR: $53.44B backlog ÷ $82B market cap = 0.65x
• $EME: $17.14B contractual obligations ÷ $33B market cap = 0.52x
• $MYRG: $3.16B backlog ÷ $4B market cap = 0.79x
• $FIX: $17.82B backlog ÷ $40B market cap = 0.45x
That’s approximately 2.5x the backlog-to-market-cap ratio of $PWR, 3.2x $EME, 2.1x $MYRG, and 3.7x $FIX for $MTZ.
You’re paying roughly $0.61 in market cap for every $1 of MTZ’s reported backlog, versus $1.53 for PWR, $1.93 for EME, $1.27 for MYRG, and $2.25 for FIX.
These backlog measures aren’t perfectly comparable. They also differ in business mix, margins, contract duration, and revenue conversion. Still, the valuation gap is worth investigating.
Now look at the ramp.
Management’s FY2026 revenue guidance stands at approximately $18.2B, with $1.6B in adjusted EBITDA and $9.30 in adjusted EPS.
Clean Energy & Infrastructure backlog grew 58% YoY, making it a major contributor to the company’s record backlog.
Power Delivery also reached a record backlog, directly relevant to the grid expansion required by data centers and electrification.
MasTec also acquired The Superior Group, adding approximately 3,000 employees and expanding its electrical contracting capabilities in critical infrastructure, including data centers.
Here’s what stands out to me, fam: $21.39B in backlog, 30% YoY growth, a 1.2x book-to-bill ratio, expanding margins, and the highest backlog-to-market-cap ratio among these five companies.
That doesn’t automatically make $MTZ undervalued. Backlog isn’t guaranteed revenue or profit, and I’d still compare forward earnings, free cash flow, debt, and EV/EBITDA before drawing that conclusion.
This is one I’m keeping eyes on.
Rip salad pending. 🌱


$ALAB
This is probably the bottom.
Nice weekly 200 bounce would hit like crack lol 😂
Can I say that oh well? I’ve seen worse.

Who’s gonna come compete against us?
@Fsl_X
90 days.
10 stocks.
Bragging rights.
@Tape_Vector 🔥
@MohanadInv 🔥
@ant_trading1
@LeifInvests
@Investinc_Intel
@Blair519
Run it back gang?
Anybody else want the smoke and wants want to play?
OH MY BAD LOSE…
SEE If you can come out on top after I lead for 90% of the season and fall off a cliff for the third season in a row 😂
@StonkChris
@Mr_Derivatives
@CKCapitalxx
@NotA_Bull
@GrindeOptions
@hitborg
@steady_profits
@LazaroInvestor
@FinancePotentia
@Mariusz_Invest
@sovereignsense
@creillystocks
@timoassi
@BlackPantherCap
@LegacyPathCA
@TraderTammy1
@TehLamboX
@GAndersonTrades

Gvog1984 is back for Season 4.
@HunterAllen4 is back for Season 3.
That should tell you everything.
The people who’ve actually played FSL keep coming back.
Legal Services is already 5/12 full. 7 spots left.
If you think you can pick stocks, stop watching from the sidelines and come draft against people who keep showing up for more. 👀

$KLIC
Don’t blink. Don’t miss. Don’t sleep 😴
Kulicke & Soffa is a global leader in semiconductor assembly equipment, particularly ball and wedge wire bonding.
FY2025 revenue was approximately $654M, down from $706M in FY2024. The recovery has accelerated dramatically.
Q3 FY2026 revenue reached $330.4M, up 122.6% YoY and 36.2% sequentially. Gross margin reached 47.8%, and operating income swung from a $6.1M loss to $68.3M in the same quarter a year earlier.
Revenue for the first nine months of FY2026 reached $772.7M, up 62.1% YoY. Management guided for approximately $375M in Q4 revenue, plus or minus $20M.
That guidance implies approximately $1.15B in FY2026 revenue if achieved, representing a substantial recovery from the prior year’s downturn.
Management expects FY2026 Advanced Solutions revenue to exceed $100M, with TCB becoming the primary contributor. For FY2027, management is targeting $150–200M in TCB revenue.
KLIC is expanding its Singapore production facility to support approximately $400M in annual TCB system sales capacity.
The expansion is scheduled for completion in the second half of FY2027, with substantial capacity expected to become available during that period.
According to industry forecasts attributed to Yole Group, the global thermocompression bonding equipment market is projected to grow from approximately $542M in 2025 to $936M in 2030.
That’s roughly 11.6% annualized growth.
Hybrid-bonding equipment is projected to grow from approximately $152M to $397M over the same period, representing an even faster expansion rate.
Meanwhile, the broader backend semiconductor equipment market is forecast to increase from approximately $6.9B in 2025 to $9.2B in 2030.
Higher HBM stack counts, including 12-high and 16-high configurations, add manufacturing complexity. Chiplet architectures also require increasingly precise connections between different dies.
$SK hynix is a major HBM supplier. As HBM production expands and stacking requirements become more demanding, manufacturers need advanced assembly equipment.
$AMKR ( earnings today 💪)is a major outsourced semiconductor assembly and test provider. OSATs like Amkor package and test chips for semiconductor designers and manufacturers.
$AMAT is a much larger semiconductor equipment company with exposure to advanced packaging and other manufacturing processes.
Management reported semiconductor utilization above 95% in China and around 90% across broader memory and general semiconductor markets.
Customer purchase orders were extending into Q2 FY2027, providing longer visibility than KLIC typically sees.
Reported backlog has increased to approximately $245M from around $149M at the end of FY2025.
However, the trailing book-to-bill ratio remains around 0.79, meaning trailing bookings are still below trailing revenue. I want to see that ratio improve above 1.0 as the recovery continues.
Using the approximate market caps and trailing revenue figures in this analysis:
• $KLIC: $3.86B market cap / $950M revenue = approximately 4.1x sales.
• $ASMPT: $6.1B market cap / $2.1B revenue = approximately 2.9x sales.
• $BESI: $13.1B market cap / $990M revenue = approximately 13.2x sales.
KLIC trades at a substantial discount to BESI on a price-to-sales basis, while ASMPT trades at a lower multiple and generates more revenue.
But if TCB grows toward management’s $150–200M FY2027 target, KLIC’s business mix could change meaningfully.
KLIC reported approximately $516.6M in cash and short-term investments at the end of Q3 FY2026.
That provides financial flexibility to invest in capacity, research, and customer qualifications while the business recovers.
At approximately $73.71, KLIC has pulled back substantially from its $130+ highs.
Great volume shelf and 360 ma at 65$ if we flush more.
This is one I’m keeping eyes on.
Rip salad pending. 🌱

THE GAP FATHER retweeted

$QQQ is testing the yellow support box 🟨
Lose it and an extended wave 5 of C targets $674 (4.236 Fib), possibly $623 (6.85) to retest the prior ATH zone.
Still, I see this as consolidation above the prior ATH zone, so bullish continuation remains the more likely outcome.


$QQQ technical update: wave 4 looks complete.
The bears need to make at least one more low to complete the impulse wave from the ATH.
If the bulls can flip the 4H supertrend, they could target the $750 levels.

THE GAP FATHER retweeted
Long term investors.
Go take out a loan.
These dips don’t last forever.
Whenever industry’s leaders say it’s go time again we going. Market makers will become bulls again and we will rip
THE GAP FATHER retweeted

New Stock screener I have been working on, Its called Squeeze Play - stocks that are primed for a short squeeze.
Any on the list that you like ?
🤖 Made with AI

THE GAP FATHER retweeted
The AI buildout is getting more complex, and $MTZ is right in the middle of it.
We’re close to officially bottoming. We’re sitting at 200 ma on top of volume shelf with Macd indicator close to flipping.
Don’t blink. Don’t miss.
As data centers demand more electricity, the infrastructure required to deliver it becomes increasingly important.
Q2 revenue hit $4.37B, up 23.4% YoY. Adjusted EBITDA climbed 39.8% to $384.2M, while adjusted EBITDA margin expanded from 7.8% to 8.8%. Earnings are growing faster than sales, signaling improving operating leverage.
Now look at the backlog.
$MTZ reported a record $21.39B in 18-month backlog, up 30% YoY.
Even more importantly, management reported a 1.2x book-to-bill ratio. That means new work is coming in faster than revenue is being recognized, helping replenish and expand future revenue visibility.
Now compare the competition.
$PWR (Quanta Services) reported $53.44B in total backlog, up approximately 49% YoY, alongside $33.55B in remaining performance obligations.
$EME (EMCOR) reported $17.14B in remaining performance obligations, up 43.9% YoY.
$MYRG (MYR Group) reported $3.16B in backlog, up 19.6% YoY.
$FIX (Comfort Systems USA) reported $17.82B in backlog, up substantially year over year, reflecting strong demand for mechanical and electrical infrastructure supporting data centers and other critical facilities.
Quanta leads in absolute backlog, while EMCOR and Comfort Systems are benefiting from robust electrical and mechanical infrastructure demand.
But $MTZ stands out with its disclosed 1.2x book-to-bill, 30% backlog growth, and 23.4% quarterly revenue growth.
Here’s where the valuation gets interesting.
Using approximate market caps of $13B for $MTZ, $82B for $PWR, $33B for $EME, $4B for $MYRG, and $40B for $FIX:
• $MTZ: $21.39B backlog ÷ $13B market cap = 1.65x
• $PWR: $53.44B backlog ÷ $82B market cap = 0.65x
• $EME: $17.14B contractual obligations ÷ $33B market cap = 0.52x
• $MYRG: $3.16B backlog ÷ $4B market cap = 0.79x
• $FIX: $17.82B backlog ÷ $40B market cap = 0.45x
That’s approximately 2.5x the backlog-to-market-cap ratio of $PWR, 3.2x $EME, 2.1x $MYRG, and 3.7x $FIX for $MTZ.
You’re paying roughly $0.61 in market cap for every $1 of MTZ’s reported backlog, versus $1.53 for PWR, $1.93 for EME, $1.27 for MYRG, and $2.25 for FIX.
These backlog measures aren’t perfectly comparable. They also differ in business mix, margins, contract duration, and revenue conversion. Still, the valuation gap is worth investigating.
Now look at the ramp.
Management’s FY2026 revenue guidance stands at approximately $18.2B, with $1.6B in adjusted EBITDA and $9.30 in adjusted EPS.
Clean Energy & Infrastructure backlog grew 58% YoY, making it a major contributor to the company’s record backlog.
Power Delivery also reached a record backlog, directly relevant to the grid expansion required by data centers and electrification.
MasTec also acquired The Superior Group, adding approximately 3,000 employees and expanding its electrical contracting capabilities in critical infrastructure, including data centers.
Here’s what stands out to me, fam: $21.39B in backlog, 30% YoY growth, a 1.2x book-to-bill ratio, expanding margins, and the highest backlog-to-market-cap ratio among these five companies.
That doesn’t automatically make $MTZ undervalued. Backlog isn’t guaranteed revenue or profit, and I’d still compare forward earnings, free cash flow, debt, and EV/EBITDA before drawing that conclusion.
This is one I’m keeping eyes on.
Rip salad pending. 🌱
Long term investors.
Go take out a loan.
These dips don’t last forever.
Whenever industry’s leaders say it’s go time again we going. Market makers will become bulls again and we will rip
First actual Tip I’ve ever got from a stranger on here.
Much appreciated because Research is key gang.
Also follow @mainstinv he’s throwing out some solid ideas 💡 💪
Thank you to for the love! And support!


$SE
Who’s paying attention…
45.7B market cap for a company growing revenue 48% YoY across e-commerce, fintech, and gaming? 👀
Sea generated $7.79B in Q2 2026 revenue, up 48.1% YoY, with gross profit reaching $3.55B, up 47.3%.
Annual revenue accelerated from $13.06B in 2023 to $16.82B in 2024 and $22.94B in 2025.
🛒 Shopee
• Q2 revenue: $4.93B, +48.9%
• FY2025 GMV: $127.4B
• FY2025 orders: 13.9B
• AI-powered recommendations and advertising improve conversion and monetization.
💳 Monee
• Q2 revenue: $1.40B, +58.9%
• FY2025 revenue: $3.79B, +60.1%
• Loans receivable reached $8B at year-end 2025, versus $4.2B a year earlier.
🎮 Garena
• Q2 revenue: $746.6M, +33.5%
• FY2025 revenue: $2.41B, +26.1%
• Paying users increased from 50.5M in 2024 to 62.6M in 2025.
Sea is already integrating AI into recommendations, advertising, customer service, and seller tools.
In Q1 2026, AI chatbots handled around 80% of customer queries, while customer-service cost per contact fell approximately 30% YoY. Advertising revenue surged 80%.
AI could help Sea generate more transactions, monetize existing traffic more effectively, and improve operating leverage across its ecosystem.
Here’s where $SE gets interesting.
• $MELI
Q2 revenue and financial income grew 50% YoY. Market cap was approximately $91.8B, with a forward P/E around 42.9x
• $CPNG
Q2 revenue grew just 4% reported, or 10% in constant currency. Market cap was approximately $25B, with negative trailing earnings.
• $PDD
A major low-cost commerce competitor, with a market cap around $112.5B and a forward P/E around 6.9x.
Meanwhile, $SE traded around $74.63 with a $45.7B market cap, approximately 17.5x forward earnings, and a price-to-sales ratio around 1.65x.
$SE is sitting near the former $70–75 resistance zone, which could now act as support.
The stock is deeply beaten down from its previous highs. If the former resistance holds and momentum turns, a recovery could develop.
$SE combines 48% quarterly revenue growth, three expanding business segments, measurable AI adoption, and a forward earnings multiple below many high-growth peers.
At approximately $45.7B in market value, I think the market could be underappreciating the combined opportunity across Shopee, Monee, and Garena.
The key is whether earnings growth catches up with revenue and the chart confirms a reversal.
Gap Father is watching this one closely. Don’t blink.


There’s fast.
Then there’s 132 stops in 4 hours fast.
Time to go rescue again haha
No days off gang
Vroom Vroom 🏎️
More people need to be following my dawg in these market mysteries state.
He’s been all bear and been correct shoutout @Vance_Roberts5 as well.
To my dawg @Solsk to still have under 1k followers is criminal.
GET MY DAWG TO 1K BEFORE THE MARKET OPENS TONIGHT.
HE DESERVES THAT PLUS 10k MORE.

$QQQ $SPY The stock market is actually at a make or break level right now for tech. Many AI names are at the 200DMA or final local low with literally no support below (from the huge AI run up). Poorer quality AI names are already below 200D MA which will be more heavily shorted by HF algos so you can forget abt those names for awhile.
I am really really hoping we bounce from here. If it is a violent one, likely a dead cat. Watch volume and breadth to see if it is a sustainable recovery.
If it doesn't bounce, will close $IREN calls. That's my only position. Good luck to all.
$VRT
I hate to tell you but we ain’t crashing to 120$.
This is one of the top 5 buys in the market.
Sitting on top of previous resistance.
Bounce season soon missy elliot style, stay waiting for better prices or ape in to to the risk reward opportunity. 💪

Go follow my boy. @TheFrankzy
This is a great underated stock not many know about.
He constantly shares great ideas fam.
SLB is just the latest one.
Hidden data center plays yes please.

🚨 $SLB : AN UNEXPECTED AI WINNER? ❄️
The oilfield technology giant is expanding into AI data centers!
Q3 2026 results:
🟢 Data-center revenue: $230M
🟢 Growth: +76% YoY
🟢 Quarterly growth: +23%
🔩 Why it matters:
AI factories generate enormous heat. Cooling and modular infrastructure are essential to keep them running.
SLB is expanding into thermal management through its planned Kelvion acquisition.
⚠️ But there's a catch!
Data centers are still only ~2.4% of SLB's revenue, and project ramp-up costs pressured segment profitability.
Strong growth is exciting. Profitable growth matters more!
$BE
50 ma weekly bounce anyone?
Don’t miss. Don’t blink. Don’t cry when we’re back at 300$


Guess the stock Sunday 🤫
Very similar to $MTZ
Very slept on
Just dropped to Subscribers.
I’m looking at an infrastructure company with:
• Backlog nearly 2× its market cap
• A 1.4× organic book-to-bill
• Accelerating organic growth
• Expanding adjusted EBITDA
• Exposure to fiber, data centers and power infrastructure
And the chart is approaching a major technical level with momentum potentially starting to turn.
The market is still focused on the price action.
I’m focused on the backlog, earnings power and what the next few years could look like.
Sometimes the best setups happen when fundamentals keep improving while the chart is still trying to find a bottom.
Full research going to my community. 👀