

Building world’s 1st ₿itcoin & AI IR firm @OGAdvisors | Research @Finblueprint | @VillanovaU ‘16
👇Institutional-Level Research
Joined August 2021
- Tweets18.5K
- Following362
- Followers23.9K
- Likes25.2K




Danny Marques | Investing Informant retweeted
$CIFR has been considered "dead" money twice in the last 4 years. What's funny is that AFTER everyone dismissed the company and became uninterested, the forward returns were an 18x in 2022 and 15x most recently in 2025.
While the world screams AI is a bubble and that neoclouds won't survive, the infrastructure behind it is still being built and monetized
Technically, the stock is in a sweet spot between the 0.786 and 0.887 fib where I expect it to find a bottom. Notice how even amidst all this selling, price is still trading above the breakout that preceded it with no deviation or acceptance below the prior accumulation
This too shall pass


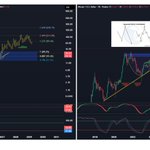
$IREN vs $CIFR have two very different but also similar technical structures. Both have endured substantial corrections amid the broader weakness in AI infrastructure, but an important distinction in where each sits relative to its long-term technical structure.
$IREN hit its macro 1.272 fib at $69 before this correction. A correction of this magnitude isn't particularly unusual, especially following the first test of an important macro extension.
$CIFR fell short of its 1.272 extension at $42 and has now retraced to its 0.887 fib which converges with a significant historical demand zone and the vicinity of its longer-term ascending trendline.
From a purely technical perspective, CIFR's is already testing, and marginally undercutting, an area of support that IREN has yet to revisit on a comparable basis.
For IREN, that equivalent 0.887 retracement sits near $19.40, roughly 30% below current levels, and coincides with the broader trendline structure I've drawn.
That doesn't mean IREN needs to trade there. But it illustrates why I see a more immediately identifiable technical risk/reward setup developing in CIFR.
Sentiment across AI infrastructure has deteriorated considerably, and we're seeing the kind of fear and volatility that historically accompanies important inflection points.
But the indicators I track aren't yet suggesting that the selling is conclusively over. Both of these have lost important monthly EMAs like the 21m EMA which in my experience ends a trend. IREN would need to reclaim $34 by month-end and CIFR $13. Until that happens, one needs to remain open to further weakness in months ahead, even if we experience a sharp relief rally.
And yet, when I consider what these businesses are building, their expanding contractual commitments, and the earnings potential emerging over the next 12-18 months, it's difficult not to be interested at these prices.
It reminds me of April 2025, when several names across the sector lost important technical levels, sentiment collapsed, and what appeared to be a breakdown ultimately developed into one of the more attractive entry opportunities of the cycle. I've followed this sector long enough to recognize that the greatest asymmetries come when the prevailing narrative becomes overwhelmingly negative and price begins discounting outcomes considerably worse than what the underlying fundamentals are showing.
It's not supposed to be comfortable. But I do think we're in an area where the longer-term risk/reward is becoming increasingly compelling, particularly for investors who can look beyond the next several months.
Just be disciplined in your accumulation, position sizing, and be patient.

Danny Marques | Investing Informant retweeted

call me crazy but I think the Anthropic S1 could be the neocloud bottom
this whole thing began when the market puked about Ant's Q3 run rate leak; their economics have now been demonstrated to be rock solid. GPUs including older vintages trading at ATHs if you actually look at the data. agentic driving record token use. think this entire drama is overdone.
Danny Marques | Investing Informant retweeted

Honestly, I couldn't care less about Brazilian politics.
But I find it interesting to note how my former college professors equate democracy with a victory for the left. In other words, if the left loses, it's not democracy.
Homeschool your children.
Danny Marques | Investing Informant retweeted

$clsk Sandersville is de-risked the infrastructure way: $2.276B of non-dilutive debt, fully funding a 20-year triple-net lease DIRECTLY backed by a high investment grade, leading global technology company.
No equity. No converts.
And on the balance sheet: ~13,500BTC, mined not bought, compounding while we build.
Certainty. Not speculation.


Danny Marques | Investing Informant retweeted

Everyone is running from neoclouds. I'm looking at the landlord.
The bear case on CoreWeave $CRWV and the rest is real. Billions in debt secured by GPUs that may be worth half as much in three years, bonds yielding near 16%, and a handful of customers holding up the whole thing.
But notice who carries that risk. The company that buys the chips.
$BGDE doesn't. It owns energized grid power, 169 MW across four sites with a path to 266 MW, and the tenant brings the GPUs. Its Hood County JV signed an LOI with Tensor IQ for 7,748 B300s at a site that's already live, with about $546M of potential power-lease revenue over 15 years.
In a cycle where everyone is short on power and long on debt, I'd rather own the plug than the chip. Management owns a big chunk of the company.
It's tiny, it still burns cash, and the LOI isn't binding yet. Nov 5 earnings will tell us a lot.
But if the neocloud shakeout happens (even in a less drastic way than the market is starting to price in), the survivors still need somewhere to plug in.
This is how I’m playing the AI buildout.
Danny Marques | Investing Informant retweeted

IREN - Almost to the spot where I've been calling for a bounce. No clue if we get it or not, it's just what it's done twice before. What IS different this time is that it's formed a not so clean head and shoulders. I really like clean setups but am continuing to do my best to provide my own play by play here. Currently, I believe we will bounce around $24.50, however, I'm afraid we are targeting the bubbled swing low longer term. If we were to reach that target, it would look like the major trendline was broken, just a heads up!

Danny Marques | Investing Informant retweeted

@cantonmeow made a great video recently about the importance of the 0.886 fib, especially when a stock pushes past the 1 multiple and doesn't extend all the way to the 1.618.
He may be right (once again), as $IREN is showing early signs of wanting to revisit that same fib at around $19.40.
It would be one more to add to the list.

Danny Marques | Investing Informant retweeted

Necessity is the mother of invention.
AI compute can't wait years for grid connections, so it's adapting to travel to the power faster than ever.
Compute is becoming mobile. Power isn't.
Having the power is the asset. $BGDE

NVIDIA $NVDA JUST INTRODUCED DSX POD, AI DATA CENTERS THAT SHIP IN CONTAINERS
Each one arrives with computing, cabling, power, and liquid cooling already installed, built around Nvidia's Vera Rubin systems. That cuts setup time at a ready site from 6 months to as little as 14 days.
Partners plan to deliver them worldwide in early 2027.
Jensen Huang: "An AI factory creates value when it starts producing tokens, not when construction is complete."
“With NVIDIA DSX POD, we’re bringing factory-built precision and speed to AI infrastructure construction — reducing deployment time from months to weeks so customers can scale capacity and bring revenue-generating production online faster.”

Danny Marques | Investing Informant retweeted

$NUAI has been hammered. High $7s after the Vistra PPA, now in the $2s.
I've talked about this name a lot, so I'm not going quiet now. I've made some bad calls before and I'll prob make more. I don't think this is one of them.
The co controls 493 acres in Odessa w/ a signed 20-yr PPA for up to 207MW from Vistra. LT the site has potential for up to 1.4GW. Power is still one of the biggest bottlenecks in AI infra, and I don't think the mkt appreciates what this asset could be worth w/ the right tenant.
Mgmt. has been substantially rebuilt w/ real experience in hyperscale DC development and financing.
But a PPA isn't a lease. And a lease isn't a finished, income producing DC.
The co still needs a tenant, construction financing on decent terms, permitting and ultimately delivery. Dilution is a real concern, particularly at these prices, and financing costs aren't getting easier. None of this is trivial.
At a mkt cap of c.$300M, I think the asymmetry is extraordinary if mgmt pulls this off. The opportunity hasn't deteriorated anywhere near as much as the price.
I added yesterday at $2.82. Position: 120,888 shares, plus long Jan '27 $7.50 calls.
Plenty of ppl here own this, some much higher. I won't tell you to hold, buy or sell. Make your own call.
If the tenant doesn't materialize, or the financing wrecks the economics for common SHs, my thesis changes.
Until then, I think the mkt has this one very wrong.
Danny Marques | Investing Informant retweeted
$NUAI | Understanding the technical structure and where we go from here.
A few observations, particularly the extraordinary selling pressure we've seen over the past month. But first, there's an important limitation worth acknowledging.
Unlike companies such as $GOOGL , $AMZN, or even $IREN , we don't have the benefit of decades of trading history to evaluate NUAI's long-term technical structure. With <2 years of meaningful price history, we have few reference points to work with. It simply means we need to be more measured in the conclusions we draw.
BUT from the price history we do have, the market has been communicating something fairly consistently. For much of the past year, $NUAI has traded within a broad range between approximately $3 and $6, repeatedly struggling to sustain advances beyond the 0.786 fib near $5.64.
I've highlighted the descending resistance line that has rejected price on multiple occasions. Post-PPA we briefly broke above that resistance, even registering a weekly close above it, but there was no sustained follow-through.
Instead, price reversed sharply and ultimately surrendered the entire breakout. This is why confirmation matters. A breakout isn't validated simply because price moves above resistance. You want to see buyers sustain that move, establish acceptance above the previous range, and ideally defend that level on a subsequent retest. We didn't get any of that.
And importantly, this happened despite positive fundamental developments at the company. Use this as a useful reminder that a bullish catalyst and bullish price action aren't necessarily the same thing. The market can acknowledge operational progress while simultaneously reducing the valuation it's willing to assign to that progress.
So where does that leave us today?
Following nearly a month of relentless selling, we're now seeing the first signs of potential stabilization around $3.06, corresponding to the 0.618 fib. This is an important technical area, particularly given the magnitude of the correction and the substantial increase in trading volume accompanying the decline.
But I wouldn't suggest the bottom has been confirmed. The broader blue-shaded region between approximately $2 and $3.50 represents an area of historical price activity where buyers have previously demonstrated interest. It's the region for accumulation.
Could we still revisit the mid-$2s, or even the 0.5 fib at $1.99? Possible. But I suspect a considerable amount of fear has already been reflected in the stock price.
The momentum indicators I track haven't yet demonstrated the kind of bullish divergence or sustained recovery that would give me greater confidence the corrective process is complete. And after a decline of this magnitude, some additional consolidation wouldn't surprise me.
I overlaid a fractal from $IREN's 2025 correction to illustrate one possible recovery trajectory. It's not a forecast, nor am I suggesting NUAI must replicate that move. It's simply a useful illustration of how a stock can experience a sharp breakdown, retest a historical demand region, and eventually recover into its former trading range.
For now, I'd be watching three areas:
- $3.06: Immediate support and the first area where I'd want to see stabilization.
- $2–$2.50: A deeper demand region if the corrective process extends.
- $5.64: A resistance level that needs to be reclaimed and sustained to improve the broader technical outlook. Until this is convincingly reclaimed, remain open to further consolidation and volatility.
Now, here's where I think the longer-term perspective becomes important.
NUAI has made meaningful progress building its development platform, including its 207 MW power agreement at TCDC, securing the associated letter of credit, and assembling a team with substantial hyperscale infrastructure experience.
But the equity is still being valued against significant commercial, financing, and execution milestones that remain ahead.
I believe the opportunity for companies controlling strategically located power and capable of developing AI infrastructure remains substantial. But the market is currently placing a much greater emphasis on how these projects will ultimately be commercialized and financed. A strong LT thesis doesn't eliminate near-term technical risk, just as a deteriorating technical structure doesn't automatically invalidate the underlying business opportunity.
For investors approaching the opportunity with a multiyear horizon, you should be increasingly interested in the risk/reward developing at $3.
But I'm also comfortable allowing the bottoming process to unfold. There's no requirement that the stock immediately recover simply because it has corrected substantially.
The objective isn't to predict a bottoms but to recognize where a potentially attractive opportunity is developing, understand what could invalidate that thesis, and position accordingly.


Danny Marques | Investing Informant retweeted

Everyone wants to be a deep value investor until it’s time to invest in some deep value
Danny Marques | Investing Informant retweeted

A lot of questions this week on funding, so here's how a GPU typically gets funded at $IREN.
First, the customer signs a multi-year take-or-pay contract and agrees to a prepayment. On our recent 3-year contracts, prepayments have been 45% to 55% of the associated GPU capex.
Second, financing is committed, secured by the contracted GPUs. On the Microsoft contract we secured an A-rated facility at around 6%, which together with prepayments covers 96% of GPU capex. More recently, for a non-investment grade counterparty at Mackenzie, we secured financing at 9% fixed, which together with prepayments covers more than the full cost of the GPUs.
That's the GPU side. The data centers are a separate, long-term asset base, and we own the ones our GPUs run in. Construction has been funded from cash to date, with no debt against these multi-billion dollar assets. As they come online with contracted customers, they can support financing in their own right.
The processes behind the next facilities are continuing, and new paper will cost what the market charges. With GPU paybacks of around two years on our recent 3-year contracts, a wider spread barely moves the economics.
There's more customer demand than we can build for. As we noted at our recent earnings, 2026 is largely sold out, recent 3-year contracts are at more than double the prior year's pricing, and demand for anything we can bring online in 2027 covers it several times over, with prepayments a focus in every negotiation. Conversations on 2028 capacity are already underway.
Meanwhile announced capacity keeps slipping across the industry, which is the point: signing deals isn't the bottleneck in this market, bringing GPUs online is, and that's our focus.
Danny Marques | Investing Informant retweeted

#Bitcoin: Since 2016 we’ve only seen acceptance above the 30w/Cloud from the underside following re-accumulation on 4 occasions
We are now on the 5th….the other 4 paths from same technical point are illustrated

Danny Marques | Investing Informant retweeted

I still see people looking at day to day price action and trying to find out or create narrative behind the move to justify price action with fundamentals.
I still think these people are doing it backwards.
Danny Marques | Investing Informant retweeted

A chart that keeps me wondering if we need more ranging to go until alts are really prime for expansion is solana:So11111111111111111111111111111111111111112
If this strong supply is too much to overcome, then we reject and form a Wyckoff accumulation range with an LPS first (higher macro low)
And since it moved with alt indexes very well, it would also mean that alts stall in the same consolidation-like structure for a few more months to prep for 2027.
But this would be an amazing base to jump from for a strong impulse after.


I just really like $SOL here. Play this out and it has an INSANE gains in front for the next 2-ish years once it breaks out. If so, Can't wait for 2027!
Needless to say most alts are in the same basket.
Ranging =/= Weakness ‼️

Danny Marques | Investing Informant retweeted
$NUAI vs $IREN
The April 2025 fractal playing out to a T is pretty wild. But, the silver lining is that you get to buy a future multi-billion power developer for sub $400M
Technical analysis isn't supposed to be absolute but it can certainly allow you to see things fundamentals and the market on its own won't show you

$NUAI vs $IREN
Technical analysis is pattern recognition and allows one to look at all possible scenarios objectively w/o any bias towards any company, and just assessing the structure
I just looked at NUAI vs IREN to see if there were any similarities outside the massive impulse NUAI had late last summer/fall, the current structure is very similar to where IREN was in early 2025. The only difference is that given the tariff scare of last year IREN, and all other HPC/AI names "broke structure" meaning lost that trendline that was holding up for a few months with IREN re-testing the liquidity around mid $5s and then from there putting a 10x move to the 1.272 fib (important macro target level and one of the main reasons I personally believe it hasn't been able to break past $69)
In the case of some weird macro event that brings more volatility than we've currently seen, this should provide a view of what could happen in the worst case for NUAI in breaking the structure like IREN did. This doesn't have to happen, but it could just like no one thought IREN would go back to $5.
Anyway, I took that exact IREN fractal and applied it to NUAI as it's actually pretty uncanny. Some of y'all might balk at it, but something that I found interesting.
Regardless of what happens though the 1.272 fib target for NUAI is $33 which is where I'd expect it to head to over the 12-18 months

Danny Marques | Investing Informant retweeted

I spend a lot of time in the private markets, and the recent madness around financing challenges for DCs and neoclouds is pure FUD.
Yes, there is a shortage of traditional lender capital, but many pristine balance sheets in Silicon Valley, elsewhere, and across sectors have strong incentives to participate and fill that void.
AI is a moment when everything as we knew it changes.
Every single business…
in every single sector…
across every P&L line item…
will be profoundly impacted…
by this new god-like capability.
Every balance sheet in the world will contribute to AI development over time, and AI datacenters benefit because of their lock on power.
So why the debt scare? The datacenter/neocloud market is being crowded out by public sector debt issuance. If you agree with my earlier proclamation about AI affecting everything, private sector enterprises will contribute their balance sheets to AI development in two ways:
1) As the next source of debt/equity financing for DC developers and compute providers (probably not voluntarily), thereby lowering DC cost of capital;
and/or
2) By consuming tokens far faster than supply, raising $/GPUhr for compute and lease rates for DCs.
Path 1, lowing the cost of capital, seems logical, but massive public sector debt woes will keep financing costs elevated for a long time, making path 2 equally a necessity:
Higher debt/equity rates are offset by higher DC lease rates.
Higher lease rates are offset by higher $/GPUhr or a larger share of those $/GPUhr economics.
In an expanding TAM, prices rise quickly as demand outstrips supply. If AI’s TAM is expanding, $/GPUhr should be high, right? Sort of. It’s a tale of two cities: the haves and the have-nots.
Most of today’s AI economics (outside GPU makers) go to the incumbents: hyperscalers. They have large, highly creditworthy balance sheets from decades of capital-light models, diverse and growing revenue, and strong margins, serving the world’s largest and successful enterprises. Hyperscalers are the most trusted providers of enterprise-grade/scale compute—an expertise built over decades.
Neoclouds, on the other hand, must build a balance sheet from scratch with creative financing, only to serve the hyperscalers’ leftover TAM, and all for a new commodity (compute tokens) whose value is not yet established.
No wonder neoclouds live on a razor’s edge: supernormal revenue growth fueled by equal or greater capex, hoping commodity prices soon make investors very happy. I call it “a dream business (to short).”
But wait—there’s more.
In a nascent, rapidly evolving commodity market, large pricing inefficiencies arise from swings between oversupply - think $CRWV in 2024–2025 bringing large compute online for what was only a handful of large buyers at the time - and undersupply when many buyers enter at (what feels like) all at once (Jevons’ paradox accelerating). Buyers and sellers are constantly left wonder g who holds the negotiating power in these conversations.
Things eventually stabilize, with better matching of land, power, talent, construction, procurement, GPUs, compute, financing, buyers/sellers of stabilized assets, used GPUs, and more.
Then $/GPUhr accelerates (as long as TAM grows). The most recent compute pricing charts suggest we might be there now.
If so, neoclouds are here to stay. The strong ones will grow fast; the weak get acquired and their old contracts renegotiated to much higher current rates.
A much healthier ecosystem overall.
But remember this:
Be it the hyperscalers of the neoclouds, the DC developer always makes bank!
$NUAI $IREN
Danny Marques | Investing Informant retweeted
3 of my highest conviction holdings, each exposed to what I think will be among the biggest growth opportunities of the next decade.
Intelligence becoming abundant. Warfare becoming autonomous. Connectivity from space.
$IREN - My favorite name in the entire AI trade. Landlord, Power, DCs, GPU cloud and a growing software layer. Contracts w/ $MSFT, $NVDA, @AnthropicAI and other tier 1 customers. The contracted rev ramp is enormous and I think the market is badly underpricing both the existing business and what the platform can become. I see substantial upside to FMV from here. The scale of compute needed over the next decade is hard to comprehend and very few cos are positioned to deliver it like $IREN from business and r/r POV.
$ONDS - Closest thing I've found to a 1 of 1 autonomous defense platform. Drones, counter-UAS, loitering munitions, ground robotics, stratospheric ISR and the software tying it all together. $PLTR partnerships, $1bn+ cash and rev growing at an insane rate. I think the valuation is completely disconnected from the opportunity and the rev trajectory ahead. Autonomous warfare is going to be enormous and I believe $ONDS is worth substantially more than the market is giving it credit for.
$ASTS - D2D cellular from space. Partnerships w/ AT&T, Verizon, Vodafone etc. Ordinary phones connecting directly to satellites. This one's harder to value bc so much depends on launch cadence, execution, competition from $SPCX and the eventual economics of the network. It's much more of a venture bet than the other 2. But at $40 I think the asymmetry is incredible if they can pull it off.
What I like is that the underlying bets are very different. $IREN needs to finance and execute the buildout. $ONDS needs to win contracts and scale across defense programs. $ASTS needs to launch and commercialize its network.
Obvs all 3 can get hammered together when the market turns on high beta. We've seen that plenty.
But I don't own these just bc I think their industries will change the world. I own them bc I think the upside relative to what I'm paying today is enormous.
Particularly $IREN and $ONDS, where I think the market is massively underestimating the rev and earnings these cos can generate over the coming yrs, and the valuations that would justify.