


Ben gravel retweeted

JUST IN --
Follower reached out to me with this video of a man PUNCHING a woman to the ground "in the Ottawa/Gatineau area (Old Hull) this weekend"
No other information is known to me.
If you know this man, contact Gatineau Police.
Ben gravel retweeted

Dear Democrats,
I'll be voting Republican in the midterm elections because of your unwillingness to support the crypto industry.
Ethereum and the broader crypto market aren't about money laundering or scams. This is neutral technology that will accelerate humanity's progress and create opportunity for people everywhere not just in America.
The United States sets the standard the world looks to.
It's time to act like it.
Pass the Clarity Act


Ben gravel retweeted

GLXY is up 9%, and if you feel like you already missed the train, you're not even close
The market still treats Galaxy like a crypto proxy. It's not. This is a contracted AI power infrastructure company with a crypto kicker on top
Galaxy has over 800MW of data center capacity with CoreWeave as its anchor tenant across Helios. These are real, locked-in cash flows worth $1B+ per year. And a second major tenant announcement is expected in the next five weeks
But the data centers are only half the story (though it is the bigger one)
The crypto business is shipping relentlessly. Lending, borrowing, staking, trading, asset management, you name it. This is silently growing.
And if you believe crypto prices improve from here at any point, that's ANOTHER massive tailwind for a company already scaling at these levels.
Galaxy doesn't need a crypto bull market to work, but if one shows up, this stock gets repriced significantly higher
The real risk is execution on Phase II and Phase III buildout and securing that second tenant (that's not a real risk lol). But Galaxy has been hitting milestones, and these power assets are real physical infrastructure, not vaporware
My average cost is around $21. My model puts the base case above $50 and the bull case near $65. Even the bear case gets you to $35 (still above the current price)
You can still jump on the train (at a bargain).
Follow me @m0xt_ for more analysis and track my real-time moves on Milk Road PRO (link in bio)

GLXY is my largest position. I think it hits $50 within 12 months.
I built a full sum-of-the-parts (SOTP) model across three scenarios: bear $34, base $50, bull $66. Every assumption is below so you can stress test it yourself.
The stock trades at $24. Here's why I think the market is wrong.
Helios Phase I+II (393MW contracted)
I value this segment at $15.1B in the bear case and $19.2B in the bull case. These are enterprise values, meaning what this business would be worth as a standalone company before subtracting debt.
Tenants signed (CoreWeave), power secured, revenue locked on 15-year contracts. I value this at a multiple of its annual EBITDA (earnings before interest, taxes, depreciation, and amortization, essentially the cash profit the business generates each year). I use 22x in the bear (multiple compression from higher rates), 25x in the base (current peer range for contracted AI infrastructure like CoreWeave and Applied Digital), and 28x in the bull (AI demand premium, rate cuts). In other words, in the base case I'm saying this business is worth 25 times its annual cash profit. The cash flows don't change across scenarios because they're contracted. The multiple the market assigns to them does.
Phase III (133MW under construction)
Valued at $3.3B (bear) to $6.3B (bull). Same approach: annual EBITDA times a multiple, but with a wider range because this isn't generating cash yet. I use 14x in the bear (construction delays, cost overruns, pre-revenue assets get punished hardest in downturns), 20x in the base (on-track construction, reasonable discount to operating peers), and 27x in the bull (delivered on time, multiple nearly converges with Phase I+II as risk disappears).
Pipeline (Helios + Merlin Ranch)
Valued at $3.0B (bear) to $11.0B (bull). This is future buildout optionality. Construction hasn't started and won't until Phase III is done. But Galaxy owns permitted, grid-connected sites where new power interconnections take 3-5 years to secure. That land and those permits have real value today even before a shovel hits the ground.
- Bear: $3.0B
Development rights value plus modest buildout probability.
- Base: $6.5B
Majority buildout over 3-5 years, second tenant on similar terms.
- Bull: $11B
Full buildout, strong demand. Still a 50% discount to what the pipeline would be worth fully built and contracted.
Over a 12-month horizon, Phase III construction progress and the second tenant announcement are the primary catalysts that close the gap to fair value.
Digital Asset Operations
Valued at $0.3B (bear) to $4.0B (bull). Galaxy has built the most complete institutional crypto platform on a public exchange: $5B in assets under management, 1,700+ counterparties, full-service OTC trading, derivatives, structured products, lending, and advisory.
- Bear: $0.3B
Liquidation value in a crypto winter.
- Base: $2.0B
About 6x net revenue in a typical year for a healthy crypto market.
- Bull: $4.0B
Peak cycle volumes and AUM growth.
Crypto Portfolio
Valued at $0.8B (bear) to $3.0B (bull). Galaxy holds $1.3B in digital assets today, primarily BTC and ETH plus venture positions.
Bear: $0.8B
About 40% drawdown from current, venture marks compress.
- Base: $1.75B
Continued cycle, BTC toward $120-$130K.
Only 35% appreciation from current marks.
Bull: $3.0B
Full cycle plays out, venture positions reprice.
What I subtract: Project Debt + Net Treasury
I add up all the segment values above, then subtract what Galaxy owes. Project debt is non-recourse (meaning it's tied to the data center assets, not Galaxy as a company): $5.5B for Phase I-III. Pipeline debt scales with buildout ($0 bear, $4B base, $9B bull). Net treasury after corporate debt and cash: negative $2.3B
Dilution: 10% bear, 5% base, 3% bull
Galaxy has diluted shareholders aggressively in the past, nearly doubling share count since 2021. In the bear, I assume they tap equity markets again. In the bull, strong cash generation limits the need. I divide the total equity value by the diluted share count to get the per-share price target.
Here's the base case math all the way through: $17.1B + $4.7B + $6.5B + $2.0B + $1.75B = $32.05B in total segment value.
Subtract $5.5B Phase I-III debt, $4.0B pipeline debt, and $2.3B net treasury.
That leaves about $20.3B in equity value. Divide by diluted shares after 5% dilution and you get $50/share.
After dilution: bear $34, base $50, bull $66.
Here's what's wild. Helios Phase I+II contracted value alone, after subtracting all project debt and treasury, covers most of the current stock price.
At $24, you're paying almost nothing for Phase III under construction, the entire pipeline, an institutional crypto platform with $5B AUM, and $1.3B in digital assets.
The market prices Galaxy as a crypto proxy. The SOTP says it's contracted power infrastructure with crypto upside attached for free.
The next catalyst: Galaxy is expected to announce a second contracted tenant this summer. If the terms match CoreWeave's, this model gets repriced overnight.
I share all my positions and thesis updates in real-time at Milk Road PRO. You can join today at 33% discount (link in bio).

Ben gravel retweeted

Our first $SLNH group chat has been full for almost a month.
I opened up a second group chat. Click the link to join!
teapawt.net/i/chat/group_join/g207…

Ben gravel retweeted
Galaxy is a $50+ stock. That's more than double from here, and most of the upside is driven by contracted revenue, not speculation. Here is why
In the last 90 days, Galaxy has quietly become one of the most interesting infrastructure stories in the market (AI and crypto), and nobody is paying attention
Here's what's happened
Galaxy just delivered Phase I of Helios, their massive AI data center in West Texas. 133 megawatts of power to CoreWeave, on time and on budget
This isn't speculative. CoreWeave signed 15-year leases across 526 MW and the full buildout is expected to generate over $1 billion in annual revenue
Phase II is already under construction with delivery expected first half of 2027. The site has 1.63 gigawatts of approved capacity with room to scale to 3.6 GW
Galaxy started recognizing data center revenue in April 2026 (wait for Q2 earnings) when the first data hall went live. Helios is no longer a promise, it's on the income statement
Novogratz said that conversations with the second tenant for the remaining 830 MW are active, and he expects to announce the next tenant by end of summer
That's just the AI infrastructure side
On crypto, the execution has been relentless
Galaxy has $9 billion in assets on platform, a $1.4 billion average loan book, and 1,600+ institutional trading counterparties. This is one of the largest digital asset platforms in the world and it's still scaling
BlackRock picked Galaxy as a validator for their Staked Ethereum ETF. They got a New York BitLicense (one of the hardest crypto licenses to obtain) for institutional trading and custody. They launched institutional onchain yield vaults, prediction markets trading, and a new product called Galaxy Curator for institutional onchain access. GalaxyOne is live as a retail platform with crypto, stocks, and up to 8% yields for accredited investors
The CFO said just three and a half weeks into Q2 that the digital asset business was already tracking exceptionally well, signaling crypto EBITDA could come in around $90M this quarter. Still very early and preliminary, but layer in another $50M (90% margins) from the AI data center business now generating revenue, and you're looking at $135M in quarterly EBITDA
Annualize that and it's $540M a year from a company with an $8.8B market cap. That kind of earnings power would force a quick rerating
And they just got added to the Russell 1000 Index (not the 3000, the 1000), which means passive fund buying at scale
The average analyst price target across 16 analysts is $41, implying roughly 80% upside from here
My base case is $50+ in the next 12 months. This is your chance to get this company at a discount. I don't think it will last long
Follow me @m0xt_ for more analysis and track my real-time moves on Milk Road PRO (link in bio)
GLXY is my largest position. I think it hits $50 within 12 months.
I built a full sum-of-the-parts (SOTP) model across three scenarios: bear $34, base $50, bull $66. Every assumption is below so you can stress test it yourself.
The stock trades at $24. Here's why I think the market is wrong.
Helios Phase I+II (393MW contracted)
I value this segment at $15.1B in the bear case and $19.2B in the bull case. These are enterprise values, meaning what this business would be worth as a standalone company before subtracting debt.
Tenants signed (CoreWeave), power secured, revenue locked on 15-year contracts. I value this at a multiple of its annual EBITDA (earnings before interest, taxes, depreciation, and amortization, essentially the cash profit the business generates each year). I use 22x in the bear (multiple compression from higher rates), 25x in the base (current peer range for contracted AI infrastructure like CoreWeave and Applied Digital), and 28x in the bull (AI demand premium, rate cuts). In other words, in the base case I'm saying this business is worth 25 times its annual cash profit. The cash flows don't change across scenarios because they're contracted. The multiple the market assigns to them does.
Phase III (133MW under construction)
Valued at $3.3B (bear) to $6.3B (bull). Same approach: annual EBITDA times a multiple, but with a wider range because this isn't generating cash yet. I use 14x in the bear (construction delays, cost overruns, pre-revenue assets get punished hardest in downturns), 20x in the base (on-track construction, reasonable discount to operating peers), and 27x in the bull (delivered on time, multiple nearly converges with Phase I+II as risk disappears).
Pipeline (Helios + Merlin Ranch)
Valued at $3.0B (bear) to $11.0B (bull). This is future buildout optionality. Construction hasn't started and won't until Phase III is done. But Galaxy owns permitted, grid-connected sites where new power interconnections take 3-5 years to secure. That land and those permits have real value today even before a shovel hits the ground.
- Bear: $3.0B
Development rights value plus modest buildout probability.
- Base: $6.5B
Majority buildout over 3-5 years, second tenant on similar terms.
- Bull: $11B
Full buildout, strong demand. Still a 50% discount to what the pipeline would be worth fully built and contracted.
Over a 12-month horizon, Phase III construction progress and the second tenant announcement are the primary catalysts that close the gap to fair value.
Digital Asset Operations
Valued at $0.3B (bear) to $4.0B (bull). Galaxy has built the most complete institutional crypto platform on a public exchange: $5B in assets under management, 1,700+ counterparties, full-service OTC trading, derivatives, structured products, lending, and advisory.
- Bear: $0.3B
Liquidation value in a crypto winter.
- Base: $2.0B
About 6x net revenue in a typical year for a healthy crypto market.
- Bull: $4.0B
Peak cycle volumes and AUM growth.
Crypto Portfolio
Valued at $0.8B (bear) to $3.0B (bull). Galaxy holds $1.3B in digital assets today, primarily BTC and ETH plus venture positions.
Bear: $0.8B
About 40% drawdown from current, venture marks compress.
- Base: $1.75B
Continued cycle, BTC toward $120-$130K.
Only 35% appreciation from current marks.
Bull: $3.0B
Full cycle plays out, venture positions reprice.
What I subtract: Project Debt + Net Treasury
I add up all the segment values above, then subtract what Galaxy owes. Project debt is non-recourse (meaning it's tied to the data center assets, not Galaxy as a company): $5.5B for Phase I-III. Pipeline debt scales with buildout ($0 bear, $4B base, $9B bull). Net treasury after corporate debt and cash: negative $2.3B
Dilution: 10% bear, 5% base, 3% bull
Galaxy has diluted shareholders aggressively in the past, nearly doubling share count since 2021. In the bear, I assume they tap equity markets again. In the bull, strong cash generation limits the need. I divide the total equity value by the diluted share count to get the per-share price target.
Here's the base case math all the way through: $17.1B + $4.7B + $6.5B + $2.0B + $1.75B = $32.05B in total segment value.
Subtract $5.5B Phase I-III debt, $4.0B pipeline debt, and $2.3B net treasury.
That leaves about $20.3B in equity value. Divide by diluted shares after 5% dilution and you get $50/share.
After dilution: bear $34, base $50, bull $66.
Here's what's wild. Helios Phase I+II contracted value alone, after subtracting all project debt and treasury, covers most of the current stock price.
At $24, you're paying almost nothing for Phase III under construction, the entire pipeline, an institutional crypto platform with $5B AUM, and $1.3B in digital assets.
The market prices Galaxy as a crypto proxy. The SOTP says it's contracted power infrastructure with crypto upside attached for free.
The next catalyst: Galaxy is expected to announce a second contracted tenant this summer. If the terms match CoreWeave's, this model gets repriced overnight.
I share all my positions and thesis updates in real-time at Milk Road PRO. You can join today at 33% discount (link in bio).


Ben gravel retweeted

I'm just gonna ask @SullyCNBC straight up, cause hes a great guy and can maybe hopefully give some color. Why have you had every BTC miner on under the sun, yet @novogratz is never invited, when $GLXY IS the LEADER in this space, more MW approved than anyone.
Is there an issue?

Ben gravel retweeted

Strong move ahead in GLXY Galaxy Digital (GLXY) could be on the verge of massive reversal HIGHER.
This could send the stock more or less straight up in wave 3.....
The move will not take long. Impulsive and forceful.
I am massively LONG!
See chart here:
teapawt.net/HenrikZeberg/status/20…
You're unable to view this Tweet because it's only available to the Subscribers of the account owner.

Ben gravel retweeted

$OPEN | Why Opendoor Is Moving Higher
@ericjackson @nejatian
• Added to the Russell 3000 Index, increasing institutional visibility and potential fund inflows.
• Investors are encouraged by CEO Kaz Nejatian's highly performance based compensation structure, aligning management with shareholders.
• Eric Jackson (EMJ Capital) reiterated his long term bullish thesis, calling Opendoor "real estate's Tesla moment," with price targets of $82 by 2028 and up to $500 by 2033.
• Technically, $OPEN is trading above both its 20 day and 50 day moving averages, signaling improving short term momentum.
• MACD has turned bullish, suggesting buying momentum continues to strengthen.
• Key resistance: $5.50. A breakout above this level could open the door toward the 200 day moving average near $5.96.
• Key support: $4.50, where buyers have recently stepped in.
• Long term trend damage from the March death cross still exists, but bulls are beginning to rebuild the trend.
• The company continues to expand beyond iBuying with Marketplace, agent partnerships, title insurance, and escrow services, creating a more integrated real estate platform.
Bottom line: Momentum, index inclusion, improving technicals, and a strengthening long term narrative are all bringing renewed attention to $OPEN.

Ben gravel retweeted

At long last, my #2026NHLDraft Ranking is finally out
A more streamlined approach with only 38 000 words but with the same level of heart and passion throughout my analysis
Thanks for commenting and sharing
FRENCH : toutsurlehockey.com/tslh-esp…
ENGLISH : toutsurlehockey.com/tslh-esp…

Ben gravel retweeted

If you’ve ever found any of my content useful do me a huge favor and RT this and tag @stoolpresidente and I’ll leak the alpha too


Ben gravel retweeted

$HIVE.NE @HIVEDigitalTech shares jumped 12% in pre-market trading Thursday after announcing a 3-year #GPU cloud contract worth about $220M for a Canadian sovereign #AI infrastructure deal with Bell Canada and Cohere.
The move gives HIVE one of the clearer contracted AI/HPC revenue paths among #bitcoin miners racing to turn power and data center assets into long-term compute businesses.

Ben gravel retweeted

Top 32: Liste finale 2026 de Simon St-Laurent toutsurlehockey.com/tslh-esp…


Ben gravel retweeted

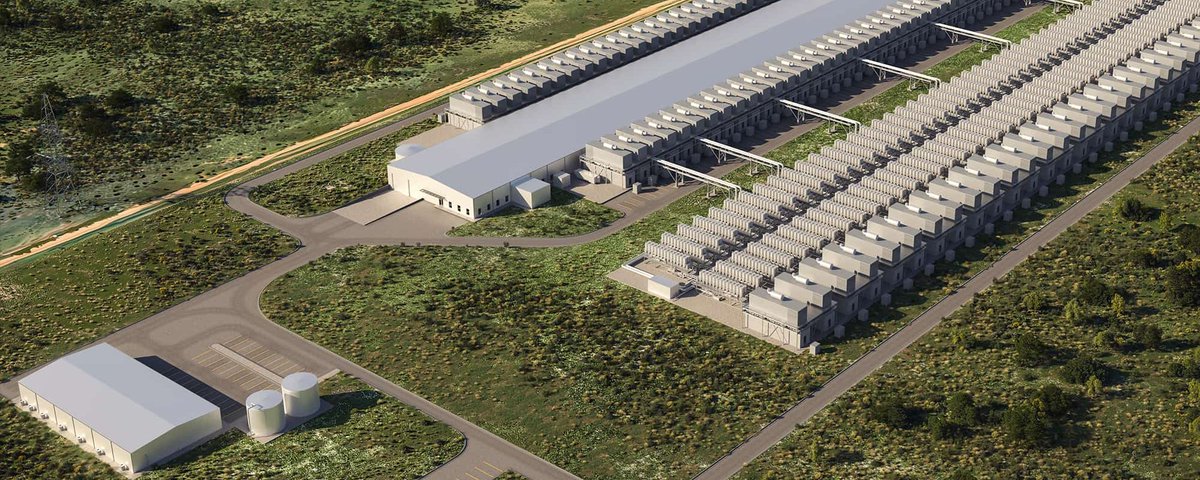
A quick recap on Galaxy Digital's $GLXY Helios data center campus:
- 1.63GW (gross) of fully ERCOT approved, front-of-the-meter power.. An incremental 1.8GW sits in ERCOT's approval queue, which if approved as expected, would scale the site to 3.4GW... "The largest single campus data center in America:"✅
- 800MW gross, 526MW IT load contracted to CoreWeave for $1B+ of annual revenue over a 15 year lease, with the first phase of the project on-time, on-budget, and now generating revenue (execution chops:✅)
- 830MW gross, ~550MW IT load to be leased out "by the time Fourth of July comes around, or certainly by the summer ends" (tenant diversification: 🔜)
- 1,500 construction workers currently on-site, which "will max out to 2,500" (labor procurement: ✅)
- Located in Afton, TX, a remote town with a population of only ~200 people.. "Very business friendly.. a part of the country, and a part of Texas, where you can build data centers without a lot of community problems. We're in the middle of nowhere, we got lots of spare electricity out there, so were not driving electricity prices up for the local community... (no) noise pollution. Texas is one of the best places for data centers, (and) we've looked at other cities, and states." (optimal location: ✅)

"GALAXY IS BUILDING WHAT WILL BE THE LARGEST SINGLE CAMPUS DATA CENTER IN AMERICA"
"KNOCK ON WOOD, BY THE 4TH OF JULY WE WILL HAVE LEASED OUT — OR CERTAINLY BY SUMMER’S END WE WILL HAVE LEASED THE FULL 1.6GW" $GLXY