

Analyst at @Milkroaddaily | Hunting mispriced conviction | Building @Portfolio_OS
Joined August 2016
- Tweets3.7K
- Following1.1K
- Followers5.3K
- Likes4.7K



Pinned Tweet
Galaxy reports tomorrow before the open.
Since early September, the stock has cratered 43%, landing near $15 today, and it has nothing to do with Galaxy’s execution. It is fallout from its tenant, CoreWeave, and the broader AI rout.
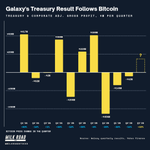
Over the last 90 days $GLXY has moved with CoreWeave, not bitcoin. And the last Q2 report didn't help either: an $85M net loss and a 14% drop on the day.
But Q3 can be a real game-changer. Here's what I'm expecting tomorrow:
m0xt retweeted
Instacart reportedly offered itself to Uber. Uber reportedly said no.
As an Uber holder, that news didn't surprise me.
On Thursday, it came out that Instacart, worth about $12B, is exploring a sale and had early talks with Uber and DoorDash. The stock jumped 9% to $56.44. Uber and DoorDash both fell about 3.5%.
Then after the close it was reported that Uber had already walked away, and an Uber official said there are no talks right now. That leaves DoorDash as the only named buyer.
Here's why I think passing was the right call.
Uber says openly that it measures every acquisition against their own hurdle rate, including buying back its own stock. So a deal only happens if the price is good enough to beat that. If Uber said no, my guess is the price was too high for the upside it saw. At the right price, I think Uber would still have done it.
Uber also already has a lot on its plate. It's buying Delivery Hero for $14.8B and ezCater for $2.3B, both in cash. A typical 30-40% premium would put Instacart at roughly $15.6-16.7B on top of that. Together, all three would come to about $33B, more than three years of Uber's free cash flow. Buybacks already dropped to $510M last quarter from $1.4B a year earlier.
And Uber is already beating Instacart in grocery without buying it. Uber's grocery business is growing about 40% a year, Instacart's about 13%. Why pay a premium for the rival you're taking share from?
The bull case for a deal is real though. Grocery is the biggest delivery category left. Instacart brings 2,200 retailers, an ads business doing around $300M a quarter, and about $1.3B of EBITDA expected this year. It would have closed the grocery gap in one move.
The risk now is DoorDash. If it buys Instacart, it leads US restaurant delivery and grocery delivery at the same time. That's a much harder antitrust case, but if it clears, Uber Eats is a clear No. 2 in the US.
Uber is priced at about 13x free cash flow, whereas DoorDash commands closer to 37x. To me, that gap reflects an opportunity. Uber has the scale and breadth to steadily siphon share from DoorDash over time. It is global, it is not a one-trick delivery business, and it can lean into platform network effects. That could mean outspending on customer acquisition or rolling out differentiated perks and functionality that pure-play delivery apps cannot easily match.
UBER is one of the main stocks in my Milk Road portfolio. You can see it here: link.milkroad.com/Martin


INSTACART EXPLORES SALE, HOLDS TALKS WITH UBER AND DOORDASH
$CART, valued at around $12 billion, is working with an investment bank and has held preliminary discussions with $UBER and $DASH, according to The Information.
Interestingly, Instacart previously held talks with DoorDash in 2021 over a potential deal valued at $40B to $50B, but negotiations fell apart.
Instacart reported $1.04B in Q2 revenue, up 14%, and generated $480M in free cash flow.
No deal is guaranteed, and any acquisition by a major delivery rival could face antitrust scrutiny.

m0xt retweeted
Morgan Stanley's worst case for Galaxy is $16. The stock closed Friday at $14.68.
TeraWulf is even further off. The bank's bear case is $17.50, and it closed at $11.32. I own both.
Morgan Stanley reiterated Overweight last week, with base targets of $65 on TeraWulf and $43 on Galaxy, and called the selloff a buying opportunity. Four of the seven names in its table (TeraWulf, Galaxy, Hut 8 and Riot) now trade below the bank's own bear case.
So either the bear case is too generous, or the market is pricing something worse than a bad year. I think it's pricing the second one: money for building drying up.
Elon said it bluntly on Sunday. Debt markets have "almost entirely shut off access to money for any company that doesn't have substantial revenue independent of AI data centers." These landlords build mostly with borrowed money, so that sentence covers them too.
He's right about the debt markets. But I think the risk is smaller here than for the neoclouds. These companies raise money to buy land, put up buildings, and connect them to power. They keep owning the land and buildings, and buildings depreciate over 25 years or more. Whatever happens to the AI trade, those assets don't go away.
The rent they build against usually comes from hyperscalers or neoclouds, so the tenant risk is real. But I find it hard to imagine we'll use less of those services in the future than we do today. Whoever owns the land, buildings, and grid connection owns a valuable asset. Still, this capital-intensive phase is touching everyone, and anyone looking for funding will likely have to pay a steeper price for it, assuming they can secure any at all.
But here is the other side of this trade: Morgan Stanley's TeraWulf target is about double the Street average of around $33. It also leads TeraWulf's credit line, which just got upsized to about $400M. They might be biased.
And Galaxy's only Helios tenant is CoreWeave, whose funding gap banks put anywhere from $23B to $76B. The next tenant will definitely help.
For all the noise, the market is pricing these PSPs at levels, and with implied upside, that are hard to look past. This is not a free lunch, but the asset base puts a floor under the downside, while the ceiling is essentially set by how much pricing power they can extract at the table.
Galaxy reports Q3 tomorrow before the open. I want to see a profitable crypto business and any news on a second Helios tenant.
PSPs are 13.6% of my portfolio on Milk Road. You can see the rest here:
link.milkroad.com/Martin


The market misprices great businesses all the time. At Milk Road, we find them before everyone else does.
That's how we caught $GLXY, $HOOD, $NBIS, and $HYPE early.
Want to see every trade we make, live? Check it out here:milkroad.com/pro/?utm_medium…
m0xt retweeted
SK hynix is reportedly weighing a special dividend of about 16T won (~$12B). If it happens, SK Square holders would get a bigger slice than direct SK Hynix shareholders.
The payout would be about 23,000 won per share, roughly 1.8% of SK hynix's market value. Nice, not life-changing.
SK Square owns 20.68% of SK hynix, so it would collect about 3.31T won (~$2.5B). But SK Square trades at a 46.6% discount to its holdings. So that same cash equals about 3.2% of SK Square's market value, close to double what a direct holder gets.
For scale, SK Square's whole 2026 shareholder return plan is 310B won. This one payment would be about 10x that.
The money would come from SK Hynix's old Kioxia stake, roughly 80% of an estimated 20T won gain. Nothing is decided yet. SK Hynix says it's reviewing options; nothing is final, and the board will decide on Wednesday with Q3 results.
Back in August I wrote that special dividends could land on top of the record buyback, with the full plan coming at Q3. That's this week.
The bear case is that the market won't pay for peak-cycle earnings, and a big one-off payout is what companies do at the top. Goldman just cut its KOSPI target from 12,000 to 9,000, though it stayed overweight, and says memory stocks are priced for a ~65% drop in 2027 earnings. Goldman calls that too pessimistic. I agree. In a flat-stock scenario, SK hynix trades under 2x forward earnings by the end of 2027.
The catch for SK Square is that the cash lands at the holding company first. Shareholders only see it if SK Square passes it on or buys back stock, and so far its return plan says nothing about special dividends. I think this is about to change.
Wednesday's SK Hynix board decision, alongside its buyback program, will be a key thing to watch. The second is whether SK Square says what it does with the money.
I’m still firmly bullish on memory. It’s the largest slice of my Milk Road portfolio. See the full breakdown here: link.milkroad.com/Martin


3. The crypto business
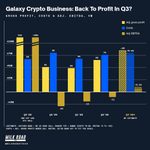
Trading, lending, asset management. Gross profit was $66M in Q2, up 34% from Q1, but it still lost $11M. Losses have shrunk three quarters in a row:
-$29M, -$19M, -$11M.
The costs ran $76M in Q2, so $66M of gross profit wasn't enough.
I think Q3 is the quarter it turns. Crypto finished the quarter much higher, which lifts asset management and staking. Volumes were soft over the summer but returned in September, and costs could also come down.
My bet: ~$85M of gross profit, nearly 30% more than Q2. That's $5-10M of adjusted EBITDA. Anything above zero is a win for me.
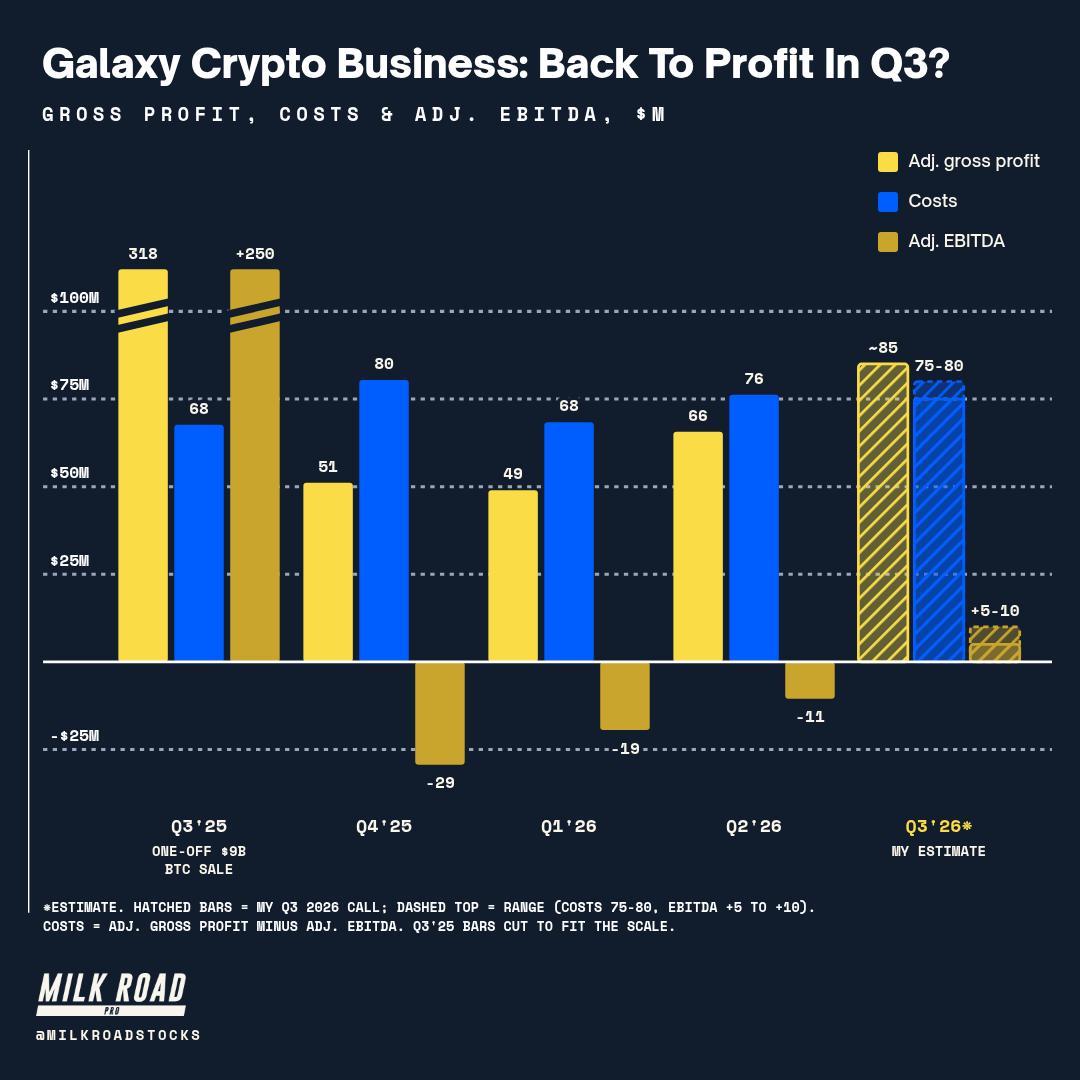
ALT Galaxy Digital Assets segment by quarter: adjusted gross profit, costs and adjusted EBITDA in $M. Q3'25 318/68/+250 (one-off $9B BTC sale), Q4'25 51/80/-29, Q1'26 49/68/-19, Q2'26 66/76/-11, Q3'26 estimate ~85/75-80/+5-10.
My estimate: ~$0.30-0.35 EPS vs ~$0.22 consensus. Most of the gap is crypto marks. The quarter's quality is in Helios and the crypto business.
Two more things. Stock comp runs ~$16M a quarter, and buybacks have offset it: the share count was flat this year. They bought at ~$20. The drop to $15 only came in October, so I'm fine if Q3 buying was light. That just leaves more of the ~$109M left for these prices.
At these prices, I wouldn't be surprised to see them top up the program. The current one runs out in February anyway.
The bear case: Galaxy has one tenant, and that tenant's lenders are nervous. A clean report can't fix CoreWeave's balance sheet.
A second tenant would help a lot. If Galaxy talks about a new customer tomorrow, the one-tenant risk drops dramatically. Not my base case, but it's the upside I'd love to hear.
I will provide an update tomorrow after the earnings.
m0xt retweeted
Companies keep using more AI every month, but for two months now, they haven't paid more for it.
Spending on AI tokens (what businesses pay the labs to run their models) grew just 1% in August and 0.2% in September, the slowest since last November. And it doesn't look like a summer lull. The price per token is down about 41% from the March peak, so companies run a lot more through the models while the bill barely moves.
No surprise that once AI got cheaper, people started relying on it far more; that is the predictable twist known as the Jevons paradox.
What bugs me is who's paying. Apollo found that 80% of the top 1% of AI spenders are VC-backed. So the biggest token buyers are mostly paying with investors' money, not profits.
The bull side says this is fine. A cheap token burns roughly the same compute as an expensive one, so more usage on a flat bill is great news for chips and memory. I mostly agree. Volume is what memory sells into..
But volume only keeps growing if someone keeps funding it. If VC money slows, flat spend turns into falling spend, and the first to feel it are the neoclouds renting GPUs to labs and startups.
The questions I keep coming back to is who is going to spend hundreds of billions on AI? Hyperscalers use most of their compute today for their own products, and EPS growth has been strong every quarter. But the rest of the market hasn't caught up yet.
One caveat: the data below comes from a small sample of companies, so I'd treat the exact numbers loosely and the direction seriously.
Microsoft and Google report Wednesday; Amazon on Thursday. I want to hear whether cloud growth is holding and who is actually renting all that compute. It is less about the backlog number and more about the quality of that customer, and how that contract is financed.
Follow me @m0xt_ for more market updates and insights.

BREAKING: AI token spending grew just +0.2% MoM in September, the lowest monthly growth since November 2025.
This follows a +1.0% increase in August, marking two consecutive months of growth at or below +1.0%, the weakest streak in at least 18 months.
This comes as falling prices for the most advanced AI models, alongside improvements in efficiency and quality, drive down the average price per million tokens processed by these models.
Since July, overall AI token prices have declined -48%, to $0.65 per million tokens, the lowest since at least January 2026.
Lower costs could unlock the next wave of AI adoption.

Instacart reportedly offered itself to Uber. Uber reportedly said no.
As an Uber holder, that news didn't surprise me.
On Thursday, it came out that Instacart, worth about $12B, is exploring a sale and had early talks with Uber and DoorDash. The stock jumped 9% to $56.44. Uber and DoorDash both fell about 3.5%.
Then after the close it was reported that Uber had already walked away, and an Uber official said there are no talks right now. That leaves DoorDash as the only named buyer.
Here's why I think passing was the right call.
Uber says openly that it measures every acquisition against their own hurdle rate, including buying back its own stock. So a deal only happens if the price is good enough to beat that. If Uber said no, my guess is the price was too high for the upside it saw. At the right price, I think Uber would still have done it.
Uber also already has a lot on its plate. It's buying Delivery Hero for $14.8B and ezCater for $2.3B, both in cash. A typical 30-40% premium would put Instacart at roughly $15.6-16.7B on top of that. Together, all three would come to about $33B, more than three years of Uber's free cash flow. Buybacks already dropped to $510M last quarter from $1.4B a year earlier.
And Uber is already beating Instacart in grocery without buying it. Uber's grocery business is growing about 40% a year, Instacart's about 13%. Why pay a premium for the rival you're taking share from?
The bull case for a deal is real though. Grocery is the biggest delivery category left. Instacart brings 2,200 retailers, an ads business doing around $300M a quarter, and about $1.3B of EBITDA expected this year. It would have closed the grocery gap in one move.
The risk now is DoorDash. If it buys Instacart, it leads US restaurant delivery and grocery delivery at the same time. That's a much harder antitrust case, but if it clears, Uber Eats is a clear No. 2 in the US.
Uber is priced at about 13x free cash flow, whereas DoorDash commands closer to 37x. To me, that gap reflects an opportunity. Uber has the scale and breadth to steadily siphon share from DoorDash over time. It is global, it is not a one-trick delivery business, and it can lean into platform network effects. That could mean outspending on customer acquisition or rolling out differentiated perks and functionality that pure-play delivery apps cannot easily match.
UBER is one of the main stocks in my Milk Road portfolio. You can see it here: link.milkroad.com/Martin
INSTACART EXPLORES SALE, HOLDS TALKS WITH UBER AND DOORDASH
$CART, valued at around $12 billion, is working with an investment bank and has held preliminary discussions with $UBER and $DASH, according to The Information.
Interestingly, Instacart previously held talks with DoorDash in 2021 over a potential deal valued at $40B to $50B, but negotiations fell apart.
Instacart reported $1.04B in Q2 revenue, up 14%, and generated $480M in free cash flow.
No deal is guaranteed, and any acquisition by a major delivery rival could face antitrust scrutiny.
The market misprices great businesses all the time. At Milk Road, we find them before everyone else does.
That's how we caught $GLXY, $HOOD, $NBIS, and $HYPE early.
Want to see every trade we make, live? Check it out here:milkroad.com/pro/?utm_medium…
m0xt retweeted

$AAVE already has about 30% market share, and Milk Road analyst Martin thinks tokenization hands it a lot more
"The bull case for AAVE is just easy to make"
His logic: as stocks, treasuries, even houses move onchain, people lend them out, and "liquidity begets liquidity"
Revenue isn't there yet. He has Aave around breakeven today
If that future plays out, he sees a "tens of billions company" in no time
FT @m0xt_ @KyleReidhead @BitcoinJesusETH

Aave doesn't need to find its next million users. Coinbase, Circle and Lido are bringing them.
That's the real idea behind Aave V4. Instead of one lender building every market itself, V4 is a platform. There's one shared pool of money, the Hub, and separate lending markets, the Spokes, that plug into it. Each Spoke has its own collateral and risk rules, but they all draw on the same liquidity.
Now here's where it gets interesting. Every partner that plugs in brings its own users, and those users tap money that's already sitting in the pool. Lido, EtherFi, Ethena and Tether's gold token are live. Coinbase's tokenized stocks on Base, like Apple, Nvidia and Tesla, can now be used as collateral to borrow USDC. Circle went live on its own chain, Arc, in September.
In other words, Aave doesn't have to build each market from scratch. Partners bring the users, and the shared pool gets deeper with every one that joins. That's the flywheel.
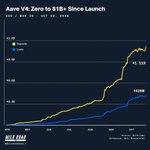
And it's working. V4 went from zero at launch in March to over $1.1B deposited and about $426M borrowed. In the last month alone, deposits grew about 30% and loans about 50%.
To be fair, there are real catches. This isn't open to everyone: each new Spoke needs an Aave DAO vote, while Morpho lets anyone create a market. Rewards are still being used to kick-start some markets. And V4 is still a small slice of Aave.
On risk, each Spoke carries only the risk it signs up for: its own collateral, its own limits, its own liquidation rules. The Hub gives every Spoke a capped credit line, so a bad market can't empty the whole pool.
I’m excited to see V4 keep scaling. This feels like Aave’s next big growth lever. Tokenized equities could be a compelling adoption wedge too, since they will likely be lent out for yield in the end, value that brokers mostly capture today.
Follow me @m0xt_ for more market updates.

Morgan Stanley's worst case for Galaxy is $16. The stock closed Friday at $14.68.
TeraWulf is even further off. The bank's bear case is $17.50, and it closed at $11.32. I own both.
Morgan Stanley reiterated Overweight last week, with base targets of $65 on TeraWulf and $43 on Galaxy, and called the selloff a buying opportunity. Four of the seven names in its table (TeraWulf, Galaxy, Hut 8 and Riot) now trade below the bank's own bear case.
So either the bear case is too generous, or the market is pricing something worse than a bad year. I think it's pricing the second one: money for building drying up.
Elon said it bluntly on Sunday. Debt markets have "almost entirely shut off access to money for any company that doesn't have substantial revenue independent of AI data centers." These landlords build mostly with borrowed money, so that sentence covers them too.
He's right about the debt markets. But I think the risk is smaller here than for the neoclouds. These companies raise money to buy land, put up buildings, and connect them to power. They keep owning the land and buildings, and buildings depreciate over 25 years or more. Whatever happens to the AI trade, those assets don't go away.
The rent they build against usually comes from hyperscalers or neoclouds, so the tenant risk is real. But I find it hard to imagine we'll use less of those services in the future than we do today. Whoever owns the land, buildings, and grid connection owns a valuable asset. Still, this capital-intensive phase is touching everyone, and anyone looking for funding will likely have to pay a steeper price for it, assuming they can secure any at all.
But here is the other side of this trade: Morgan Stanley's TeraWulf target is about double the Street average of around $33. It also leads TeraWulf's credit line, which just got upsized to about $400M. They might be biased.
And Galaxy's only Helios tenant is CoreWeave, whose funding gap banks put anywhere from $23B to $76B. The next tenant will definitely help.
For all the noise, the market is pricing these PSPs at levels, and with implied upside, that are hard to look past. This is not a free lunch, but the asset base puts a floor under the downside, while the ceiling is essentially set by how much pricing power they can extract at the table.
Galaxy reports Q3 tomorrow before the open. I want to see a profitable crypto business and any news on a second Helios tenant.
PSPs are 13.6% of my portfolio on Milk Road. You can see the rest here:
link.milkroad.com/Martin
The market misprices great businesses all the time. At Milk Road, we find them before everyone else does.
That's how we caught $GLXY, $HOOD, $NBIS, and $HYPE early.
Want to see every trade we make, live? Check it out here:milkroad.com/pro/?utm_medium…
SK hynix is reportedly weighing a special dividend of about 16T won (~$12B). If it happens, SK Square holders would get a bigger slice than direct SK Hynix shareholders.
The payout would be about 23,000 won per share, roughly 1.8% of SK hynix's market value. Nice, not life-changing.
SK Square owns 20.68% of SK hynix, so it would collect about 3.31T won (~$2.5B). But SK Square trades at a 46.6% discount to its holdings. So that same cash equals about 3.2% of SK Square's market value, close to double what a direct holder gets.
For scale, SK Square's whole 2026 shareholder return plan is 310B won. This one payment would be about 10x that.
The money would come from SK Hynix's old Kioxia stake, roughly 80% of an estimated 20T won gain. Nothing is decided yet. SK Hynix says it's reviewing options; nothing is final, and the board will decide on Wednesday with Q3 results.
Back in August I wrote that special dividends could land on top of the record buyback, with the full plan coming at Q3. That's this week.
The bear case is that the market won't pay for peak-cycle earnings, and a big one-off payout is what companies do at the top. Goldman just cut its KOSPI target from 12,000 to 9,000, though it stayed overweight, and says memory stocks are priced for a ~65% drop in 2027 earnings. Goldman calls that too pessimistic. I agree. In a flat-stock scenario, SK hynix trades under 2x forward earnings by the end of 2027.
The catch for SK Square is that the cash lands at the holding company first. Shareholders only see it if SK Square passes it on or buys back stock, and so far its return plan says nothing about special dividends. I think this is about to change.
Wednesday's SK Hynix board decision, alongside its buyback program, will be a key thing to watch. The second is whether SK Square says what it does with the money.
I’m still firmly bullish on memory. It’s the largest slice of my Milk Road portfolio. See the full breakdown here: link.milkroad.com/Martin
The market misprices great businesses all the time. At Milk Road, we find them before everyone else does.
That's how we caught $GLXY, $HOOD, $NBIS, and $HYPE early.
Want to see every trade we make, live? Check it out here:milkroad.com/pro/?utm_medium…
Companies keep using more AI every month, but for two months now, they haven't paid more for it.
Spending on AI tokens (what businesses pay the labs to run their models) grew just 1% in August and 0.2% in September, the slowest since last November. And it doesn't look like a summer lull. The price per token is down about 41% from the March peak, so companies run a lot more through the models while the bill barely moves.
No surprise that once AI got cheaper, people started relying on it far more; that is the predictable twist known as the Jevons paradox.
What bugs me is who's paying. Apollo found that 80% of the top 1% of AI spenders are VC-backed. So the biggest token buyers are mostly paying with investors' money, not profits.
The bull side says this is fine. A cheap token burns roughly the same compute as an expensive one, so more usage on a flat bill is great news for chips and memory. I mostly agree. Volume is what memory sells into..
But volume only keeps growing if someone keeps funding it. If VC money slows, flat spend turns into falling spend, and the first to feel it are the neoclouds renting GPUs to labs and startups.
The questions I keep coming back to is who is going to spend hundreds of billions on AI? Hyperscalers use most of their compute today for their own products, and EPS growth has been strong every quarter. But the rest of the market hasn't caught up yet.
One caveat: the data below comes from a small sample of companies, so I'd treat the exact numbers loosely and the direction seriously.
Microsoft and Google report Wednesday; Amazon on Thursday. I want to hear whether cloud growth is holding and who is actually renting all that compute. It is less about the backlog number and more about the quality of that customer, and how that contract is financed.
Follow me @m0xt_ for more market updates and insights.
BREAKING: AI token spending grew just +0.2% MoM in September, the lowest monthly growth since November 2025.
This follows a +1.0% increase in August, marking two consecutive months of growth at or below +1.0%, the weakest streak in at least 18 months.
This comes as falling prices for the most advanced AI models, alongside improvements in efficiency and quality, drive down the average price per million tokens processed by these models.
Since July, overall AI token prices have declined -48%, to $0.65 per million tokens, the lowest since at least January 2026.
Lower costs could unlock the next wave of AI adoption.
The market misprices great businesses all the time. At Milk Road, we find them before everyone else does.
That's how we caught $GLXY, $HOOD, $NBIS, and $HYPE early.
Want to see every trade we make, live? Check it out here:milkroad.com/pro/?utm_medium…
NEAR AI lets you talk to an AI that literally can't see your data. Even the company running the server can't read your prompts, and the chip proves it.
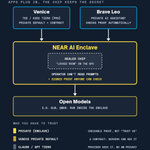
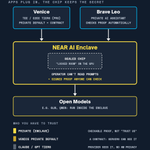
Here's how it works. Your prompt is processed inside an "enclave", a locked room inside the chip that keeps data encrypted even while it's being worked on. The chip then signs a proof that this exact code runs in a locked room on a genuine chip, and anyone can check it for free. Most "private" AI is really "trust us". This one you can verify.
And apps are already plugging in. Brave's Leo assistant has run on NEAR AI since Oct 15 and checks the proof automatically. Venice runs its paid private tiers on NEAR AI and Phala. In other words, NEAR AI is quietly becoming the private backend other apps run on. It also looks asset-light: a privacy layer on rented chips, not a company buying its own GPUs.
Now here's where it gets interesting for the token. The privacy comes from the chip and the proof, not from the chain. You pay per token like any AI service, and the company gets that revenue. The only link to NEAR is staking: more than 1M NEAR is staked so the staking rewards pay for AI credits, but those rewards are newly issued NEAR. So the token mostly funds the product rather than earning from it.
There are fair limits too. Closed models like Claude, GPT, Gemini, or Grok on NEAR AI aren't hardware-private, because the provider still sees your prompt.
Overall, the product is great, but the token doesn't capture any value. NEAR stays on my watchlist.

ALT Diagram of NEAR AI as a private AI backend for apps
There's a lot of noise about NEAR right now, so let me break it down.
NEAR has two products worth knowing: NEAR Intents, a cross-chain swap engine that just had its biggest month ever, and NEAR AI, which keeps your AI prompts private in a way you can actually check. Now here's where it gets interesting. One of them doesn't even need a blockchain.
And then there's the bigger question: does any of this matter for the token? A lot of people seem to be buying NEAR simply because it sits where AI, crypto, and privacy meet, probably three of the year's hottest stories. But a good story and a token that earns from it aren't the same thing.
Start with Near Intents. You just state the result you want, like "swap my USDT on Ethereum into ZEC." Professional trading firms compete to fill it, and NEAR settles it. You never hold or even see NEAR. Wallets like Ledger, Brave, Rabby, and Solflare already support it.
September hit a record $4.80B, about 10x what it was a year earlier, and roughly $160M a day. October has cooled to about $132M a day.
Here's the catch for holders. In the last 30 days, Intents made about $7.33M in fees. About $2.34M of that goes to NEAR, and it buys NEAR on the market. But new NEAR is issued at 2.5% a year, so the buyback covers only about a sixth of the new supply. Meanwhile, daily active accounts on NEAR itself are down 79% from a year ago.
The bear case is real too. The volume spikes line up with ZEC privacy trading, an exploit of about $3.8M on Oct 1, paused Intents, and September was one parabolic month. You can't ignore these things either.

The market misprices great businesses all the time. At Milk Road, we find them before everyone else does.
That's how we caught $GLXY, $HOOD, $NBIS, and $HYPE early.
Want to see every trade we make, live? Check it out here:milkroad.com/pro/?utm_medium…