

Hedge Fund PM in a prior life. Ask me anything. Not investment advice, just opinions and thoughts. Please do your own due diligence.
Joined January 2021
- Tweets1.6K
- Following56
- Followers3.6K
- Likes1.1K





I’ve said this since May of 2026.
teapawt.net/spacman17/status/20551…
Welcome to the party. The strategic value of $ASTS is unquestionable. There is no other alternative solution on the near-term horizon.
$ASTS sellers are actually doing the company a disservice as carriers will use today’s price as indicative of the value any spectrum-to-equity deal should be valued at.
People complaining about $ASTS being silent should perhaps ask themselves whether management is purposely being quiet due to significant strategic conversations happening in real-time. Companies evaluating strategic alternatives have a heightened sensitivity to public disclosures, worried about how that might risk deal discussions.
That said, here is how I think this goes down. $VZ, $T, $TMUS would love to secure $ASTS and the only way to do that is for all of them to equally have a significant equity stake and board representation. What ASTS would perhaps want is to own more spectrum. A spectrum to equity swap makes sense and $ASTS could look and operate similar to how the media players owned Hulu.l when they needed to compete with $NFLX.
I do think this also extends to no U.S. carriers as mobile is moving global.
The one advice I have to @AbelAvellan and @scottwisniews is if they do consider a transaction, they better get a massive premium on a deal as the carriers have no option and they will likely get what they want anyways by staying independent - which as a public shareholder is what I would prefer to any deal.
I can’t wait for @laurenthomas or @davidfaber to break this in a few months.

Let me clarify why I changed my position on AST SpaceMobile.
It started when the DT Telecom CEO publicly called on MNO CEOs to block SpaceX from securing MVNO deals.
I've been calling for the @FCC @BrendanCarrFCC and @JusticeATR to step in and establish regulatory protections to ensure fair competition for MVNOs for some time now and that simply hasn't
I believe the logical next move for MNOs is to build or acquire a credible alternative to SpaceX to put investor's fears aside and to stop the volatility in there Share price every time spaceX hints at them building a mobile network😀
And that's where for me AST comes in.
I could be wrong, but I believe the MNOs will ultimately look to secure AST, either through the joint venture they announced, a strategic acquisition, by a form of global consortium why because thats what I would do.
the last thing the world's largest mobile operators should want is to become dependent on a single satellite provider that could ultimately become their biggest competitor.
To be clear I haven't changed my view on AST's technology or its going it alone chances of success I still consider huge challenges for them. I've changed my view on its strategic value.
And sometimes strategic value is worth a hell of a lot more than the business itself.
Now this is not investment advice just my personal veiw.
SP🅰️C-M🅰️N retweeted
Ethena Pay expects to start opening in the US, UK and Europe in three to four weeks, Guy Young said on Unchained. The card companies behind the app often set the pace.
unchainedcrypto.com/ethena-p…

$FRNM
Continues to grind, is at all-time high. Still room to go per analyst price targets:


$FRNM
Jefferies initiates on @freenome with a PT of $17.
"Multiple Screening Shots on Goal; Initiate at Buy, $17 PT
Freenome is a cancer screening company developing blood-based tests across CRC, lung and other indications. Differentiation stems from the multiomics and AI-driven R&D platform, while Abbott and Roche partnerships support an asset-light commercialization strategy. Although broader commercialization only begins this fall, we see multiple avenues for value creation (royalties, milestones, indication expansion). Initiate at Buy, $17 PT supported by DCF.
Nascent CLIA lab with unique screening playbook. Freenome (FRNM) is developing a portfolio of blood-based cancer screening tests spanning CRC (120M eligible U.S. patients), lung (15M) and 10+ other indications. Leveraging proprietary multi-omics capabilities and partnerships with ABT (CRC only) and ROP-SW (ex-U.S. IVD), we see FRNM as uniquely positioned from a development and commercial standpoint, with a multi-year penetration ramp ahead.
Testing roadmap. Colorectal cancer screening (CRC) remains the near-term focus, following v1 FDA approval and recent release of v2 data, with a broader ABT-supported commercial launch in the fall. Longer term, FRNM's value proposition lies in pull-through revenues from patients receiving screening for CRC and at least one other indication (101M patients co-eligible), with lung (15M patient TAM) the next major indication. We see a steady cadence of reimbursement catalysts on deck, following American Cancer Society (ACS) guideline inclusion for CRC and potential for commercial coverage prior to USPSTF guideline review (expected late '27/'28).
The benefit of an asset-light commercialization strategy. FRNM expects to have 300-400 sales reps at scale, aiming to capitalize on a top-down health system approach, in addition to leveraging EXAS/ABT's scale (1.4k commercial employees) while retaining exposure to $700M in potential milestones and royalties (up to 10%). Internationally, Roche provides kitting upside, alongside access to the nascent Axelios NGS ecosystem, which should allow FRNM to focus capital on assay development and R&D vs. building a global commercial engine from scratch.
Financials. Revenues will be gated amid the initial CRC rollout (with GMs ramping towards a 10% royalty rate by YE27), however, FRNM should benefit from $170M in near-term milestones ($100M on v1 FDA approval, $70M on v2 approval and tech transfer to ABT). The launches of lung and other indications should support additional testing revenues, with a path to mid-teens royalties on Roche's ex-U.S. kit solution still viewed as upside.
Initiating at Buy. With access to ABT's proprietary database of 7-10M patients who have not adhered to Cologuard, we see FRNM's launch ramp exceeding Shield's, albeit with an inferior economic profile (royalties). While there are always likely to be partnership risks and questions around ABT's commercial incentive to sell FRNM tests relative to other options, we see enough optionality (pull-through, milestones) to support the current EV ($800M) with room for expansion."
My prior due diligence below:


Remember when these guys tryed to go public at a $550 million valuation? lolz

THE BLOCK: eToro has agreed to acquire TradeZero, a U.S.-focused online brokerage, in a deal valued at up to $231 million.
The announcement comes as eToro posts its Q2 results, which showed continued profitable growth. Net contribution rose 9% year-over-year to $229 million, driven mainly by stronger equities trading.


SP🅰️C-M🅰️N retweeted

If you are like me, and you're looking for ways to invest in the public markets behind companies that are going to solve novel real-world problems as AI models continue improve exponentially, $FRNM (Freenome) may be a good name to look at. It is worth watching this presentation from the CEO at $NVDA GTC earlier this year. Right now they are focused on a specific blood based cancer screen for colon cancer, but clearly the vision of the CEO is much greater than one test. The slate of investors and management team are 1st tier. It has the potential to be a future platform company for AI-based health care screening and drug development.
nvidia.com/en-us/on-demand/s…
$ASTS The man speaks the truth. Consistent since 2022.

SpaceX buying spectrum and competing against MNOs? Oh that’d be amazing for @AST_SpaceMobile.


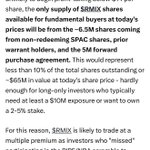
$RMIX - stock down almost 8% today on yesterday's filing that amended the credit agreement to expand the term loan and to carve out any equity raise (up to $400m) from needing to pre-pay any loan amounts.
This is good as it means RMIX has some deals to do. Stock is down as people hedge into the potential stock offering that is likely coming.
Expect stock to be weak but then rebound post equity offering (whenever it comes).

I bought 3,888,888 ethereum:0x57e114b691db790c35207b2e685d4a43181e6061
This is not investment advice
BlackRock and RobinHood integration
1.) Ethena's USDe synthetic dollar serves as primary collateral for the decentralized lending product: “Robinhood Earn”
2.) BlackRock integrated USDe onto its Aladdin risk-management platform. This adoption by the $25 trillion institutional network extends USDe access to traditional banks and pension funds
#POSITIVITY


These guys are also partnered with @coinbase. Looks like some of the biggest fintechs are partnered with @Ethena. $USDE @stablecoin_x

JUST IN: More ways to earn.
Now you can choose how you earn when you lend.
→ Prime: backed by blue chips like BTC and ETH.
→ High Yield: higher potential, backed by a broader mix of assets, including those powered by @ethena.
More choice, more opportunity.
And Janus Henderson….

Ethena has partnered with Janus Henderson, a $480 billion asset manager, to allocate and support the distribution of their liquid high-quality CLO tokenized funds.
As part of the partnership Janus Henderson has made a strategic investment into Ethena's governance token, will allocate into USDe as part of their treasury cash management, and is also exploring avenues to distribute USDe to their client base via exchange traded instruments.
And BlackRock…
Excited to announce our collaboration with @Blackrock.
→Integration of USDe into BlackRock's Aladdin platform
→BUIDL as the primary asset for our whitelabel product
→Liquidity facility on BlackRock tokenized products
The integration of USDe on Aladdin provides unique institutional access for the >$20 trillion of assets managed by financial institutions on Aladdin.
