

Journalist | Data Stories | Gold | Silver | Agriculture | Crypto | Bitcoin | Mutual Funds | Equity Market | Forex | Economy | Policy | Foreign Trade |
New Delhi
Joined September 2012
- Tweets7.2K
- Following663
- Followers636
- Likes329


Gold Q3 Demand
Total Q3 gold demand, including OTC, was 1% lower y/y at 1,369t. On a y-t-d basis, demand of 3,881t virtually matches the 2025 record (3,884t), while value set a record of US$566bn.
Central bank buying jumped to 321t in Q3, eclipsing recent typical quarterly buying levels and lifting y-t-d demand to 675t (+6% y/y).
Gold ETFs reversed course following the Q2 outflows, adding 211t in Q3. The inflow seemed to be driven by mounting concerns over fiscal sustainability and inflation, among other things.
Bar and coin investors were more circumspect; global demand was 19% lower y/y at 268t as investors waited for a clearer price trend to emerge.
Jewellery demand fell 17% y/y to 313t, the weakest third quarter in our data series, as high prices remained a headwind across all markets. Demand value edged up 2% y/y to US$43bn.
Gold used in technology increased 3% y/y in Q3 as demand generated by AI-related manufacturing more than offset the limiting effect of high gold prices.
Source: WGC


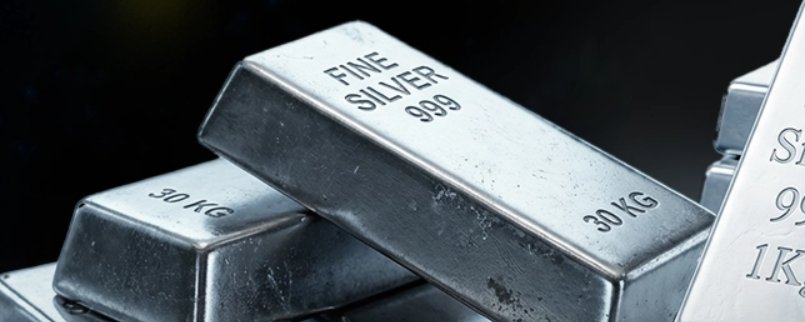
#Silver Price Falls to $49/oz, The Level Which was Record High for Decades before December 2025.

#ForexReserve Further Declined to $719.75 Billion During Week Ending October 23rd


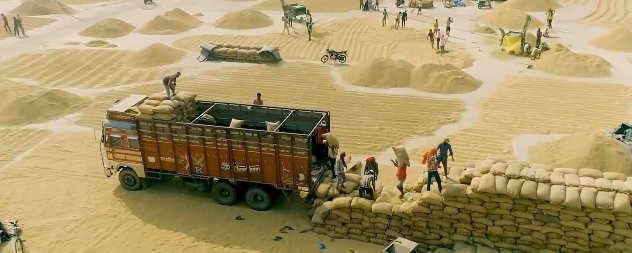
Soybean Season 2026-27 Report
Season Begins with 8.31 Lakh Tonnes Carry Forward Stock Against 7.66 Lakh Tonnes Last Year
Carry Forward Stock for Soymeal Seen at 1.93 Lakh tonnes Against 68 Thousand Tonnes Last Year
Industry Estimates 107.93 Lakh Tonnes Production in 2026-27, 2.11% Less over Last Year
Soybean Import During 2025-26 Seen at 11 Lakh Tonnes, Highest Yearly Import. Only 2 Thousand Tonnes was Imported in 2024-25

Sugar Production for Ongoing Season Till Oct 25th Reaches 4 Lakh Tonnes
Sugar Season 2026-27 (Oct-Sep) has started with nearly 107 sugar mills having commenced crushing operations across Maharashtra, Uttar Pradesh, Tamil Nadu and Gujarat.
The previous sugar season, 2025–26, ended with approximately 36 lakh tonnes of carryover stocks, providing a base for meeting domestic consumption requirements.
As of 25 October 2026, sugar production during the current 2026–27 season had reached approximately 4 lakh tonnes, compared with around 0.6 lakh tonnes on the corresponding date last year.
So far, 107 sugar mills have commenced crushing operations across India, including close to 87 mills in Maharashtra, two mills in Uttar Pradesh and 17 mills across Tamil Nadu, Karnataka and Gujarat.
Crushing operations in other states are progressing in line with their respective seasonal schedules.
Global markets could face a week of sharp volatility. From October 28 to 30, several key data releases and central bank decisions are due, with the potential to affect global stock, crypto, commodity and currency markets.
South Korean companies SK Hynix and Samsung Electronics are set to release their September-quarter results this week. Their earnings could offer clues about the returns on the massive global investment in AI.
The U.S. is also due to release third-quarter GDP growth figures, alongside GDP data for the European Union. These releases could influence markets worldwide.
In addition, the U.S. Federal Reserve is set to announce its interest rate decision on October 28, followed by the European Central Bank on October 29 and the Bank of Japan on October 30. Their decisions could also move global markets.


