

COO @eco. Former lawyer. Crypto since 2014. Previously @circle @hometap @goodwinlaw.
Boston
Joined April 2011
- Tweets364
- Following199
- Followers1.1K
- Likes295



Honored and humbled that Circle decided to subtly recognize my early contributions by naming their chain Ark (Arc).

Arc Mainnet is live.
Arc launches as the Economic OS for the internet: an open platform for global markets, real-time value movement, tokenized assets, and agentic economic activity.
Arc is more than a blockchain.
It launches as a full-stack financial platform with assets, applications, interoperability, developer infrastructure, and Circle platform services live from day one.
Arc delivers USDC as native gas, deterministic sub-second finality, EVM compatibility, and institutional validators.
It integrates with Arc Studio, App Kits, Arc Portal, Circle Agent Stack, CCTP, Gateway, CPN, and StableFX.
A complete economic platform at genesis.
Arc launches with infrastructure for:
→ Agentic economic workflows
→ Lending and borrowing
→ Trading and liquidity
→ Onchain FX
→ Payments and settlement
→ Tokenized assets
→ Exchanges, wallets, custody, compliance, data, and developer tooling
190+ institutional and ecosystem builders are building across Arc.

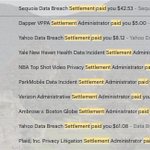
Nobody talks about the upside of KYC though.
When your data is inevitably stolen, it leads to a never ending stream of tiny payments from class action settlements.
People out there chasing memecoins when they should be KYCmaxxing.


Going from one token to another used to mean 5 open DEX tabs, hunting for liquidity, plotting multiple hops and hoping none failed. Now you just click a button and let @eco power the whole thing. And using deep stablecoin liquidity in the middle means great price execution.

On almost every chain, the most liquid path between any two tokens runs through a stablecoin.
Today, we're consolidating that into a single API call. Live in Eco Routes: Any-to-Any Swaps convert any token on one chain into any token on another, with solvers holding only stablecoins in between.
Any-to-Any Swaps settle transactions using @LayerZero_Core.
Everything routes through stablecoins with Eco:

The EU knows they will look dumb if even Circle can't comply and Circle has enough structure with it's EMI French entity that they'll come up with something good enough that hand waves some of the fungibility and reserve issues.

circle has 12 months to solve an unsolvable problem
usdc can't comply with both mica and genius act using one token. eu requires 30% reserves in eu banks, us requires 100% in us treasuries
same address can't redeem through both systems. $35b liquidity splits into usdc-us and usdc-eu. defi protocols need separate pools for each. price divergence nearly guaranteed
Years and years ago a European regulator told me it was impermissible to store European personal data in a US AWS instance but it was totally fine to contract with our US entity to do the same. EU privacy interests magically solved via intercompany agreement. They love strict rules but then give you enough "steer" to find a path.
People will read this tweet, get inspired, and then go build a decentralized BNPL protocol so people can stretch pay their cruise vacation at 37% APR over 2 years.

When people notice that @lifiprotocol has gotten faster and cheaper for stables and so you introduce them to @eco.

Stablecoins can now go wherever you need them to thanks to our integration with @eco.
The future of stablecoins, powered by LI.FI.
It's 2025 and you're *not* using unbalanced merkle trees and async-first nonces to streamline multichain UX? Yikes. Better check out Permit3 before anyone notices.
At Eco, we're obsessed with creating seamless cross-chain experiences with stablecoins. There's still much more to build.
Today, we're open-sourcing Permit3, a contract that enables multichain token approvals with a single signature.
eco.com/blog/introducing-per…

Marquis de Lafayette was the person most responsible for winning the American Revolution on the French side.

Imagine if your TV seamlessly aggregated Netflix, HBO, Prime, Apple, Disney, etc. into one browsing experience. One login. One payment flow. The modularity of streaming with the simplicity of cable.
That's what @eco does for stables.
This is spot on. There is no one size fits all when it comes to companies and their stablecoin strategies.
But that also leaves end users navigating countless stables and chains, and without the proper interoperability and liquidity layers we'll just move from walled gardens to kinda sorta open networks where you have to slog through bridges and swaps and the mental load will remain too high.
That's why protocols like @eco will be so important. Companies get to choose their optimal chain/stable strategy but end users won't have to care - because they'll move seamlessly between them.

Most companies entering the stablecoin conversation are asking the wrong question.
They're debating @Ethereum vs @Solana vs @Base. They're comparing technical features and transaction speeds.
But the real question isn't which blockchain to use.
The real question is: how much distribution do you have?
After conversations with dozens of companies building stablecoin strategies, I've noticed they all face the same decision tree. And most are choosing the wrong path because they're optimizing for technology instead of economics.
Here's what I'm seeing in these conversations:
Some companies are trying to build on @USDC or $USDT. Unless you can negotiate a revenue share deal with Circle or Tether, you're basically paying rent on someone else's success. Not great economics.
Others want to create their own stablecoins using infrastructure like @M0 or @stablecoin. Both let you build your own branded stablecoin using their tech stack. M0 is open - your stablecoin can interact with the broader ecosystem. Bridge is closed-loop (for this example) - like @Dakota_xyz's DKUSD that stays within their banking platform.
Some are exploring shared economics models like @global_dollar Network. Instead of creating your own stablecoin, everyone uses the same $USDG (issued by @Paxos) and you get revenue share from the shared pool based on your contribution to the network.
And a few are considering launching their own chains. If you're Stripe with millions of merchants, why give away sequencer fees? Same logic applies to any company with massive distribution.
The smart ones are mixing approaches. Some will launch their own stablecoin + chain. Others will use USDG's shared model ( @Krakenfx, @RobinhoodApp to name a few). Some will issue their own stablecoin while building on Solana or Base.
The insight most people normies miss: USDC doesn't have distribution. Coinbase has distribution.
If you're a neobank building your first stablecoin product, deploying on Solana probably makes sense. Look at @Kastcard. (check comments for a good video about this)
If you're a company with 400 million users, why would you give away all those infrastructure fees?
Its not a one size fits all approach. Some behemoths will launch their own stablecoin + chain. Others will opt to use USDG, while some issue their own stablecoin while building on Solana, Base etc.
This won't be like SWIFT—one dominant player controlling everything.
This will be like the car industry. Ford, Chevy, Mercedes, BMW. Multiple leaders serving different markets with different strategies.
20 years ago, fintechs dreamed of owning their messaging protocol instead of paying SWIFT tolls.
Now they can actually do it.
But only if they choose the right infrastructure path for their specific distribution and scale.
What's your distribution look like? That determines your stablecoin strategy.
If you want to dive deeper, I dropped the 3 videos below that I send to anyone that asks me about stablecoin issuance.

That's because Money 2020 is five years behind the times.

. @money2020 won't have me to speak about stablecoins at #Money2020USA. I guess one of us doesn't know what they are talking about 🤔

