

full-time satire/comedy. part-time capital allocator & tech nerd 🤓 formerly 20+ years in sell-side IB & equities. not investment/financial advice. DYOR
salomon's house
Joined July 2025
- Tweets1.2K
- Following96
- Followers2.8K
- Likes1.2K





Pinned Tweet
In the picture is a baby orangutan (ape), nicknamed Novita, estimated to be of 3-4 years old
Novita was found clinging to a tree near an oil palm plantation located in Borneo in late Sep
Her palms and soles were burnt, because she had to walk through fire in her habitat to the tree to take refuge
She was rescued by a team after a local resident called it in, and is now undergoing rehabilitation
Land and forest fires have serious consequences for wildlife
The cheap slash-and-burn land clearing practices by the palm oil companies and those who control the concessions need to stop
Time to short those mofo palm oil companies listed in Singapore, Malaysia and Indonesia. Make a call to your banks to question them about their loans to these companies, and their sustainability pledges
APES TOGETHER STRONG

if there's one thing I would advise visitors to emerging Asia - never be too adventurous to try that hole-in-the-wall eatery at a back alley, not matter how great local Google reviews are
i just learnt it the hard way


👀


Elon Musk has good showmanship - if it's not obvious to everyone by now
But let's all do a sanity check how realistic it is to add 10GW of compute within a year (in 2027) when 1) it takes other hyperscale/neocloud/co-lo operators years to scale even 1GW and 2) 10GW is up to 4x their 2.5-3GW exit capacity this year
And we need the shells to be energized
Having those GPUs sitting idle doesn't count - been hearing instances of NVIDIA forcing deliveries of GPUs on customers whose infra isn't yet ready
With all the capacities projected to come online next year (>35-50GW depending on whose estimates to believe) - we also have to track utilization very closely. Stranded capacity risks are non-zero
$SPCX
The ultra-rich Californians opposing the one-time 5% Prop 40 billionaire wealth tax can learn something from the Godfather of AI
And Jensen had not used NVIDIA to create a new share class for fulfilling personal tax obligations like someone at $META lol

Just saw a note that short interest across $CRWV CoreWeave, $NBIS Nebius, $IREN, $APLD Applied Digital and $CORZ Core Scientific currently ranges betwen 20% to 26% of free float ($17B equivalent of stock sold short)
The irony is - some of the sell-side who are constructive on these names are also stock lenders through their prime desk
With this level of short interest, a reversion is going to trigger a significant squeeze
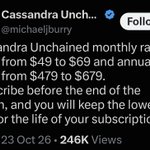
It's all over when the biggest permabear in the market is selling AND raising substack sub rates in a bear market
Isn't his net worth like, a couple of hundred million dollars?
This goes to show ... greed can never be satisfied

hiding from a super typhoon with a nice cup of hand brewed joe like how i've been taking cover from market volatility
stay safe folks

Hearing it's a problem amongst "token factories" in some parts of Asia

With all respect, this is the worst advice I'm hearing especially to FinX folks who are mostly retail/small indie funds/family offices (the large funds/pods are mostly here for the memes and momos)
Institutional funds short for two main reasons - to hedge (mkt/sector beta, idiosyncratic risks), or if they see frauds. Some long-only do index put overlays but most of them don't or can't short
Most hedgies keep a net long, if not neutral book because shorting is a hard game. There's borrow cost and potential losses are unlimited
What we are seeing in markets lately is de-grossing - i.e. unwinding of both long AND short positions, and overall reduction of book leverage
For folks (especially retail) who don't have access to the suite of instutitonal tools to hedge/short/manage risks, they may only have (and think) buying put options is their best option (pun)
But let's be real - up to 90% of retail options traders lose money. Reasons:
> they don't know how, or have the models to properly price volatility
> wide bid/ask spreads - friction cost is high unlike traded stocks
> time decay (theta)
Option trading is like gambling. With embedded leverage
The best thing to do given current markets?
Nothing
Scale down risks, if you need
Take a break. Log off. Go for a nice long walk or holiday. Spend time with your loved ones

Disagree. Re names like AAOI - a great short when things got crazy silly and it was 200+. But if shorting into weakness is your strategy you better have balls of steel and real conviction. In a bull market, buying the breakout/trend works well. In a bear market, shorting the breakdown in levered up / highly shorted names is how you die. You need to fade the countertrend rally.
Shorting the quality stuff and then occaisionally renting the high beta shitcos during short squeezes is much less likely to turn you into roadkill.
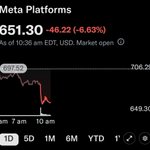
Tbf, $META reported good Q3
But creating a new non-voting share class to pre-empt future equity cap raises AND to let Zuckerberg pay wealth tax (if the motion is approved) for keeping his primary residence in California is no bueno
Meta isn't your piggy bank bro. You can move to Puerto Rico
And negative FCF, as anticipated
Credit spreads widening are signs that cap markets are cracking
$META

i have reasons to believe that market reaction to $META Meta's Q3 tomorrow is not going to be driven by revenue (still mostly ads anyway), expenses, margins or Muse
it's them turning FCF negative due to continuing capex ramp
questions will be asked about ROI on capital spend and Muse monetization
Quick pulse check: who do you think is likely to default first?
69%$CRWV CoreWeave
31%$ORCL Oracle
36 votes • Final resultsMeta announced what is technically a 100% stock dividend of Class C non-voting shares to be distributed to eligible Class A/B shareholders
They plan to use Class C stock as an optionality to raise equity for funding AI-related capex
How is this a positive thing?
On ex-date, Class A/B stock goes ex (50%) and the stockholders will receive Class C shares worth less than 50% of the split value - Class C stock will be worth less than Class A/B because it does not have voting rights
And stockholders' economic interests will be diluted with future equity capital raises
Hmm
$META
Breaking down SpaceXSI (Super Intelligence) numbers, which would $SPCX main growth driver for the coming quarters/years
■ Q3 revenue: $7.6B
■ Adjusted EBITDA: $5B
■ Nameplate compute capacity: 1.7 GW at end-Q3 (~2.2 GW by October, 2.5 to 3 GW by year end)
■ Backlog: $63B
■ ARR: $100B by year-end
Revenue is derived from Grok, Cursor, compute leases. Enterprise cloud customers include:
■ Anthropic ($45B over 3 years signed in May this year; ~$3.75B/qtr; recallable at notice)
■ Google
■ Reflection AI
And others (unnamed). Cursor will be an internal user of their compute too
Elon sees payback under a year with these parameters:
■ Cloud pricing slightly above a $30 to $50 per watt range
■ Compute allocation targeted at roughly a 50/50 internal and external split, rented at spot-like rates
To the last point, wonder how internal pricing works for Cursor. Charging them at spot rates doesn't sound quite right
DayOne weighing a delay or downsize of their IPO

There's been a deluge of negative press on neoclouds/co-los over the last weeks or so. Obviously some are idiosyncratic, but still, not a good look
Today: NextDC in Australia halted stock trading. Their 225MW M3 data center near Melbourne CBD faces a delay in power connection that is expected to have implications on their FY27 guidance
Oct 18: Microsoft pulled out of a data center deal with Nscale. The agreement terminated is for a data center in Loughton, Essex, due to delays in electrifying the project (the UK national grid had told Nscale they do not expect power connectivity for the data center until the 2030s)
Oct 14: Gartner's post on neoclouds (full report was dated Sep 14) on how >$3.5T of AI infra spending could be exposed to impairment by the end of 2030 if AI providers continue their current pace of capital spending. They also predicted that cost pressures and a lack of differentiating business models could force 80% of neocloud providers to cease independent ops by 2030
Oct 13: Airtrunk delays its Singapore REIT IPO
Oct 9: Firmus pulled their IPO after books closed (on concerns over high gearing, aggressive valuation + CG issues with one of the co-founders charged and jailed for insider trading when he was a stockbroker)
Then we have CoreWeave's credit secondaries getting dumped coupled with a surge in their CDS
DayOne's proposed IPO looks likely to be canned too - they are the primary development partner for Firmus' Southeast Asia projects (Batam, and KL in Malaysia)
BUSINESS INSIDER: Amazon is buying billions in Nvidia AI systems it can't yet turn on
businessinsider.com/amazon-n…
Key points:
■ Amazon (AWS) is expected to receive roughly $5B of GB300 racks at its US facilities before final deployment, according to August internal emails, under a new Early Rack Receipt process
■ AWS is projecting roughly $3B more in GB300 racks EACH MONTH “for the foreseeable future”
■ At least one AWS team said they did not have a “clear forecasted path” for getting the incoming racks into data centers
■ While some AWS sites had room for more racks, there’s not enough available power to turn them on. Finished equipment is staged at intermediary warehouses near the deployment sites so that they can install them once capacity becomes available
tl;dr –
We’re seeing a phenomenon of “dark GPUs” – where chips/racks sit idle while waiting for power
Pros: for AWS, they secure the chips/racks, sometimes ahead of competitors, even if some shells are not ready to be energized. For NVIDIA, they recognize the associated revenue when these chips/racks are delivered
Cons: AWS will start recognizing these systems on their books, as well as depreciation. There’s a mis-match in revenue/cash flow timing since these systems are not yet productive until they are powered to serve customers

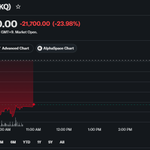
Holy smokes - NextDC
From Bloomberg:
Nextdc Ltd.’s shares plummeted after the data center operator said it was considering force majeure options and cut earnings guidance as community opposition delayed one of its major projects in Melbourne.
The Australian firm revised its earnings before interest, taxes, depreciation, and amortization for the current fiscal year through June 2027 to between A$245 million ($172 million) and A$265 million, down from A$385 million to A$410 million, in a statement Wednesday.

