

Co-founder / Partner at @OuriosAnalytics Full time Shipping and Commodities investor - No advice, do your own DD
Spain
Joined September 2021
- Tweets6.9K
- Following525
- Followers1.2K
- Likes5K




Shipping Up More retweeted

More than 100 shipping companies, shipowner associations and maritime registries have backed a call for international governments to pursue a "pragmatic" alternative framework at the International Maritime Organization's (IMO) talks in December, where discussions will resume over a proposed global shipping net zero framework (NZF).
IMO attempt to approve a first NZF draft in October 2025 failed to reach consensus after the US and Saudi Arabian delegations advocated against it and proposed an adjournment. The draft included a proposal for a global greenhouse gas (GHG) pricing mechanism. Proposals to tweak and reduce the stringency of this draft were circulated in MEPC talks in April, and gained some support. argusmedia.com/en/news-and-i…

Shipping Up More retweeted

Star Bulk ($SBLK) updated financial model is already available.
You can download the Excel model and play around with it, adjusting your own assumptions to build your own scenarios and valuations whenever you want.
Your assumptions. Your valuation. Your investment decisions.
ouriosanalytics.com


Frontline (NYSE: $FRO) – Q3 2026 Results
Another very strong set of numbers from Frontline, with an increasingly attractive outlook heading into Q4.
A few highlights from our updated model:
FY 2026 Adjusted EPS: $13.90
NTM Adjusted EPS: $15.58
NTM Adjusted EBITDA: $3.9bn
NTM Levered FCF: $3.48bn
NTM Adjusted P/E: just 2.87x
NTM EV/Adjusted EBITDA: 3.22x
NTM Dividend Yield: 37.36%
In addition, Frontline is expected to take delivery of its final three VLCCs in Q4, completing the January 2026 order. These vessels are arriving at an exceptionally favourable point in the tanker cycle, with VLCC rates at very attractive levels. Frontline should be in an excellent position to capitalize on this additional capacity.
And the Q4 rate guidance is particularly encouraging, reinforcing the strong earnings potential ahead.
A fully updated financial model is available at ouriosanalytics.com; most importantly, you can easily input your own assumptions
#Tankers

Shipping Up More retweeted

BREAKING: Iran has crewed and loaded up dozens of tankers at Kharg, hoisted the Iranian flag on them, and is preparing to break the U.S. naval blockade, per Fars News
In the coming days, these vessels will transmit their intention to exit the Gulf of Oman unhindered.
Iran has reportedly informed the U.S. and regional countries that any attempt to interfere with the movement of the tankers will result in a harsh response, which means that the war will begin.

Shipping Up More retweeted
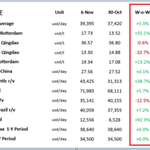
Looking at the WoW figures (red column), it's easy to get nervous about the recent correction in tanker rates.
But take a closer look at the actual earnings levels (blue column).
Even after the pullback, these are extraordinary TCE levels. The spot market is still generating remarkable cash flows across all three segments.
A correction in rates? Absolutely. A weak tanker market? Not even close
Got #tankers
Source: Banchero


Shipping Up More retweeted

A small detail that I like is that this comes from $PAAS, a high quality company that is likely to have run a high quality mill but perhaps not have had maximum focus on replacing ounces in this for them small mine when gold was 1800 usd 2022.
I suspect this will turn out to be a steal...
A second thing is that it will further add scale for $CERT.v in Argentina. A subject I suspect we will have to re-visit coming years.
Cerrado Gold is a massive growth story under the radar. Key holding for me where I recently met management in Stockholm.

News Alert: Cerrado Gold ($CERT, $CRDOF) Acquires the Past-Producing Manantial Espejo Mine in Santa Cruz, Argentina, from Pan American Silver. Read full release here: bit.ly/CERTAcquire #gold

Shipping Up More retweeted
cerradogold.com/news-media/n…
😍 😍
The production from $CERT.v vs mcap was already out of whack... Now this ...
Very important to simply check the mcap and see what we get for that.. Imo only a matter of time for them to re-rate

United Maritime ($USEA) doubles its quarterly dividend to $0.20/share!
If maintained, that's an annualized divi yield of around 26% at current prices.
Growing Capesize exposure, improving earnings and a very interesting shareholder return profile.
Source: @OuriosAnalytics.
United Maritime ($USEA), Seanergy Maritime's spin-off, has just released its Q3/26 results, and there is some very interesting news for shareholders!
The company has DOUBLED its quarterly dividend to $0.20/share.
If maintained at this level, this would translate into an annualized dividend yield of approximately 26% at current share prices. Quite remarkable!
Even more interesting is its strategic repositioning towards Capesize vessels. Its two operating Capesizes are already fixed for 2027 at rates exceeding $35,000/day and $29,100/day, respectively, providing substantial earnings visibility.
With a third Capesize expected to join the fleet in early 2027, the company is increasingly positioning itself to benefit from the positive outlook for the dry bulk sector.
A 26% potential dividend yield combined with growing Capesize exposure certainly makes United Maritime worth watching.
Our updated valuation model is now available on the Ourios Analytics platform.
Explore our financial projections, vessel valuations and different market scenarios by making your own assumptions.
ouriosanalytics.com
338
Seanergy Maritime ($SHIP): strong results, a higher dividend and an ambitious fleet renewal programme.
At around 0.64x NAV, with around 10% dividend yield and trading below 3x NTM EV/EBITDA, we believe it deserves attention from Capesize investors.
Source: @OuriosAnalytics
Seanergy Maritime ($SHIP) has released its Q3/26 results, delivering another very strong quarter.
Q3 fleetwide TCE reached $34,266/day, up 46% YoY, while adjusted EBITDA increased to $40.8M. Nine-month net income reached a record $61.9M.
One particularly positive development is the increase in the quarterly dividend from $0.35 to $0.40/share, bringing the annualized dividend yield to approximately 10% at current share prices.
Seanergy is also continuing its fleet renewal programme, with an ambitious investment plan involving 12 Capesize and Newcastlemax vessels, including nine newbuildings and three modern Japanese-built secondhand vessels.
Looking at our model, at a share price of $15.58:
Q4/26 NAV: $24.16/share (P/NAV 0.64x)
Q1/27 NAV: $25.19/share (P/NAV 0.61x)
NTM Adjusted P/E: 3.36x
NTM EV/Adjusted EBITDA: 2.91x
NTM P/FCF: 2.55x
NTM Dividend Yield: 10.27%
In our view, Seanergy offers an attractive combination of dividend income, a significant discount to NAV and exposure to the Capesize segment. If you like to invest in Capesize segment, this is certainly a company worth keeping an eye on.
Our updated valuation model is now available on the Ourios Analytics platform.
Today, we will also be updating our model for United Maritime ($USEA), Seanergy's spin-off, whose shares surged 22% yesterday. Quite a move!
Explore our models and make your own assumptions.
👉 ouriosanalytics.com


Outstanding Q3 results from Teekay Tankers ($TNK)!
A massive liquidity position and an Adj. EV/EBITDA close to zero.
The only disappointment? A quarterly divi of just $0.25/share.
With this cash generation, we believe shareholders deserve much more.
@OuriosAnalytics
Teekay Tankers ($TNK) has just released its Q3/26 results, and the numbers are outstanding.
The company reported adjusted net income of $175.8M, adjusted EPS of $5.04 and adjusted EBITDA of $188.4M.
And the outlook is even more impressive. Q4 spot rates are already reaching extraordinary levels, with Suezmaxes averaging $272,000/day and Aframax/LR2s $208,300/day on booked days so far.
At current valuations, our model points to an Adjusted EV/EBITDA multiple practically close to zero, reflecting the company's enormous net cash position and strong earnings generation.
However, there is one aspect we find rather disappointing: shareholder remuneration.
With around $1.5 BILLION in cash, cash equivalents and short-term investments, we believe the current quarterly dividend of just $0.25/share is remarkably conservative.
Given the company's enormous liquidity position and the cash generation potential of the current tanker market, we would certainly like to see a much more aggressive approach to shareholder distributions.
Our updated Teekay Tankers valuation model is now available on the Ourios Analytics platform.
Explore our financial projections, vessel valuations and different market scenarios by making your own assumptions.
👉 ouriosanalytics.com

1
7
561
Okeanis ($OET, $ECO) is playing in a league of its own!
Insane Q3 TCEs, with Q4 potentially reaching even more extraordinary levels.
And what can we expect for Q1/27? Given what Okeanis has accustomed us to, that's the interesting question!
Updated model at @OuriosAnalytics
Okeanis Eco Tankers ($OET, $ECO) has released its Q3/26 results, and the TCE figures are simply insane!
VLCCs achieved an average TCE of $260,100/day in Q3, while Suezmaxes reached $166,600/day.
And Q4 looks wild, that is what we were expecting.
During Q3, the company also secured short-term employment for five VLCCs at an average rate of $449,200/day, for 100-150 days.
So, with Q4 potentially reaching unprecedented levels, the next question is: what can we expect for Q1/27?
Even assuming a significant moderation from Q4 levels, these would still represent exceptional earnings.
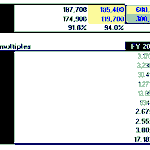
With rates you can see in the screenshot, at current valuations, our model indicates approximately 2.2x NTM Adjusted P/E, 2.4x EV/Adjusted EBITDA and 2.1x P/FCF, with a potential, great and amazing dividend yield approaching 50%... I’m not sure if we realize it, but we could be looking at a dividend of around $15 for the next quarter 🤪🔥🤑
Okeanis continues to demonstrate why it is one of the most impressive operators in the tanker industry.
Our updated valuation model is now available on the Ourios Analytics platform. You can acquire them and try to make your own assumptions to guess what Okeanis’s rates will be, but the only thing you can be sure of is that they will always be the best.
It´s funny to explore different scenarios and make your own assumptions.
👉 ouriosanalytics.com

1
32
1,569
Shipping Up More retweeted
Eurodry ($EDRY) released its Q3/26 results.
We have just updated our valuation model, and it is now available on the Ourios Analytics platform.
Explore the company's valuation, financial projections and different market scenarios by making your own assumptions.
👉 ouriosanalytics.com
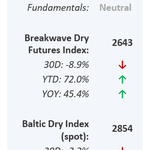
Breakwave Dry Bulk Shipping
Bi-Weekly Industry Report
November 10, 2026
static1.squarespace.com/stat…

1
278
Panama Canal turns the taps back on
splash247.com/panama-canal-t…

2
372


Another strong quarter from Himalaya Shipping ($HSHP).
As I’ve mentioned on a few occasions, this monster is one of our favorites.
Updated valuation model already available at ouriosanalytics.com
Himalaya Shipping ($HSHP) has just released its Q3/26 results, delivering another very strong quarter.
Average TCE earnings reached $58,400/day, with net income of $33.3M and EBITDA of $52.7M. October TCE earnings remained strong at approximately $50,900/day.
The company continues to demonstrate its ability to outperform the Capesize market, supported by its modern Newcastlemax fleet and long-term index-linked charters with significant premiums over the Baltic 5TC.
At current valuations, the stock trades at around 7.9x NTM Adjusted P/E, 7.9x EV/Adjusted EBITDA and 6.1x P/FCF, while offering a potential dividend yield of approximately 13.3%.
Himalaya also continues to reward shareholders through its monthly cash distributions, having declared $0.75/share for Q3 and another $0.20/share for October.
Our updated valuation model is now available on the Ourios Analytics platform.
Explore our financial projections, vessel valuations and different market scenarios by making your own assumptions.
👉 ouriosanalytics.com
#shipping #drybulk

10
431