

Chief DCF manipulator, market investigator and fundamental chartist. ACCA, CISI. Dynamic asset allocation. Not financial advice.
quickfs.org
Joined January 2016
- Tweets6.5K
- Following365
- Followers2.9K
- Likes5.1K
Dude still can't settle with $SIVE after squeezing subscribers with this hype nonsense at 100. Yes, still 4x on 1Y, but those who bought at 100? Minus 75%, close to complete wipeout.
А где здесь Мальта? И почему Россия воздержалась от голосования за эту резолюцию? Должна же была против голосовать по твоей логике. А вообще твой комментарий это манипуляция. От ответственности не уйдешь 😉. Вернемся к теме, умылся кровью сегодня или пока нет, сочинец?

First 100 USD made. That's 10% in less than 2 months. This war will only stop if one of the parties falls. Ukraine will not fall any time soon, because they have Western support. Russia will not fall because, in a war of exhaustion, they still have capacity.
I look at it as high risk / high reward bet. Very similar to the stock market, where we are placing bets on companies. Will bring it to 10% of the portfolio by the end of the year.


$PG VALUATION MODEL
Procter & Gamble has raised its dividend for 70 years in a row. Tide, Pampers, Gillette, Oral-B - chances are you used one of its brands before breakfast. It is about as close to a bond with a logo as the stock market gets. At USD 151, my DCF says investors are paying roughly 14% more than the cash flows are worth. Great company. Wrong price? Let's run the numbers.
KEY ASSUMPTIONS:
* Explicit average 5Y/5Y revenue growth @ 2.6%/2.8%
* Long-term growth in perpetuity @ 2.5%
* Adj. EBITDA margin expanding from 26.3% to 28.5% by Year 10
* WACC @ 7.4%
* Adj. EBITDA exit multiple of 14.8x
* Tax rate 20.85%, the marginal rate
* The input that drives reinvestment is the marginal Sales to Capital ratio of 2.63, held constant through Year 10

Portfolio update – September 2026
CL Sept - 2.28%
SP500 Sept - 0.35%
CL YTD - 1.2%
SP500 YTD +12.7%
My portfolio slightly underperformed S&P index in September. The main laggards were a few growth stocks (Eose, Jobe, OCGN) which I bought earlier this year because I thought they could deliver decent returns. This unfortunately didn’t happen yet, however the impact on portfolio was limited since I gave those positions only a small fraction. TLT and SPHD were also down -3% and -4% respectively, and this had larger impact on underperformance. TLT and SPHD declined in September 2026 largely because US Treasury yields rose sharply. This illustrates an important portfolio-construction risk: long-duration government bonds and defensive dividend stocks are not necessarily good diversifiers against each other. Both can suffer substantially when long-term real yields or term premiums rise. For my portfolio, this is also a reason why I keep short-duration government bonds such as $SHY, PRAB and BIL - they behave differently. They have much lower duration risk and is therefore less vulnerable to the same bond-market repricing.
Transactions
➖ Disposed $NVO, $BTDR, $PDD, SYM, RZLV, BETS as part of a portfolio de-risking. Accumulated losses on these positions were locked in, and proceeds reinvested into more conservative stocks.
➕ New entry in IMB, STZ, HONA, AZO, BKNG, FICO. Those are visibly more prominent names and based on my DCF models they seem to be undervalued at the moment.
Stress test
I have built a portfolio that is designed to endure a market collapse of any size, including a depression similar to 1929.
If S&P500 collapses by 50%, my portfolio is expected to drop by 24%. A mix of low-risk assets, such as government bonds, along with undervalued defensive stocks, will provide the necessary cushion while still generating decent returns to preserve purchasing power. When a bear market kicks in, I want to go shopping instead of leaking wounds. This opportunity unfortunately comes at a cost. If I had kept 100% in an S&P index fund, my return would be 14% higher YTD. I do acknowledge this cost, but at the same time I do not plan to make any changes in my strategy. I feel more comfortable with buying government bonds at a 5% yield than buying the S&P 500 at 40 CAPE.
Holdings as of 10/10/2026
BIL 16%
PRAB13%
Cash7%
SHY7%
TLT 4%
FTSL4%
BKLN4%
IEI 3%
BKNG3%
USMV3%
VGT3%
SPHD3%
LQD3%
NVDA2%
WKL2%
AZO2%
PYPL2%
MSFT2%
Other 18%
What is my portfolio trying to achieve?
Capital preservation
The 45% allocation to cash and short/intermediate Treasuries ($BIL, $SHY, PRAB) provides liquidity and relative stability. It also gives me the flexibility to increase equity exposure after a market correction.
Income generation
FTSL, $BKLN, $LQD and $SPHD aim to generate income. FTSL and BKLN provide floating-rate corporate loan exposure, but they carry credit risk, particularly during recessions.
Selective capital appreciation
$BKNG, $MSFT, $META, $NVDA, $AZO, WKL and FICO provide exposure to businesses with competitive advantages and long-term compounding potential. PYPL, LULU and OTIS introduce more turnaround, recovery or valuation-re-rating exposure.
Asymmetric growth opportunities
OCGN, EOSE, IONQ and JOBY together represent just 4%. I retain exposure to potentially transformative technologies without making the entire portfolio dependent on speculative outcomes.
So yes, capital preservation is my highest priority right now. I hope to achieve this by combining systematic exposures (USMV, VGT, SPHD, MVOL) with individual stock selection (core-and-satellite philosophy, although the fixed-income and liquidity positions are effectively my largest core).
The main trade-off is the possibility of underperforming during a prolonged equity bull market, as we are already witnessing in 2026.
Breakdown by sector/asset class
Cash and equivalents – 42%
Bonds ETF – 18%
Technology – 8%
Low volatility ETF – 7%
Industrials – 7%
Consumer Cyclical – 7%
Consumer Defensive – 4%
Healthcare – 2%
Financial – 3%
Communication – 2%
This wraps up the September performance.
Thanks for reading.
CL.

Full list of my Polymarket positions. Current stage: accumulating.
Today, Trump is saying once again that Ukraine-Russia war will end soon.
The reason why he is saying this is a mix of real diplomatic activity + deliberate pressure/optimism, rather than because there is public evidence that a full ceasefire is already close.
Trump has been saying versions of this for months. On July 6 he said the war was “getting closer than people realize,” after speaking separately with Putin and Zelenskyy. Reuters noted at the time that Trump gave no specific reason for that confidence.
Then at the UN on September 22 he again said he thought an end would come “more quickly than people understand.”
There are nevertheless a few concrete reasons why he may genuinely think the situation is moving.
First, US diplomacy restarted in September after roughly six months of stagnation. Witkoff and Kushner visited Moscow and Kyiv, and Washington has been discussing a new “peace package.” Russia, Ukraine and the US have also accepted in principle the idea of another trilateral round of talks.
Second, Trump seems to believe that both sides are under increasing pressure. Ukraine has inflicted serious damage on Russian energy infrastructure, while Ukraine itself faces another difficult winter and remains heavily dependent on Western military and financial support. That creates incentives on both sides to explore at least limited agreements. Trump has explicitly been pushing an energy ceasefire as a possible first step.
Third, Trump appears to think he has leverage over Russia economically. His administration is simultaneously discussing sanctions, energy issues and potentially substantial future US-Russia commercial relations. The Kremlin itself said Trump told Putin that ending the war could open the way to a major restoration of US-Russian economic ties.
Recent reporting also says US-Russia discussions have touched on a multibillion-dollar oil transaction.
But there is a major contradiction: Putin's public and reported private positions don't currently look like those of someone preparing to sign a general ceasefire immediately.
Reuters reported in July that people close to the Kremlin said Putin was rejecting compromise and still wanted control of the remainder of Donbas; one source said he had rejected advisers' suggestions for a ceasefire along the existing front. And as recently as 1 October, Putin rejected the proposed exchange of limits on long-range/energy attacks, while saying Russia still preferred an eventual negotiated end.
Today, October 6, Ukraine is also warning that Russia appears to be preparing another major aerial attack.
Therefore, we should interpret Trump's wording approximately like this:
~40% genuine belief based on private conversations that there is a negotiable landing zone;
~30% negotiating tactic - publicly saying agreement is close can put pressure on Putin and Zelenskyy to behave as though it is;
~20% domestic politics/economics - Trump badly wants lower energy prices and a visible foreign-policy success;
~10% Trump's normal tendency to express very optimistic timelines.
Those percentages are my judgment.
For my Polymarket ceasefire-agreement positions, I don't treat Trump's statement alone as strong evidence that a qualifying agreement is imminent. I would become much more bullish on YES if we saw one of these concrete developments: Russia accepting the principle of a general ceasefire, a Putin-Zelenskyy/Trump summit with an actual ceasefire text under discussion, negotiators beginning work on a dated frontline-wide halt, or Kremlin language shifting from “root causes first” toward “ceasefire first.”
At the moment, Trump's rhetoric is noticeably more optimistic than the observable Russian negotiating position. That gap is the most important thing I keep in mind.
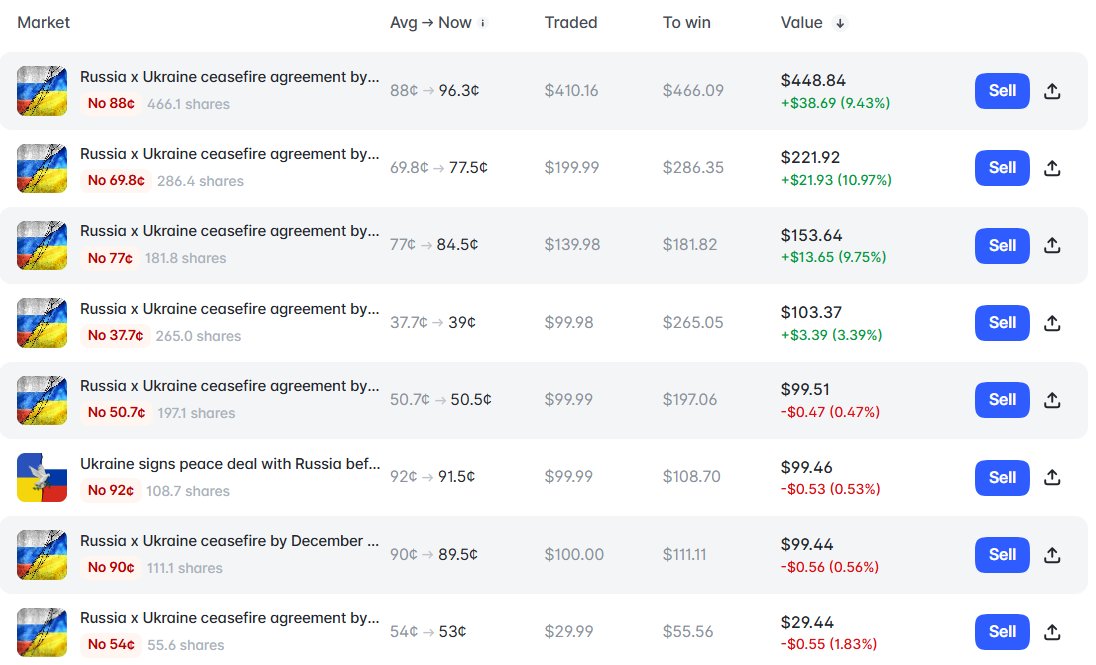
17% in just one month. I do not believe in a quick ceasefire between Ukraine and Russia. To evaluate my position, I check how many new contract soldiers Russia recruits monthly, and this trend tells me they do not have any intention of stopping anytime soon. I can be wrong - it's politics and everything can change fairly quickly. Therefore, do not copy my trades. It is a very small share of my total portfolio.


$PEP VALUATION MODEL
Today, PepsiCo is not an average stock. It’s protection against a major market meltdown. Lay's, Doritos, Gatorade, a dividend yield of 4.7%, and an impressive 54 years of continuous dividend increases, all at the bottom of its 52-week range, down about 36% from its peak. Its standard deviation of price return is the lowest in the Morningstar Wide Moat universe, indicating that its price tends to bounce back to its fair value relatively quickly. So, what exactly is that fair value today? Let’s find this out together.
KEY ASSUMPTIONS:
* Average revenue growth of 3.5% in Years 1-5 and 2.8% in Years 6-10
* Long-term growth in perpetuity of 2.5%
* Adjusted EBITDA margin rising from 19.1% to 20.1% by Year 10
* WACC of 6.7%
* Terminal adjusted EBITDA exit multiple of 12.3x
* Tax rate of 22%, broadly in line with PepsiCo’s core effective tax-rate guidance for 2026
* Marginal Sales/Capital ratio of 1.43 for growth reinvestment
Sharing full workings on my Substack later today.
