

$13M NW | fatFIRE | Peter Lynch 2.0. Long term investor, chasing deep value baggers. Ex-Senior Exec Tech/SV. Building agentic equity research platform. e/acc
Bahamas
Joined February 2024
- Tweets28K
- Following626
- Followers57.2K
- Likes35.4K




Pinned Tweet
This portfolio journey started with all-in $ASTS and kickstarted 1430% in my IRA account.
> I bought in Covid era SPAC around $10.
> In 2023, I watched it drop to $3ish, and I scheduled weekly buys of $ASTS to accumulate for 6 months.
> By Oct 2024, I decided that $RKLB was the better company, and better valuation, I switched 100% over $RKLB around $5ish and higher. (sold $ASTS in 30s).
> I switched half to $CRCL at IPO mid 2025, then to $IREN at $20.
> By early 2026, I switched half to $INTC calls (~$30-50).
> Sold all $INTC calls when stock price hit $100, and bought $NBIS
> In May, I sold all of my $RKLB before SpaceX IPO and bought $MU and $NBIS.
When I shared my ASTS vs RKLB after I made the switched, people said I was wrong, stupid whatever.
When I shared why I sold my IREN for NBIS, people called me stupid too.
When I bought MU, people were telling me that memory is a commodity, and cyclical.
And here are my gains...

Israel's election ends on Oct 27, result on Nov 4.
US Mid term election ends on Nov 4.
It would make sense that Iran war is conveniently extended past the election to maintain the voting issues around Iran.
I'm an investor both $SPCX and $TSLA and fan of Elon. However, as an investor, I've been used to his hyperbole for a while. It was difficult for me to see but I got out of it $TSLA early this year.
Tesla has lost 2 models, Model S and Model X, and we don't have 2nd gen cybertruck or full size SUV, or a van. It's nearly end of 2026 and we haven't seen Optimus yet.
Recently, Elon promised 13GW 2027. I'm going to call bullshit on that. SpaceX's AI/DC capacity is 100% terrestrial. There's no way to scale that much capacity terrestrial, so let's presume, he will do it in space.
A. He couldn't acquire that 13W compute from Nvidia, that is not physically possible.
B. The engineering it takes to get the cooling and power production right will take more than a year. You need like a football field size solar panel deployment. Not even sure how he could source that much solar panel either. Even if you take 1/4 football field, it's a big scale to build process out.
C. He's going to deal with all kind of cooling problems, produce power consistently. Terrestrial DC system took 30 years to get all of this right. Granted you build off what is done terrestrially, it takes at least a year to do right at best with how fast you design, build and test.
Now why is he shitting on Neocloud... I don't think he would acquire them, it's just not his style, and it gets really messy dealing with a dozen acquisitions and their employees. I don't know. Maybe after he just raised $50B for $SPCX, the banker said, "Elon, btw do you mind just fudding on neodc for us". Elon: "Sure, that's what good friends do."

Glad to see $nbis ceo is ahead of the game.

NBIS CEO: “From last week, probably some of the capital sources are temporarily closed, like asset backed or debt market, but we’re working now with customer advances and several other instruments which will probably provide us enough finance to build this gigawatt at least.” $NBIS $IREN $CRWV $NVDA $ORCL $SPCX @elonmusk
youtube.com/watch?v=ElxZFG9l…


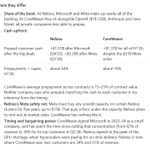
Nebius’s two anchors are cash-rich Microsoft and Meta.
CoreWeave’s growth customers (OpenAI, Anthropic, Jane Street) are private and depend on raising money themselves, so they’re less able to prepay. CoreWeave’s 10-Q says it is adding customers that “may have increased risk of insolvency,” and it carries no credit insurance.
$NBIS $CRWV


The market is brutal. Revenue slowdown then a new competitor shows up. $crdo
I exited a month ago. Didn't like the uncertain and high expectations.

⚡ 𝐔𝐏𝐃𝐀𝐓𝐄: $CRDO Credo Shares Fall 7.5% as MaxLinear Targets 30% of 1.6T AEC Market
👉 𝗞𝗲𝘆 𝗛𝗶𝗴𝗵𝗹𝗶𝗴𝗵𝘁𝘀:
➤ 𝗖𝗿𝗲𝗱𝗼 𝗧𝗲𝗰𝗵𝗻𝗼𝗹𝗼𝗴𝘆 shares declined 𝟳.𝟱% amid rising competitive concerns.
➤ 𝗠𝗮𝘅𝗟𝗶𝗻𝗲𝗮𝗿 estimates Credo controls 𝟵𝟯%–𝟵𝟵% of the AEC market.
➤ MaxLinear targets 𝟮𝟬%–𝟯𝟬% of the 𝟭.𝟲𝗧 𝗔𝗘𝗖 market.
➤ MaxLinear plans to supply 𝗔𝗘𝗖 𝘀𝗶𝗹𝗶𝗰𝗼𝗻 rather than complete cables.
➤ 𝗘𝗱𝗴𝗲𝘄𝗮𝘁𝗲𝗿 𝗥𝗲𝘀𝗲𝗮𝗿𝗰𝗵 sees limited near-term 𝟭.𝟲𝗧 𝗔𝗘𝗖 adoption.
➤ 𝗖𝗶𝘀𝗰𝗼 reportedly seeks quotes for 𝟭𝟬𝟬,𝟬𝟬𝟬 cables monthly.
➤ 𝗕𝗿𝗼𝗮𝗱𝗰𝗼𝗺 or MaxLinear could supply Cisco's 𝗔𝗘𝗖 𝘀𝗶𝗴𝗻𝗮𝗹 𝗽𝗿𝗼𝗰𝗲𝘀𝘀𝗼𝗿𝘀.
➤ 𝗔𝗺𝗽𝗵𝗲𝗻𝗼𝗹 and 𝗧𝗘 𝗖𝗼𝗻𝗻𝗲𝗰𝘁𝗶𝘃𝗶𝘁𝘆 could manufacture cable assemblies.
➤ 𝗔𝘀𝘁𝗲𝗿𝗮 𝗟𝗮𝗯𝘀 poses potential competition in future custom AI platforms.
➤ 𝗜𝗻𝘀𝗶𝗱𝗲𝗿 𝘀𝗲𝗹𝗹𝗶𝗻𝗴 added pressure amid concerns over delayed 1.6T adoption.
👉 𝗪𝗵𝘆 𝗧𝗵𝗶𝘀 𝗠𝗮𝘁𝘁𝗲𝗿𝘀:
➤ Credo's dominant 𝗔𝗘𝗖 𝗺𝗮𝗿𝗸𝗲𝘁 𝘀𝗵𝗮𝗿𝗲 could face competitive erosion.
➤ Slower 𝟭.𝟲𝗧 𝗮𝗱𝗼𝗽𝘁𝗶𝗼𝗻 could delay expected AI connectivity revenue growth.
➤ Growing competition could pressure Credo's 𝗽𝗿𝗶𝗰𝗶𝗻𝗴 𝗽𝗼𝘄𝗲𝗿 and profit margins.
➤ Cisco's potential sourcing strategy could benefit 𝗕𝗿𝗼𝗮𝗱𝗰𝗼𝗺, 𝗠𝗮𝘅𝗟𝗶𝗻𝗲𝗮𝗿, and cable manufacturers.
👉 𝗘𝘅𝗽𝗲𝗿𝘁 𝗦𝘁𝗮𝘁𝗲𝗺𝗲𝗻𝘁:
𝗞𝗶𝘀𝗵𝗼𝗿𝗲 𝗦𝗲𝗲𝗻𝗱𝗿𝗶𝗽𝘂, CEO of MaxLinear:
The source attributes market-share estimates and competitive targets to Seendripu but does not provide a direct quotation. He estimates Credo's AEC market share at 93%–99% and says MaxLinear aims to capture 20%–30% of the 1.6T AEC market over the next few years.


The biggest 0 to 1 for the retail investor is to have enough investment income to quit being a wage slave.
> Knowledge & direction to invest
> Time to manage investment
> Capital to invest
> Market bullshit (like right now)
> 40%-50% capital gain dragging you down.
> Living costs, supporting family
Once you make have enough investment income, you have enough capital to scale up faster 1...N.
It's not easy, we're here.


My contrarian take on $NBIS $3.5B loan is it's bearish. The interest rate is really good which I give the team credit for.
But it may be a signal of credit crunch as it couldn't be a 5 year loan. This is equivalent getting credit line loan. NBIS team might be hedging for better conditions a year later.