

Event-driven platform focusing on Special Situations
San Francisco Bay Area
Joined January 2021
- Tweets13K
- Following733
- Followers6.5K
- Likes2.6K



Pinned Tweet
Unlock the secrets of event-driven investing with Asif Suria's "The Event-Driven Edge in Investing"

Instacart $CART Considers a Potential Sale - Bloomberg @markgurman
🥕Instacart has explored a potential sale of the grocery-delivery company, a process that has included discussions with Uber Technologies $UBER.
🥕Though Instacart recently shopped itself to Uber, the ride-hailing giant walked away, and the two sides are no longer in discussions.
🥕Instacart also held preliminary talks with DoorDash $DASH as part of a potential sale process, the Information reported.
🥕Instacart, which trades as Maplebear, has been working with an investment bank to evaluate its options.

ALT Instacart Considers a Potential Sale
InsideArbitrage retweeted

US buybacks are set to rise to unprecedented levels:
US buyback authorizations are up +13% YoY so far in 2026, to a record $1.305 trillion.
Buyback authorizations are now on track for their 4th consecutive annual increase, the longest such streak in at least 20 years.
Since the 2020 low, buyback authorizations have more than quadrupled.
Meanwhile, executed buybacks grew +20% YoY in Q2 2026, their largest increase since Q1 2025.
This also marks the 4th consecutive quarterly increase, with H1 2026 up +15% year-over-year.
We expect a large wave of US stock buybacks ahead.

InsideArbitrage retweeted

$SKYD: JPMorgan's new 52-page report on Skydance is worth reading. The assets are impressive. The balance sheet is another story.
Following the $WBD acquisition, Skydance is now one of the world's largest media companies, with $66B in projected revenue, more than Netflix's $51B. But Netflix generates considerably more EBITDA ($17.1B vs. $12.2B).
The key takeaways:
📺 Linear TV remains the cash cow. Roughly 84% of 2025 pro forma EBITDA came from traditional television. JPM forecasts linear EBITDA declining nearly 7% annually through 2030.
💰 Debt is the biggest concern. $86.8B in gross debt, approximately $6.2B in annual interest expense and 6.1x net leverage. Little room for execution mistakes.
🔧 Synergies are the entire investment thesis. Management targets $6B+ in annual savings. JPM believes the savings are achievable but expects half to be reinvested, leaving just $3B in incremental EBITDA.
📈 Streaming has real upside. Paramount+ and HBO Max have only 7.5M overlapping U.S. subscribers. Bundling, pricing and international expansion offer meaningful opportunities. JPM sees streaming EBITDA growing from $2.8B in 2026 to $5.9B by 2030.
🎬 Studios are arguably the crown jewel. Paramount and Warner Bros. control more than 60 franchises, with roughly 25% of the domestic box office. But the merger requires an aggressive theatrical release schedule, increasing execution risk.
The valuation is interesting. SKYD trades around 8x 2028 EBITDA. JPM's $9 target implies ~15% upside, but its sensitivity analysis suggests every additional $1B in recurring net EBITDA from synergies adds roughly $1.80 per share in value.
Management targets $10B+ in 2030 FCF. JPM models just $7.3B.
My takeaway: Skydance doesn't lack scale, franchises or growth opportunities. It lacks financial flexibility. The bull case isn't simply that management finds $6B in savings. It's that those savings actually reach earnings and translate into FCF rather than being consumed by declining linear TV, higher content spending and integration costs.
This is a leveraged media turnaround, not a cheaper version of Netflix.
🏦 First Citizens shares are up premarket as the bank reported Q3 results (double beat) and approved a $1.2 billion share repurchase plan through 2027
$FCNCA is a cannibal among large regional banks
The company bought back $600 million of stock in Q3, after repurchasing $600 million in Q2
And this new authorization is additive.
As of September 30, First Citizens still had $711 million remaining under its existing 2025 repurchase plan, bringing total available capacity to $1.9 billion
Since launching its 2024 program, First Citizens has already reduced its combined Class A + Class B share count by more than 20%.
The buyback comes alongside a quarter that management says exceeded expectations, driven by strong top-line growth, accelerating loan and deposit growth, resilient credit quality and expense discipline.
Chairman & CEO Frank Holding also highlighted that First Citizens returned $600 million through repurchases in Q3 while simultaneously repaying another $8 billion of its Purchase Money Note
We also had $FCNCA in our Model Portfolio for a little under two years and exited the position in January 2026 with a 114.5% gain
$FCNCA

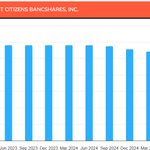
ALT $FCNCA - Change in shares outstanding
InsideArbitrage retweeted

🟡 NEW:The SpaceX-Tesla merger could face antitrust scrutiny
semafor.com/article/10/23/20…

A meaningful buyback expansion, a recent director purchase, and a CFO with relevant industrial-product experience - all happening around the same time...
🚰 Mueller Water Products boosted its share repurchase authorization by $300 million, which is roughly 9% of its current market cap.
That comes with a couple of other interesting signals at $MWA
Director Brian Healy recently bought 1,376 shares at $21.75 for $30,000
There’s also a CFO transition underway
Michael Morgan joins on October 28 as EVP, Finance and is expected to become CFO around November 19 after Mueller files its fiscal 2026 10-K. He comes from Indicor, where he was CFO of a portfolio of industrial businesses spanning pumps, valves, sensors, meters and measurement equipment - a background that lines up unusually well with Mueller’s own water-infrastructure product mix.
And Mueller has the balance-sheet capacity to act
As of June 30, it had about $495 million of cash against roughly $453 million of debt, while year-to-date operating cash flow had improved to $154 million
$MWA

ALT $MWA - IA Score
🌱 Global seed and genetics company Vylor authorized a new $3 billion multi-year share repurchase program, roughly 6% of its current market cap, in less than a month after becoming an independent public company
$VYLR was spun out of Corteva $CTVA on October 1, with shareholders receiving one Vylor share for every Corteva share they owned.
What makes this interesting is how quickly capital allocation is becoming part of the post-spin story.
Vylor generated $9.9 billion in revenue in 2025 and is the larger, higher-margin business that emerged from the Corteva separation. It owns the Pioneer seed franchise and sells seed/genetics technology in more than 70 countries
The company says the $3 billion authorization is consistent with the capital-allocation framework outlined at its September Investor Day.
That framework is not just about buybacks.
Vylor also expects to pay a quarterly dividend starting in Q4 and is targeting dividends equal to roughly 15% of annual operating cash flow, while continuing to fund R&D and growth initiatives.
And there is a potentially important growth angle behind all of this.
Vylor says it is evolving from a traditional seed company into a higher-margin genetics and IP platform, with licensing expected to become an increasingly important driver of earnings. Management expects licensing revenue to reach about $1 billion by 2035 and potentially $2 billion by 2040.
Vylor is beginning life as a standalone company with three things investors usually like to see after a spin: a cleaner business model, identifiable growth catalysts and an aggressive capital-return framework
The timing is also notable: its first standalone quarterly earnings report is due November 11, so we should soon get a better idea of how quickly management intends to actually use that $3 billion authorization
insidearbitrage.com/symbol-m…
$VYLR

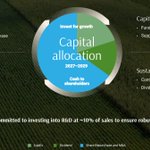
ALT $VYLR - Capital Allocation (2027-2029)
🧬 Medpace authorized a new $1 billion share repurchase program through the end of 2028
That brings me back to our 2025 Buyback Wednesdays article on $MEDP
📈 Medpace was trading around $288 at a forward P/E of 24 when we wrote it in May last year. Today it trades around $662 at 35x forward earnings
Our conclusion at the time was cautious:
“If and when this biotech nuclear winter ends, Medpace could turn out to be an attractive way to play a rebound in this sector.”
🟢The thesis played out. 🔴We missed on it.
One person who showed much more conviction was Medpace founder and CEO, August Troendle
Over just three days in September 2022, Troendle bought 245,664 shares for roughly $38.7 million at a weighted-average price of about $157.50
At today’s ~$662 share price, that position has appreciated more than 300%.
It is another reminder of why insider activity can be so useful: the founder who has run Medpace since 1992 was willing to put significant additional capital behind the company when the stock and biotech environment were under pressure
And the improvement is now showing up clearly in Medpace’s numbers.
📈 Four straight quarters of net new business award growth:
Q4'25: $736.6M, +39.1%
Q1'26: $618.4M, +23.7%
Q2'26: $795.7M, +28.2% (1.13x book-to-bill)
Q3'26: $873.4M, +10.6%
Backlog increased 5.6% to a record $3.17 billion. Revenue grew 8.5% and EBITDA increased 16%.
The biotech funding winter that worried us in 2025 has clearly thawed, and Medpace has benefited
Now the board is doubling down on capital returns
Medpace has also repurchased roughly another 6% of its outstanding shares since our last writing
The old authorization still had $527 million remaining, but Medpace terminated it and replaced it with a fresh $1 billion authorization, funded from cash on hand
A good reminder that sometimes you can correctly identify the catalyst, the company positioned to benefit, and still fail to act
We’re opening our original 2025 Medpace Buyback Wednesdays article for everyone
Free article linked below👇
insidearbitrage.com/2025/05/…

This adds another dimension to why Meta has not repurchased a single share so far this year.
$META has shifted from buying back $22.9B of stock in H1 2025 to zero repurchases in H1 2026 as AI capex surges.
Now it is creating a non-voting Class C share class that could give it another source of capital for AI investment without diluting Zuckerberg’s voting control.
Interesting capital-allocation pivot: from aggressively shrinking the share count to potentially using equity itself as a funding source

Semafor: Meta is creating non-voting Class C shares so it can raise AI money without diluting Mark Zuckerberg’s control.
Holders will get 1 Class C share for each Class A or Class B share once the charter changes on January 19, 2027.
That dividend should move Class A’s price as a 2-for-1 split would, yet it leaves every holder’s voting power unchanged.
The shares will also pay employees, and Zuckerberg’s lawyers told the special committee that voting stock would exclude sovereign financial institutions as buyers.
Alphabet’s similar structure let it sell $85B of stock this year, giving Meta a template for funding $135B to $145B of capital spending without costing Zuckerberg votes.

🫁 United Therapeutics authorized another $2 billion share repurchase program through October 21, 2027. That’s roughly 8% of $UTHR’s current market cap
What makes this more interesting is the execution history.
Earlier this year, United Therapeutics authorized $2 billion and moved quickly to use it:
$1.5 billion went into ASRs in March, another $22.4 million was bought in the open market during Q3, and the remaining ~$477.6 million was committed to another ASR in September.
CEO Martine Rothblatt said at the time that the market was not reflecting the scale of what the company is positioned to achieve and that its growth opportunities were more powerful than the stock valuation implied.
Upon completion of that prior program, United Therapeutics said it would have returned roughly $4 billion to shareholders in about 2.5 years
Now it has immediately reloaded with another $2 billion authorization
insidearbitrage.com/symbol-m…
$UTHR

ALT $UTHR - Buyback execution in 2026
EQT Private Equity to Acquire QIAGEN $QGEN for $12.10 Billion -
🔹Qiagen shareholders will receive €46.50 ($52.29) in cash for each Qiagen share, representing a 4.58% premium over the stock’s last close.
🔹The closure of this merger is currently expected in mid-2027.
🔹If the transaction does not close within 10 months (by August 21, 2027) due to pending regulatory approvals, Qiagen may elect to pay shareholders an interim dividend of up to $0.47 per share. Any such dividend will be paid in addition to the offer price and will not be deducted from it.
In January, Bloomberg reported that Qiagen was weighing strategic options including a potential sale amid fresh takeover interest. The stock was trading at $47.57 when Qiagen held talks with several possible buyers, including some US strategics.
In 2020, Qiagen had tried to merge with Thermo Fisher Scientific $TMO, but that offer lapsed. Other companies like Bio-Rad Laboratories $BIO, BioMerieux, Quidel Corp., have also made attempts at acquiring the company through the years.
For those interested in a more in-depth analysis of this merger, click on the link below:
insidearbitrage.com/2026/10/…

ALT EQT Private Equity to Acquire QIAGEN for $12.10 Billion

ALT InsideArbitrage Potential Deal Alert: Qiagen (QGEN) Is Said to Consider Strategic Options Amid Fresh Interest
$ABT Abbott to Spin Off $8.5B Nutrition Business by End of 2027
🔄Abbott plans to separate its Nutrition business into an independent, publicly traded company through a tax-free distribution to shareholders, with completion targeted by the end of 2027.
🥛SpinCo: The new Nutrition company will have about $8.5B in annual sales, 16,000 employees and 14 manufacturing sites, with brands including Similac, PediaSure, Pedialyte, Glucerna and Ensure. Daniel Salvadori will become CEO of the Nutrition company.
🏥Parent: Post-separation, Abbott will retain its medical devices, biowearables, diagnostics and established pharmaceuticals businesses, representing about $42B in annual sales, with management expecting faster growth and an improved margin profile.
⚠️Why Now: Nutrition has faced pressure from the loss of a major U.S. government supply contract, higher manufacturing costs and weaker demand following price increases, while the Similac business is still carrying baggage from the 2022 Sturgis plant shutdown, recall and related litigation.
📉The spin comes as Abbott cut its 2026 sales-growth outlook to about 6% from 6.5%-7.5%, while Q3 Medical Devices sales increased 6.9% to $5.83B but missed estimates on weaker heart-device sales; shares fell about 4% premarket.

ALT Abbott Spinoff
InsideArbitrage retweeted

Akzo Nobel in Talks to Shed European Refinishing Unit for Axalta Merger Nod on.wsj.com/47sq8vI

SpaceX $SPCX and Tesla $TSLA Boards Explore Potential Merger -
✴️SpaceX and Tesla are exploring a deal to combine Elon Musk’s two companies in a multitrillion-dollar deal that could become the largest merger in history.
✴️Musk said that both companies had formed special committees to study a tie-up.
✴️“Do I think it would be a good idea? Yes. But at the end of the day, the shareholders have to be supportive of this,” Musk said, adding that as chief executive of both companies, he cannot participate in the discussions.
✴️“The special committees have not reached agreement on the terms of any transaction, and obviously there is no guarantee that they will,” he added.

ALT SpaceX and Tesla Boards Explore Potential Merger

Q3 2026 Financial and Operational Results xitter.cf/i/broadcasts/1PKqrNbLZ…
InsideArbitrage retweeted
An activist is paying ex-Disney CEO Bob Chapek $100,000 a month as one of its nominees to the board of struggling ski company on.wsj.com/4z1zqej

Salesforce $CRM to Acquire Braze $BRZE in a $5.66 Billion Cash Deal -
✴️Holders of Braze Class A common stock will receive $47.50 in cash per share, representing a premium of 58.12% over the stock’s last close.
✴️The deal is expected to close in Salesforce’s fiscal year 2028, ending in January 2028.
For a more in-depth analysis and specifics of this merger, click on the link below:
insidearbitrage.com/2026/10/…

ALT Salesforce to Acquire Braze in a $5.66 Billion Cash Deal
🚗 General Motors reports strong Q3 results (double beat) and updates full-year 2026 guidance; it authorized a massive $20 billion multi-year share repurchase program, equal to roughly 27% of its current market cap!
🟢 $GM has already been an aggressive buyer of its own stock
🔁 Since 2023, the company has repurchased about $29.5 billion of shares, helping drive a significant reduction in the share count
And the new authorization comes alongside another solid quarter:
🟢 Q3 adjusted EBIT rose 22% to $4.1 billion, while North America margins improved to 8.7% from 6.2%. GM also narrowed its 2026 adjusted EBIT guidance to $14.5-$15.5 billion.
🗨️ CEO Mary Barra said GM’s earnings and cash-generation outlook gives the company confidence in its ability to keep returning capital to shareholders, calling the new $20 billion authorization an extension of a “proven strategy.”
insidearbitrage.com/symbol-m…
$GM

ALT $GM - Change in shares outstanding
InsideArbitrage retweeted
FTC order preserves competition in digital advertising ecosystem as part of Publicis’s acquisition of LiveRamp: bit.ly/4zKO89u /1

InsideArbitrage retweeted

NEW: Activist hedge fund Starboard Value has built a stake in Honeywell spin-off Solstice Advanced Materials, as the US speciality chemicals group fights to rebuild credibility with shareholders after an aborted megadeal.
With @ameliajpollard
