

Delta Hunter | Catalysts & Smart Money (US + India) | Price × Fundamentals | Volume Reveals | IT in Manufacturing |Tweets for learning
Germany
Joined October 2021
- Tweets2.1K
- Following366
- Followers6.8K
- Likes2.8K





The data below indicates that DIIs are selling my portfolio stocks, while FIIs are buying stocks from my watchlist stocks

💹 FII/DII Flows — 20 Nov
🟢 FII net bought ₹10,308 Cr
🔴 DII net sold ₹4,860 Cr
📅 FII: 15 consecutive days of FII buying · DII: 3 consecutive days of DII selling
#FII #DII #StockMarket #Nifty

2
8
1,497
Gaining "Market Share"
Historically, gaining market share has been one of the most powerful catalysts for wealth creation.
Identifying such businesses early can create exceptional investment opportunities.
From the Q2 FY27 concalls, which companies do you think are gaining market share?
Share your picks in the comments! 👇
My observation #GREAVESCOT
Reached 5th position in India's electric 2W market with 5.7% market share in Nov 2026
P/E = Price / Earnings or Perception / Expectations? Why Momentum Stocks Rise Faster Than Earnings and Fall Faster than Fundamentals.
The ongoing correction in the global AI Data Centre (AIDC) theme is a classic example of how stock markets work.
A few months ago, the market was asking, “How big can the AI opportunity become?” Today, it is increasingly asking, “Will these massive investments generate adequate returns?”
The opportunity hasn't disappeared. Demand is still growing, investments are continuing, and many companies are reporting strong numbers, with reasonable earnings visibility for the next 2–3 years.
So, what has changed? Not necessarily the earnings outlook, but the market's perception of how sustainable those earnings will be in the long run.
Earlier, investors were willing to pay 50x earnings for a business expected to grow at 30%, assuming that growth could sustain for many years. Today, even if the business continues growing at 30%, the market might value it at just 30x because of changing sentiment, uncertainty around future capex, and concerns over long-term growth sustainability.
That is a 40% valuation derating without any deterioration in current earnings or near-term growth expectations.
This is where terminal value comes into play. A significant portion of a company's valuation depends not just on what it earns over the next 2–3 years, but on how long those earnings can continue growing beyond that period.
This is why understanding a business is only half the job. Understanding what expectations are already priced into its valuation is equally important when you chasing " Momentum stocks"
The biggest risk in investing isn't always that the business will disappoint. Sometimes, the business delivers exactly as expected, but the market is no longer willing to pay the same premium for those earnings.
That is the difference between an earnings correction and a perception correction.
4
12
2,083
Another hit for AIDC
teapawt.net/wallstengine/status/21…

Semiconductor research firm SemiAnalysis has sharply LOWERED its global AI accelerator capital expenditure forecasts, with cuts of up to 41%:
2027: $770B → $627B (-19%)
2028: $1.054T → $758B (-28%)
2029: $1.352T → $796B (-41%)
2030: $1.531T → $923B (-40%)
That's a $608 billion reduction in its 2030 forecast alone.
SemiAnalysis also cut its cumulative 2026-2030 accelerator silicon shipment area forecast by 17%, with Nvidia accounting for 66% of that reduction.
Its 2028 HBM shipment forecast was lowered from 9.0 to 6.4 exabytes, a 30% reduction, while projected 2030 AI accelerator power demand fell from 122.8 GW to 80.7 GW, down 34%.
The firm cited slowing revenue growth at frontier AI labs, tighter capital markets, and lower assumptions for future chip and memory pricing.
Importantly, even after these cuts, SemiAnalysis still expects annual AI accelerator spending to more than double from $392 billion in 2026 to $923 billion by 2030.


2
448
The Catalyst Decoder retweeted
#QPOWER competitive advantage
Hitachi + Siemens , these two control 70–75% of global HVAC/HVDC business and together with GE, the three own ~90%.
Hitachi and Siemens will not want to buy from a GE Vernova owned competitor, so they’ll shift sourcing to QPOWER right. So positive 😃

Trench is Qpower's largest competitor overlapping in coils/reactors and instrument transformers
Hitachi + Siemens control ~70-75% of HVDC/FACTS and GE acquiring Trench can be a tailwind for companies like Qpower where thy are expecting the volumes with these 2 customers to go up significantly as GE uses Trench for its in house consumption.
This can be a key factor to track for other power equipment suppliers supplying to the likes of Hitachi and Siemens.
Disclaimer - Not a recommendation to buy/sell

Happy Forgings Ltd
As per SEBI norms, companies with a post-IPO market capitalization of less than 50,000 Cr must reduce the promoter's shareholding to 75% within a period of 36 months from listing.
Today, in the 35th month post-IPO of #HAPPYFORGE the promoter has reduced the stake to 75%, complying with the regulatory requirement.

Bharat bhai has been sharing some very insightful views on the pharma CDMO space. Around 4–5 quarters ago, he repeatedly and confidently said that FY27 would be the year of CDMO. Now, everyone is running behind the same theme.
@Quest_for_value 🙏


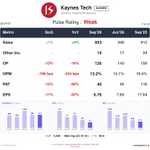
Kaynes Technology – Q2 FY27
The numbers are disappointing, but largely in line with what management had indicated in the Q1 FY27 concall.
Margins have deteriorated, as expected.
The real question now is whether OSAT and PCB operations will commence and ramp up in Q3 FY27 as planned, or face further delays.
Looking forward to management's commentary. Execution and timelines will be the key things to watch.

The Catalyst Decoder retweeted

Six of Nvidia’s seven biggest customers are building their own chips.
“NVIDIA’s seven biggest customers account for the vast majority of GPUs being deployed: Google, Microsoft, Meta, Amazon, SpaceX, Anthropic and OpenAI. All of them, except SpaceX, are making their own chips.”
“If NVIDIA didn’t prop up CoreWeave and the other neoclouds, those industries just would not exist, and the hyperscalers would have full control.”
“Jensen’s the only executive in the semiconductor industry convincing supply chain companies to invest like they’ve never done before. From our benchmarking, the TPU is just as good as NVIDIA. But Google doesn’t have that DNA of wheeling and dealing.”

#INDSWFTLAB
In this Q2FY27 concall. Overall view?, growth is fully funded, capacity is in place, and several catalysts line up over the next few quarters.
Two CDMO customer agreements expected in Q4 FY27, supporting 200–220 Cr additional annual revenue potential over the next two years.
The 7.8% Synthimed stake, worth about 550–620 cr at management’s 7000–8000 cr valuation, offers a potential cash unlock through tag-along rights alongside the majority holder.

Ind-Swift Laboratories Ltd
#INDSWFTLAB
The company has upgraded its FY27 revenue growth guidance from the earlier 900 Cr revenue target to 50% revenue growth, with EBITDA margins expected to reach 20%.
The long-term revenue target stands at 1500 Cr. Management also indicated that there are no major working capital constraints. The company may monetise its remaining stake in the previously divested API business when a suitable opportunity arises to support future working capital requirements.
H1 exports 190cr among that 65cr CDMO and H2 above 80cr CDMO possible.
540 approved dossiers.
A very bullish concall. Given the strong business momentum and upgraded guidance, I wouldn't be surprised if the company achieves 1000 Cr in revenue in FY27.
Disc: No buy/sell.


Kwality Pharmaceuticals Ltd
The bull-case scenario is playing out, and the stock is not expensive at all, considering the growth potential. The growth acceleration is expected to continue. If you listen to the concall, it is clear that bioequivalence and expansion into new countries are making good progress.
If the company delivers on what management has outlined, the growth story becomes quite straightforward. The company has set a long-term revenue target of 1000Cr by FY29, and it could potentially achieve this target even earlier.
#KPL

Kwality Pharma – Investment Thesis View
Kwality Pharma is gradually evolving into a niche, export-led specialty pharma player with a diversified presence across oncology, hormones, biosimilars, and complex injectables. The business operates through two distinct models—out-licensing in Rest of World markets and CDMO in regulated geographies like Europe.
In the out-licensing model, the company owns product registrations and brands across 30–40 countries with a portfolio of 400–500 molecules, giving it strong control over distribution and pricing flexibility. In contrast, the CDMO model enables faster market entry in regulated markets through site variation approvals, typically within 6–8 months, with pricing advantages ensuring stable partnerships.
The R&D model is structured and scalable, with an in-house team of ~80 specialists supporting out-licensing. Biosimilar development is partially outsourced across the US and India, while CDMO operations remain replication-driven with no major R&D requirement. R&D intensity is expected to rise from ~2% earlier to 5–6% in FY27, driven by ~40 bioequivalence studies, with a target of 60–70 studies by FY28.
Manufacturing remains the core execution engine, with overall utilisation at 65–70% in general lines. Key expansion drivers include oncology (Unit 3), targeting ~₹500 Cr revenue by FY29, hormones (Units 5 & 6) expected to contribute ~₹200 Cr each over FY28–29, and syphilosporin/cephalosporin lines targeting ~₹200 Cr by FY28. Biologicals remain a long-term optionality not yet fully factored into near-term guidance.
The company has planned capex of ~₹160–170 Cr over FY27–FY28, largely funded through internal accruals, indicating relatively controlled leverage. Revenue guidance stands at ~₹650 Cr with an upside aspiration of ~₹700 Cr, driven by export markets such as Mexico, Colombia, and Algeria.
Margins are expected to improve structurally, with EBITDA projected at 25–26% in FY27 and potential expansion to 29–30% at a ₹1,000 Cr revenue scale, supported by product mix improvement and operating leverage.
Working capital remains a key constraint, with receivable cycles around 150 days due to export-led operations. However, gradual improvement is expected as faster cash-cycle markets scale up.
From a strategic standpoint, the company operates in a high entry-barrier space combining multiple complex therapeutic areas. Execution on regulatory approvals, BE studies, and capacity ramp-up will be critical in translating the pipeline into sustained earnings growth.
Overall, Kwality Pharma represents a structured growth story with improving scale, expanding margins, and strong long-term optionality, but execution risk and working capital intensity remain key monitorables.
Management guidance, on a conservative basis, implies FY29 is valued at around 9x forward PE, showing strong upside if execution plays out as discussed in the first con-call. Even FY27 valuation at around 16x forward PE looks cheap.
Disc: No buy and sell.

Apollo Micro Systems Ltd
It’s been a while since I revisited #Apollo, and now it seems like the right time to take another look ?
The near-term triggers look very strong, with defence budget announcements and cabinet approvals in focus these days.
MIGM: RFQ expected in November 2026, with PO by Jan-Feb 2027. Apollo is the sole electronics and sensor supplier. Management targets an order book of 4500–5000 Cr by FY27-end, up from 1765 Cr.
Pinaka: Around 4,000 rockets of potential demand, including exports to Armenia. Orders for 300 units are expected before December.
Torpedoes: Expected 100 Cr+ opportunity from Varunastra. An emergency order for 30 heavyweight torpedoes is expected in November, followed by a potential requirement for another 125 units.
MIGM (Multi-Influence Ground Mine): An advanced underwater naval mine developed by DRDO's Naval Science & Technological Laboratory (NSTL), Visakhapatnam, for the Indian Navy.

𝐀𝐩𝐨𝐥𝐥𝐨 𝐌𝐢𝐜𝐫𝐨 𝐒𝐲𝐬𝐭𝐞𝐦𝐬 𝐋𝐭𝐝
#APOLLO
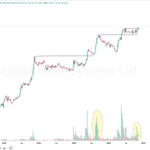
Some charts tell you the story… but sometimes, they remind you to listen to what management says in earnings calls. This is one such case. I’ll share a few interesting snippets from the transcript in this thread. DYOR before making any investing decision.

Action Construction Equipment Ltd
#ACE – Q2 FY27 Concall Key Takeaways
FY27 Guidance: Revenue growth of 18–20%, with EBITDA margins expected to sustain through better product mix and operating leverage ( No guidance in last quarter)
Strong H2 Expected: Historically contributes 55–60% of annual revenue. Strong demand since September and healthy order bookings.
KATO JV: JV with Japan's KATO Works operational, targeting high-value cranes. FY28 revenue potential 100–150 Cr, scaling to 300–400 Cr medium term.
KATO Exports: Export models expected by FY29–30. Domestic EBITDA margin target 15%, potentially higher for exports.
Capacity Headroom: crane and construction equipment utilisation was approximately 55% at Q2-end, but management indicated it had subsequently reached 70–75%. Existing infrastructure can support 5500–6000 Cr overall revenue. (vs FY 26 , 3300cr revenue)
CapEx: New 40–50 Cr defence/products plant by Jan–Feb 2027. Additional 400 Cr tower crane expansion under consideration for Q4 FY27/Q1 FY28.
New Products: Container reach stackers and piling rigs planned in 1–2 years. Each could generate 150–200 Cr annually within 2–3 years of launch.
Defence: Order book above 500 Cr, executable over 18–24 months. Includes 74 backhoe loaders for BRO (20–25 Cr).
Exports & Defence: Combined contribution expected at 11–12% of FY27 revenue, reducing domestic crane dependence.
Steel Inflation: Price hikes of 7–8% implemented by September. Further increases possible in January to protect margins.
Anti-Dumping Duty – Potential Trigger: Management expects greater clarity within 1–2 months. Any favourable decision could strengthen ACE's competitive positioning against Chinese imports, but this remains uncertain.
Overall my view: Back to track and good visibility from now.

#MANINDS
Q2 FY27 Concall | Key Takeaways - NPC
Q2 Performance: Revenue ₹486 Cr, EBITDA ₹88 Cr (18% margin), PAT 77 Cr (15.8% margin). Ahead of expectations.
Revenue Guidance: FY27 1500 Cr; FY28 2500 Cr. Next 2 quarters expected at 500 Cr each.
Utilisation: Currently 40–45%, with significant headroom. Expected to remain similar for the next 2 quarters.
Coating Plant: Commissioning by April 2027, with margins expected above 15%.
Peak Potential: Earlier guidance of 3500–4000 Cr revenue at 80–85% utilisation, suggesting further growth potential beyond FY28.
Balance Sheet: Debt-free with 1576 Cr net worth. Integration completed successfully.
-------#####-----------
Other Income 24cr ? special attention.
Record EBITDA: 190 crore. The CFO said it would be 215 crore if a forfeited customer advance of about 25 crore, shown as an exceptional item, were counted.
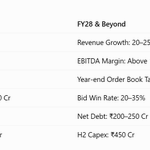
Overall guidance in table format👇

#MANINDS
Man Industries has entered a high-demand segment in Saudi Arabia through the acquisition of NPC. The Saudi Arabia-based company has a strong client base, along with the necessary certifications and approvals. It is now part of Man Industries. This could be one of the most significant acquisitions for the company and potentially transform its future growth prospects.
Man Industries paid USD 102 million (about 1000 crore) for NPC, and management puts the Saudi business’s peak revenue at 3500–4000 crore upper end by FY28-FY29.
Just look at NPC key clients👇
MANINDS P/B = 2.4x
WELCORP P/B = 5.3x ( peer and Industry leader)

#TDPOWERSYS
TD Power Systems – Is Sentiment Changing?
As expected, the concall delivered a guidance upgrade and management reiterated that there is no change in the demand outlook and coming to me nothing surprising here and same was heired from other AIDC players
However, despite the positive commentary, the price action wasn't particularly encouraging today, although the stock eventually closed in the green.
So, what has changed? Perhaps only sentiment.
In Markets.... Narrative creates belief, sentiment creates momentum, and price creates conviction.
I remain a TD Power bull, but I also believe in being a flexible observer of reality rather than being rigid about my thesis.
I wouldn't be surprised if the stock goes through some time correction from here, and I'm not against it. In fact, a period of consolidation could be healthy.
Bullish on the business, but open-minded about the price action and views are personal and no buy/sell recommandations.
----------------------------------------------------
TD Power Systems – Q2 FY27 Concall Key Takeaways
1. Guidance Upgraded: FY27 revenue guidance revised upward to 2900–3000 crore. Initial FY28 guidance stands at 3400–3500 crore, which management considers conservative.
2. Long-Term Ambition: Management reiterated its $1 billion revenue aspiration, with a conservative 20–25% growth trajectory.
3. 2-Pole Generators: Development progressing as planned, providing another potential growth avenue.
4. Siemens Opportunity (FY29–30): The Siemens plant-related opportunity is expected to materialise around FY29–30. OEMs typically release orders closer to execution, based on detailed production forecasts.
5. US Data Centre Regulations: Management is not particularly concerned about political opposition to data centres. Investments could shift between locations rather than disappear. Tighter regulations could even accelerate captive power demand.
6. SoftBank Gas Turbine Cancellation: Management views SoftBank's cancellation of turbine reservations as an isolated event, not indicative of weakening industry demand.
7. Siemens Partnership: The Siemens partnership potentially limits collaboration opportunities with other major turbine OEMs, creating a strategic trade-off. ( Only 3 major OEM's in world)
#TDPOWERSYS
Great set of numbers, as usual. This time, sentiment is slightly unfavourable, and many might argue that the stock is expensive. Some may have a different opinion, but the real judgment will come tomorrow. Price action will deliver the verdict.
#Intellect Usually, management talks about revenue and margin guidance. But this management is talking about doubling EPS over the next two years.
They plan to achieve this through employee cost reductions and operating leverage. They are targeting decent year-on-year revenue growth of 15%, with margins expected to reach 20–25%.
An interesting interview. Worth watching in your spare time!

Intellect Design Arena's Arun Jain discusses company's FY28 revenue and margin guidance.
In conversation with @sharad9dubey