

Delta Hunter | Catalysts & Smart Money (US + India) | Price × Fundamentals | Volume Reveals | IT in Manufacturing |Tweets for learning
Germany
Joined October 2021
- Tweets2.1K
- Following366
- Followers6.8K
- Likes2.8K





The Catalyst Decoder retweeted
#QPOWER competitive advantage
Hitachi + Siemens , these two control 70–75% of global HVAC/HVDC business and together with GE, the three own ~90%.
Hitachi and Siemens will not want to buy from a GE Vernova owned competitor, so they’ll shift sourcing to QPOWER right. So positive 😃

Trench is Qpower's largest competitor overlapping in coils/reactors and instrument transformers
Hitachi + Siemens control ~70-75% of HVDC/FACTS and GE acquiring Trench can be a tailwind for companies like Qpower where thy are expecting the volumes with these 2 customers to go up significantly as GE uses Trench for its in house consumption.
This can be a key factor to track for other power equipment suppliers supplying to the likes of Hitachi and Siemens.
Disclaimer - Not a recommendation to buy/sell

The Catalyst Decoder retweeted

Six of Nvidia’s seven biggest customers are building their own chips.
“NVIDIA’s seven biggest customers account for the vast majority of GPUs being deployed: Google, Microsoft, Meta, Amazon, SpaceX, Anthropic and OpenAI. All of them, except SpaceX, are making their own chips.”
“If NVIDIA didn’t prop up CoreWeave and the other neoclouds, those industries just would not exist, and the hyperscalers would have full control.”
“Jensen’s the only executive in the semiconductor industry convincing supply chain companies to invest like they’ve never done before. From our benchmarking, the TPU is just as good as NVIDIA. But Google doesn’t have that DNA of wheeling and dealing.”
The Catalyst Decoder retweeted

Man Industries (India) Ltd
#MANINDS
Man Industries – Saudi Acquisition Driving a Major Growth Opportunity
One of the interesting stories we have been tracking is Man Industries, where the acquisition of Saudi Arabia's National Pipe Company (NPC) could materially transform the company's growth and margin profile.
Why is this acquisition interesting?
In May 2026, Man Industries acquired 100% of NPC for approximately ₹1,000 Cr at an attractive 1.5x EV/EBITDA valuation, significantly below Saudi listed-peer multiples of 7–9x.
NPC brings several advantages:
430,000 MTPA manufacturing capacity for large-diameter steel pipes used in oil & gas and water infrastructure.
Saudi Aramco-approved supplier, with an established relationship spanning over two decades.
An operational, profitable manufacturing facility with an existing customer base and order book.
Exposure to Saudi Arabia's massive energy and water infrastructure investments under Vision 2030.
What makes the opportunity exciting?
The Saudi business has the potential to contribute substantial incremental revenue at 15–18% EBITDA margins, compared with the company's historically lower consolidated margins.
Management has indicated that Saudi operations could eventually generate 3500–4000 Cr annual revenue at 80–85% utilisation.
Additionally, a new pipe-coating facility in Dammam, targeted for March 2027, could further improve the product mix and profitability.
Today's numbers provide encouraging evidence that the acquisition-led growth thesis is playing out.
Disc: Info for edu only.


The Catalyst Decoder retweeted
Another interesting beneficiary of the Caterpillar engine supply crunch is Happy Forgings Ltd
#HAPPYFORGE is moving into ultra-heavy crankshafts/components valued at ₹25–40 lakh each, used in large engines powering data centres.
Caterpillar has been cited as a customer in external reports, although management hasn't explicitly confirmed the name.
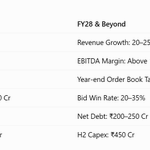
With ₹300 Cr in secured data-centre-linked annual revenue potential and major capacity expansion underway, this could be a significant growth trigger from FY28 onwards.

The Catalyst Decoder retweeted

Happy Forgings
#HappyForgings
Probably one of the brutal reaction for consistent 32%++ growth that the company is giving every quarter
Solid #Q2FY27 with very very consistent performance across all parameters
Highest ever revenue, EBITDA, PBT and PAT in comps history
Volumes at 18754 MT⏫25%
Realizations at 267⏫6.3%
Rev at 501cr⏫33%
Gross profit at 305cr⏫34%
EBITDA at 153cr⏫32%
PAT at 98cr⏫33%
H1FY27:
Rev at 950cr⏫30%
Gross profit at 577cr⏫34%
EBITDA at 296cr⏫36%
PAT at 189cr⏫36%
RoE 17%
RoCE 20%
Additional capex of 500cr
Scaling volumes while enhancing value addition and improved realizations
Margin expansion driven by value addition and efficiency
Strong cash flow generation
350cr liquidity surplus
Funding capex through internal accruals


The Catalyst Decoder retweeted
Marine Electricals (India) Ltd
#MARINE has not conducted a concall yet. It has a substantial order book, entirely from the domestic market. Also, its data center orders are not directly linked to the AI/DC theme.


The Catalyst Decoder retweeted

Shadowfax’s concall - very interesting insights on QC, Express delivery, Amazon, etc.
Management guided for 27–30% revenue growth. Here’s how it sees the key drivers:
1. Express Parcel: market-share gains
Shadowfax is targeting 27–28% CAGR despite slower underlying e-commerce growth, driven by deeper penetration among large sellers, D2C brands and smaller sellers through Shadowfax 360.
2. Quick commerce: 30%+ industry growth, with upside
Management expects the industry to compound at 30%+ and aims to maintain its leading share in third-party logistics (3PL).
“Every year quick commerce continues to surprise us and amaze us.”
Faster industry growth could provide upside to its assumptions.
3. Value-added services: 35–40% of revenue - Same day delivery, Prime, reverse logistics and exchange services remain key offerings. Small sellers can now access same-day and next-day delivery, while the acquired critical logistics capability is fully integrated.
“Value-added services continue to remain about 35% to 40% of our revenues.” Management expects a similar mix over the next 3–5 years.
4. Amazon: already a top-five customer - “Within a year of launch… Amazon has become one of the top-five customers for us.”
The partnership spans Express Parcel and quick commerce, with quick commerce growing significantly faster. Most Express Parcel integrations are complete; the rest are expected over the next couple of quarters.
“One should expect a meaningful jump only to come in the next financial year.”
My takeaway: Express Parcel growth relies partly on market-share gains, while the fast growing quick commerce benefits more from industry expansion. Amazon is already sizeable, with the larger e-commerce contribution still ahead. Very solid concall overall with detailed insights on the ecom, qcom & logistics sector.
Disc: Not a recommendation


Shadowfax: the next margin gains will be harder won
Shadowfax crossed ₹1,500 crore of quarterly revenue and a 5% adjusted EBITDA margin in Q2 FY27. Consolidated revenue grew 57% year on year to ₹1,538 crore, while adjusted EBITDA, including full rent and excluding ESOP expense, reached ₹77 crore. The margin improved only seven basis points from Q1, however, and the call explains why the next phase of profit growth will look different.
1) Speed is changing who buys the service
CEO Abhishek Bansal said, “Price can be matched within a quarter”. His argument is that reliable same-day delivery needs a network built before the orders arrive.
Shadowfax is now offering small marketplace sellers fast delivery directly from their own locations, without requiring them to place inventory in marketplace warehouses. Shadowfax 360 reached 6,700 transacting sellers, versus 1,200 in Q1. D2C revenue was 2.1 times the year-earlier level, and management says customers outside the top ten were its fastest-growing group.
This offers a route beyond dependence on a handful of large platforms. Management reported its largest customer’s revenue share was three to four percentage points below its long-term average, although it did not disclose the current percentage. The commercial opportunity is to sell delivery speed to sellers whose sales depend on it, rather than compete only for large marketplaces’ lowest-cost parcels.
2) The cost mix can mislead
Delivery-partner expenses rose from 52.4% to 53.4% of revenue, while transport costs fell from 18.8% to 18.3%. Management attributed both largely to hyperlocal’s revenue share rising from 20% to 22%. Hyperlocal uses more delivery partners; express parcels use more middle-mile transport. These movements should not be read as equivalent wage inflation and transport productivity gains.
Likewise, hyperlocal revenue per order rose 13% sequentially because of longer-distance deliveries and a greater food-delivery mix. A larger delivery bill does not by itself establish greater pricing power.
3) Easy loss reductions are running out
Lost-shipment and quality-check costs fell from 5.5% to 5.0% of revenue. Management now expects the next milestone, 4%, over a few quarters, and explicitly warned that the recent rapid improvement will not repeat. July’s longer-term ambition was 3.5–4%.
That puts more weight on customer mix and network utilisation. Mid-mile space increased 40% sequentially, against roughly 10% order growth. Rent rose from 3.2% to 3.5% of revenue ahead of the October festive peak. Only around 5% of the overall operating footprint is temporary; most of the new capacity needs continuing throughput after the peak.
4) Expansion remains inside the existing commitments
Managed dark stores reached 70, against July’s 47 and the 100-store FY27 target. New micro-fulfilment centres will hold several brands’ inventory near existing sort centres for eight-to-twelve-hour delivery. Their investment is included in the 3.8–4.0%-of-revenue capex envelope, with little FY27 revenue expected.
Despite 60% first-half revenue growth, management retained its 38–40% FY27 growth guidance, preferring to reassess after Q3.
Kyro Read: Shadowfax has a credible mechanism for winning higher-value customers on a shared network. With easy shipment-loss savings fading, the next margin improvement depends more on filling permanent capacity and growing those customer relationships. The festive peak will test how well the larger network earns its keep.
Disc: Not a recommendation
Explore more about us at kyroventures.com


The Catalyst Decoder retweeted
#STLTECH Q2FY27 concall Key notes
FY29 Targets: The company has maintained its revenue target of 20,000 Cr and increased its EBITDA margin target to around 30% and current orderbook 32000cr.
Improving Margins: Management expects profit margins to remain at 27.1% or higher from Q3 onwards, compared with its earlier FY27 guidance of 23%.
Extra Costs/One Off : ₹39 Cr impairment, ₹22 Cr additional depreciation from writing off subsidiary and High Interest cost are recorded in Q2 and received Tax refund 160cr
Actual Profit Picture: After adjusting for these extra costs, estimated profit 420-450cr
Data Center Growth: Contributed 33% of H1 revenue, with a target of 50% in FY27, supported by two hyperscaler contracts worth over $2.3 billion. Management aims for a 50-60% revenue share from data centers to maintain a balanced customer and geographic mix.
Disc: No buy/sell.
Sterlite Technologies Ltd
#STLTECH
Q2 FY27 blockbuster numbers and Order book reached 32000cr.
The screenshot below speaks a thousand words.
Disc: No buy/sel

The Catalyst Decoder retweeted

QPower (QPOWER): A key manufacturing milestone in the BESS opportunity.
Quality Power Electrical Equipments has commenced operations at its new Power Conversion Systems (PCS) facility in Nigde, Türkiye, through subsidiary Endoks Energy Systems.
Why this matters:
• Operations started: 16 October 2026.
• What it manufactures: Power electronic converters and inverters for utility-scale Battery Energy Storage Systems (BESS) and grid-connected applications.
• Expands QPower into power electronics and energy storage, complementing its existing high-voltage equipment and power quality business.
• Order-book execution: The facility is intended to support execution of the Group’s international BESS order book.
• Production ramp-up: Will be gradual, aligned with operational plans and customer delivery schedules.
This is more than a new-facility announcement. QPower is strengthening its manufacturing and system-integration capabilities in the energy-storage value chain.
What to track next: 👉Production ramp-up, execution of international BESS orders and the eventual contribution to revenue and profitability.
Important:
No Recommendations.
#QPOWER

The Catalyst Decoder retweeted

It is a great story. I was visiting their facility recently and impressed. Q2 FY27 will be even better as CDMO and Branded Product export mix with higher margin will start contributing
The Catalyst Decoder retweeted
Jash Engineering Ltd
#JASH seeing the Data Center opportunity ?
The Answer is "Yes". However, they are not directly supplying to hyperscalers, but to their vendors.
What the product actually is????
This is not a brand-new product but a modification of something Jash already makes. Their existing pressure vessels are used on transmission lines for water hammer control (surge protection), not cooling. For data centers, the same vessel has been adapted with internal design changes to suit the cooling application.
Current order traction:
- First order already won: 4 vessels
- Under negotiation: another order for 32 vessels
- Quoted (pipeline): more than 600 pressure vessels, which he noted is "enough to make a new plant"
Product cost / economics
Per vessel: roughly Rs.30–50 lakh depending on size, up to about Rs.60 lakh for larger ones
The 32-vessel order being negotiated: Rs.35–40–50 lakh × 32 (so broadly Rs.11–16 crore)
Full-scale annual opportunity: an investor (Yogansh) framed it as a Rs.25–30 crore/year business, which Patel did not dispute
The Revenue guidance:
FY27: Rs.875 Cr revenue, including Rs.320 Cr from India and Rs.555 Cr from international markets, with Rs.100–105 Cr PAT. Management reiterated that this is easily achievable and remains bullish.
FY28: Rs.1025 Cr revenue.
Long term: Rs.1500 Cr revenue target by 2031.
Disc: No buy/Sell.

The Catalyst Decoder retweeted
Power & Transformer Proxies: Winding Wire Capacity Tracker
Who controls Indian enamelled copper winding wire volumes? Here is the capacity trajectory across top organized players

The Catalyst Decoder retweeted
Carborundum Universal Ltd
CUMI’s decision to close its loss-making German subsidiary (Awuko) and the growth in its Ceramics business could play out the operating leverage story.
#CARBORUNIV

The Catalyst Decoder retweeted
Manorama Industries Ltd
#MANORAMA growth trigger simply for you
Disc: Info for just edu. No Buy/sell


The Catalyst Decoder retweeted
#RKFORGE
Ramkrishna Forgings promoters are again putting INR 150 Cr into the company through the conversion of 34 lakh warrants at INR 588 per share. The company has received INR 149.94 Cr from promoter Chaitanya Jalan. This is another meaningful promoter capital commitment and worth tracking for how the company deploys the funds toward its next phase of growth.

Ramkrishna Forgings Ltd
#RKFORGE management latest TV interview.
Growth outlook:
Management expects revenue to compound at roughly 20–25% annually, supported by improving commercial-vehicle demand, domestic growth, Europe, and North America.
The North American Class 8 truck market is a major near-term driver: first-seven-month order bookings were cited at 223,000 trucks, versus 218,000 for all of the prior year.
The company believes capacity utilisation will rise from the current 68%, creating operating leverage and supporting margin improvement
youtube.com/watch?v=C3L_OAQ0…

The Catalyst Decoder retweeted

Interesting development #morepen labs - senior resource hired for oncology tech transfer - currently morepen has no oncology API
