

I work with families/biz owners wanting to lower their taxes with charitable trusts.
🌟 Not Financial Advice 🌟
Joined June 2011
- Tweets4.9K
- Following1.2K
- Followers954
- Likes17.8K




Pinned Tweet
Ran the numbers on a $500K house at 6.75%.
Live there 7 years, then sell.
-Monthly payment: $2,594
-Total payments: $217,929
-Interest paid: $181,079
-Principal paid down: $36,850
Seven years of payments and you own $36,850 more of the house than you did on day one.
Add property taxes, insurance, maintenance, closing costs and the 6% to sell it, and roughly $355K is gone for good.
You walk away with about $215K of equity, most of it your own down payment plus appreciation.
Now the other path.
Rent at $2,900/mo (rising 3%/yr) for the same 7 years: about $268K gone.
Take the $100K down payment and put it in the S&P 500 instead. Using the actual last 7 calendar years of returns, including the -18% year in 2022, that $100K is sitting at roughly $305K.
$305K in a brokerage account vs $215K in a house. And the renter spent $87K less getting there.
Before anyone yells: the last 7 years were one of the strongest stretches in market history. Run it on the 2000s and the house wins. This is a backtest, not a forecast, and past returns don't promise anything.
But "renting is throwing money away" is a bumper sticker, not a spreadsheet. Run yours before you sign.

If “renting is a scam” please let me know your thoughts on the following:
- Median duration of homeownership is 12 years (many homeowners spend most of their ownership paying mostly interest each payment)
- Many overlook maintenance costs, property taxes, and transaction costs
- Home equity is usually not as asset funding retirement (outside of downsizing, borrowing against, or becoming a renter)
- When excluding home equity, the median homeowner STILL has significantly more wealth than a renter
If you’re a financial advisor not analyzing every investment for your clients…
What. Are. You. Doing?
BIG ANNOUNCEMENT! 🚨 🚨 🚨
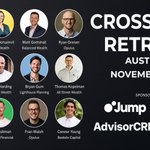
We have been keeping a HUGE SECRET. We’ve been planning the biggest surprise event for almost a whole year for financial advisors that are building the best practices in the US.
Our podcast, Advisor Freedom, has (amazingly!) exploded over the last 18 months and has been so much fun to run.
We thought the greatest way to celebrate that is to do the opposite of what every podcast seems to do (World Tours) and instead host an awesome and massive event for incredible financial advisors in Austin TX!
Soooo, we are excited to host the Inaugural Crossover Retreat!
I am obsessed with learning from other financial advisors (especially these superstars) on how they’re building their practices, growing their firms/social media reach and utilizing AI everyday.
That’s exactly what Crossover is for. Sharpening with and learning from some of the best minds in the same room.
If you want more info comment CROSSOVER and I'll send you info and event details.
Big thank you to our sponsors: @JumpAdvisorAI , AdvisorCRM , InfluenceLab and Momentum Media
Excited to explode with this year’s cohort!
@cliffcornell_ - Bone Fide Wealth
@Rianka_D - Founder, YGC Wealth
@matt_gottshall - Balanced Wealth Group
@Greiser - Co-founder, Opulus
Bryan Gum - Founder, Lighthouse Planning
@iconocapital - Founder, Iconoclastic Capital
@hardingwealth - Founder, Harding Wealth
@TakeActionCopy - Founder, Influence Lab
@TKopelman - Co Founder, All Street Wealth
Kaya Ladejobi - Founder, Earn Into Wealth
@maxpashman - Founder, Pashman Financial
@FranWalsh73 - Co Founder, Opulus
And we’re not done with surprises (👀)… Stay tuned!!!
🤖 Made with AI

I cannot get to all messages/dm's so if you want to attend/virtually attend and retreat details, you must sign up: crossoverhq.com
Totally shocked and happy for how this blew up!
I cannot get to all messages/dm's so if you want to attend/virtually attend and retreat details, you must sign up: crossoverhq.com
I spent the last 15 months hounding the best advisors who create content. In November, 12 of them are joining me in Austin.
I’ve always had a love-hate relationship with conferences. The best thing I get out of them is the conversations with other great advisors, so we decided to build a retreat to create and solely focus on those conversations.
We're calling it the Crossover Retreat, and here’s what’s on the agenda.
• A sunrise 5K along Town Lake
• Breakfast with a (super special) surprise guest speaker
• Golf
• Meals at the best restaurants Austin has to offer
• Conversing and learning with and from some awesome advisors running amazing practices
And, of course, two main sessions:
Start to Service:
How each advisor brings clients in and serves them, and the one content format that has actually driven business.
Building the Machine:
Pulling back the curtain on everything behind the scenes in ops, investment management, compliance, marketing, hiring and running the practices/firms.
Everything is set up so advisors can be open and honestly share what’s been good, the bad, and the ugly.


BIG ANNOUNCEMENT! 🚨 🚨 🚨
We have been keeping a HUGE SECRET. We’ve been planning the biggest surprise event for almost a whole year for financial advisors that are building the best practices in the US.
Our podcast, Advisor Freedom, has (amazingly!) exploded over the last 18 months and has been so much fun to run.
We thought the greatest way to celebrate that is to do the opposite of what every podcast seems to do (World Tours) and instead host an awesome and massive event for incredible financial advisors in Austin TX!
Soooo, we are excited to host the Inaugural Crossover Retreat!
I am obsessed with learning from other financial advisors (especially these superstars) on how they’re building their practices, growing their firms/social media reach and utilizing AI everyday.
That’s exactly what Crossover is for. Sharpening with and learning from some of the best minds in the same room.
If you want more info comment CROSSOVER and I'll send you info and event details.
Big thank you to our sponsors: @JumpAdvisorAI , AdvisorCRM , InfluenceLab and Momentum Media
Excited to explode with this year’s cohort!
@cliffcornell_ - Bone Fide Wealth
@Rianka_D - Founder, YGC Wealth
@matt_gottshall - Balanced Wealth Group
@Greiser - Co-founder, Opulus
Bryan Gum - Founder, Lighthouse Planning
@iconocapital - Founder, Iconoclastic Capital
@hardingwealth - Founder, Harding Wealth
@TakeActionCopy - Founder, Influence Lab
@TKopelman - Co Founder, All Street Wealth
Kaya Ladejobi - Founder, Earn Into Wealth
@maxpashman - Founder, Pashman Financial
@FranWalsh73 - Co Founder, Opulus
And we’re not done with surprises (👀)… Stay tuned!!!
How seriously should I be examining these 'leaks' of Anthropic's S1?
I want to rip it apart but how legit are they?
Then again, is Anthropic just 'accidentally' leaking their biggest financials out to get a consensus on a mkt cap and IPO price?
Looking at my outfit options today that also coincides with the biggest meeting of my career with a Family Office.
What do you guys think?
#vaspursva
🤖 Made with AI


Pro husband tip:
Ignore college football (especially if your team sucks) and tell your wife
“Let’s go to the pumpkin patch and take pictures of our daughter.”
Massive W

BIG NEWS!!!
I will not be launching any course ever!
This is a huge blessing and something my wife and I have prayed through and I’m just so excited.
There’s NO Course! No online community or discord group! NOTHING! I don’t have anything to teach you! Ever!!!
Wow, for everyone that kept encouraging me and pushing me - THANK YOU!
I was at a Buffalo Wild Wings watching this live and knocked over a waitress and three tables when he dunked this.

Your NBA ID Fan Favorites Dunk of the Year 🏆
Looking forward to more @StephonCastle slams this season!
I just built a financial planning software internally with Claude.
We were tired of not getting changes to include our models and custom positioning when talking to prospects.
Got it connected to our GitHub repo and it auto deploys in and then thru Netlify.
Github and netlify are both free...
Complete customization of all dashboards and reports. And better yet, fully integrates into our tech stack of all other softwares we use.
No more $200/m (per person!!!) to RightCapital.


"Stop complaining about home prices and interest rates, back in the 80's rates were much higher than they were today."
You're right. But you're not doing the math correctly to show what your money 40 years ago in 1986 would've bought if you took that same home and interest rate into today's dollars.
In 1986:
>Median US home price: $80K
>30Y Mortgage rate: 10.2%
>Median household income: $25K
That house cost 3.2x the typical family's income.
Now adjust that 1986 house for 40 years of inflation. It comes out to about $239K in today's dollars.
The actual median home today? $434K.
The same house, in the same dollars, costs nearly twice as much. The rate discount you got along the way doesn't come close to covering that.
Take the 1986 buyer. Put 20% down on that $239K inflation-adjusted home and keep their 10% rate. The payment is about $1,700/mo in today's dollars.
Take today's buyer. Put 20% down on the $434K median home at 7.3%. The payment is about $2,400/mo.
That's principal and interest only. (Add today's property taxes and insurance and the gap gets wider.)
So the 1986 buyer paid a 10% rate and still had a payment $700/mo cheaper than today's buyer with a "low" 7% rate. Because the rate was never the problem. The price is the problem.
A home used to cost 3x income. That was the norm for decades. Today it's 5.2x. The highest multiple on record.
And here in Austin? The median home in 1986 was $85K. That's about $253K in today's dollars. A 2,000 sq ft house in the city today runs around $615K.
The buyers who did catch 12% or 18% rates in the early 80's refinanced a few years later when rates dropped, and their small loan balance stayed small.
You can refinance a rate. You can't refinance a price.
So yes, rates were higher back then. The math still says this generation is playing the harder game.
Home prices are going to continue to fall.


Just read a Wall Street Journal article every pre-retiree should see.
A retired couple in their late 60s writes a monthly column on their first years of retirement. This month's topic: inflation.
The husband admits he's worried about money his whole life. Then he noticed something. He'd stopped worrying about inflation completely.
Prices didn't stop rising but he put together a full plan with his financial advisor and planner.
If you don't have a WSJ subscription, here's their playbook:
1. They delegated. They have a planner who keeps short-term money conservative and long-term money invested so they don't have to watch markets or panic over headlines.
2. They learned how to separate "want" from "need." His mantra when something feels overpriced: "Well then don't buy it." (Marie Kondo out there somewhere)
3. They downsized their stuff, not their life. Fewer things to buy, maintain, insure, and repair. (I've had so many convos with retirees wanting to buy the vacation home in CO when instead they should just budget $15k annually to spend a month with Airbnb and not $1.5M on a house)
4. They traded money for time. Off-peak travel, cooking at home, DIY repairs, senior discounts.
5. They built the buffer decades ago. The frugal habits from their newlywed years created the cushion that lets them stay invested and stay calm now. He says to start saving and investing more than you think you should now.
Inflation is the #1 fear I hear from people about to retire. And the fix isn't predicting prices. Gotta get the right structure with cash for the next few years, growth for the long run, matched to what you actually spend.
Article Link in the comments.

"Every advisor not using AI is going to get left behind."
I've talked to a lot of people that heard that at Future Proof, and it's 100% true.
AI has changed all admin/behind the scenes work we do now. Watch this video. This is undoubtedly my biggest work achievement ever.
I am not a technical person at all. Can't code. Never attempted to build anything but over the last 10+ months I've built our own AI Assistant that our entire team can text 24/7.
Do not want to come across arrogant but I am so freaking proud of myself and the team for finally getting this done.
I'm sure there are other tools out there that work for texting as an assistant but this was built 100% for us as a wealth management firm that deals with tons of meetings, calls, clients, prospects, emails, followups and most important: compliance.
Chewy, our AI Assistant, can't access any client PII. Just our PM board with notes and contact cards. Compliance is all tracked and recorded. We ain't playing.
Texting is how we do everything at Baskets. Now, I can literally ask "What is Manu Ginobili's favorite restaurant? And send him an email for our next meeting to make it at that location next Friday for lunch and go book a reservation."
INSANE.
We broke this 10,000 times but that's now why it does everything.
Also, for tracking everything from calls/meetings the only software that can handle and even work with AI search requests is Jump AI. Big fan of them and Parker Ence because they're the most AI advanced software by miles.
I'm a financial advisor with no coding experience that built a 24/7 texting AI Assistant connected to our whole tech stack. Ask me anything.
AI is just getting started.
"You're laughing?
Micron smashed earnings and more than QUADRUPLED their Revenue YoY and is down -2%. And you're laughing?"

Surge is right around the corner for a lot of firms and advisors. Take a great moment to BREATHE.
I hate to admit it, but I’ve entered the stage in my 30s where I’m really getting into running and I’m slowly becoming obsessed. I ran track growing up (and was horrible) but loved distance running.
There’s this component in running at the last part of a longer race where the best runners just hit another gear. Suddenly they’re separating themselves from the pack and give it everything they’ve got.
Coaches call this ’The Kick’.
Goal planning, EOY quotas, Client Review meetings, and that last mad dash into December 31st is going to take everything again.
So don’t be like me and spend so many years placing your identity into some number to hit, or how many clients you can get or please, or how someone online that you’ve never met may think of you.
Instead, do this: work as hard as you can for the service of others and for the honor/glory of Someone else.
Sometimes that means getting yourself some breaths to pull off that Kick.
The reason the best long distance runners pull off a win is because they can run at everyone’s pace while still reserving some energy. They take that extra breath and then let go.
