

Hydrocarbons barbarian. You are here for Oil & Tanker analytics #OOTT
Outside
Joined November 2019
- Tweets7.3K
- Following490
- Followers38.2K
- Likes21.6K



Oil Bandit 🛢️ retweeted

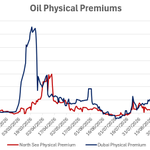
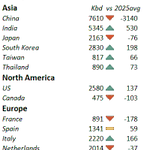
The energy security debate is shifting. Crude matters, but responsive refining capacity is a real constraint. Refiners in the US, Europe, and Africa are already running at high rates, but disruptions in Russia and the ME, along with China's policy, continue to support margins.

Oil Bandit 🛢️ retweeted

📢 Russia’s headline seaborne export volumes may look relatively stable, but beneath the surface the trade mix has shifted sharply.
💥 Following intensified strikes on Russian ports and refineries, clean product exports from Baltic terminals fell well below their historical range.
📈 At the same time, crude exports moved higher, with India absorbing a growing share of the additional barrels.
👨🏫 Our latest analysis highlights:
🔹 Baltic clean product loadings from Ust-Luga and Primorsk collapsed
🔹 Total refined product exports fell to around 1.6 million b/d
🔹 Russian crude exports climbed toward the top of their ten-year range
🔹 Crude arrivals in India rose above 2 million b/d
🔹 Russia expanded from roughly one-third to around half of India’s crude imports
📝 The result was not simply a fall in exports, but a major shift from refined products to crude, increasingly towards India.
📰 Read our full analysis at public.axsmarine.com/blog/fr…
🤖 Made with AI

Oil Bandit 🛢️ retweeted

Most likely the ~34mb US SPR will be re-tendered. But even if more US SPR releases are announced, they won’t be able to do the pace they did in May-June due to logistical constraints.


RT @ALikhodedov: WHY DID BRENT DROP TODAY? BRENT JUNE (COM6) FUTURE EXPIRY
I see many people citing "June future expiration" as the reason…
This quoted post is unavailable.
Oil Bandit 🛢️ retweeted

Dated Brent may not be $30 over futures any more, but for the next three weeks it is trading between $6.5 and $9.5:
CFDs (Rolls):
05-08/05 Jul +965 (+90)
11-15/05 Jul +875 (+135)
18-22/05 Jul +740 (+130)
Alpha.
Oil Bandit 🛢️ retweeted

perhaps a bit of fatigue...WTI total volumes on Monday were the 2nd lowest of 2026. The lowest was on Jan 2
Oil Bandit 🛢️ retweeted

A 🧵 on an often-overlooked driver of US refined product pricing: the RVO. #OOTT
(1/8)


Oil Bandit 🛢️ retweeted

Seeing a lot of posts on Jet fuel and Europe today. So just going to post some facts for UK based demand.
1. Typical yield of Jet Fuel from light sweet refineries run in UK is around 10-15%
2. UK Jet fuel demand in 2026 is around 272kbd (S&P)
3. Refining capacity is running around 700kbd-800kbd currently (S&P)
4. At est. 12% yield that’s around 96kbd Jet Fuel Production daily.
5. 272kbd - 96kbd = daily shortfall which needs to be imported 176kbd
6. 176kbd over the month is 692kt which is approximately, 7 LR2 ships
7. Currently see around 300kt-350kt imports from US. Approx 3 LR2 ships.
Photo credit platts / Kpler


Oil Bandit 🛢️ retweeted

What is the North Sea physic mkt, and how should the gap between the paper and physical markets be resolved?
Every time I post about the physical market, I see a lot of complaints about why oil prices aren't rising further. Many ppl even criticize me, claiming I’m not explaining things properly.
First, I’ll summarize the basic components of the North Sea market.
ICE Brent Futures: A financially settled paper contract used primarily for broad directional hedging and speculation without the intention of physical delivery.
EFP (Exchange of Futures for Physical): A swap that acts as a bridge, allowing a trader to convert a paper futures position into a physical cargo contract.
Forward Brent: A standardized OTC physical swap for future delivery. It represents actual oil but remains non-dated bc the exact loading schedule is not yet determined.
Dated Brent: The global benchmark price for physical crude. It is assessed daily by agencies like Platts based on actual trades of the most competitive grade within the BFOET+WTI basket, triggered once specific loading dates are confirmed (typically 10-30 days prior).
CFD: A short-term swap representing the price difference between Forward Brent and Dated Brent. It is used to plot the physical forward curve and assess whether the market is in contango or backwardation.
DFL (Dated to Frontline): A swap that links the physical Dated Brent assessment directly to the front-month ICE Futures contract, managing exposure between the physical and financial markets.
Diff (Grade Basis): The premium or discount applied to a specific physical cargo relative to the Dated Brent benchmark. Driven by crude quality, logistics, and refinery demand, this unhedgeable spread is where physical traders generate profit.
This alone should be enough. From there, I’ll explain how the gap between the paper market and the physical market actually closes.
A massive divergence between Dated Brent (physic) and ICE Brent futures (paper) typically indicates acute near-term physical tightness relative to forward expectations.
If Dated Brent remains at $120-130/bbl leading into the expiration of the front-month ICE Brent futures contract (currently around $100/bbl), the futures contract must converge toward the physical price.
The convergence is not optional; it is mathematically enforced by the exchange's settlement rules and market arbitrage. This operates through three primary mechanisms:
1) Cash Settlement via the ICE Brent Index
ICE Brent futures are cash-settled upon expiration and do not involve physical delivery. Expiring contracts are settled against the ICE Brent Index.
The Index is a calculated average of trading activity in the relevant physical Forward BFOET(Brent, Forties, Oseberg, Ekofisk, Troll)+WTI Midland market during the final trading days of the futures contract.
Bc Forward Brent and Dated Brent are intrinsically linked, a physical market sustaining $130 will generate an ICE Brent Index near $130.
Consequently, any futures positions left open at expiration are forcibly settled at this higher Index price.
2) The Arbitrage Channel (EFP Mechanism)
If a $30 spread exists between paper and physical markets, traders will immediately exploit the arbitrage using the EFP mechanism.
Traders buy the undervalued ICE Brent futures at $100 and simultaneously sells a physical Forward Brent cargo at $130. They execute an EFP to swap their long paper futures position into a long physical Forward position.
The newly acquired long physical position cancels out their short physical position, locking in a profit (minus the EFP swap cost). To execute this arbs on a large scale, traders must aggressively buy ICE futures. This massive purchasing volume forces the futures price up until the gap closes and the arb window is eliminated.
3) Forced Short Covering
Market participants holding short positions in the ICE Brent futures market face extreme risk if the physical market disconnects to the upside.
Knowing the contract is destined to cash-settle against a $130 physical Index, paper shorts cannot afford to hold their $100 positions into expiration.
They are forced to buy back their futures contracts to close their positions before the expiry date.
This forced buying—often resulting in a short squeeze—accelerates the upward momentum of the ICE futures price, driving it into alignment with the physical market.
Through the combination of final index settlement and active EFP arbs, the paper market is structurally tethered to physical reality as expiration approaches.
#oott #iran


Oil Bandit 🛢️ retweeted

The market bias is to heavily pricing supply disruptions at the very prompt. Look at Dated (pricing 10-30 days ahead) versus June ICE. Look how May-June TI spreads were pricing versus June-July Brent.
This will provide opportunities if the ceasefire breaks down (likely imo).


Oil Bandit 🛢️ retweeted
I have never seen this before:
Prompt physical (Dated) Brent is trading almost $30 over the front month futures:
AALPHA LUNCHTIME MARKS 02/04/26 1230 BST
CFDs (Rolls):
07-10/04 Jun +2920 (+500)
13-17/04 Jun +2420 (+520)
20-24/04 Jun +1900 (+550)
27-01/05 Jun +1350 (+410)
Oil Bandit 🛢️ retweeted
New word of the week: "Force majeure"
o̵f̵f̵ ̵r̵a̵m̵p̵
̵k̵i̵n̵e̵t̵i̵c̵
̵H̵o̵r̵m̵u̵z̵
Oil Bandit 🛢️ retweeted

Why is jet fuel the most stressed barrel right now?
1⃣Jet fuel has very specialized tank storage requirements. Therefore there is not much stored, unlike many other products like diesel and gasoline.
2⃣You can only produce mainstream jet fuel from the refinery aside from a mere ~1% sustainable aviation fuel globally
3⃣Asian refineries are reducing runs as their crude is stuck at the Straits of Hormuz. AG refineries have also been hit by the attacks.
4⃣With oil production also shutting in, longer run cuts are expected.
4⃣Lack of storage + Lower supply from refining runs = Recipe for disaster
Travel is going to get a whole lot more expensive.
#oott


