

Finance for the mass. EX - Two Sigma
New York - TLV
Joined September 2025
- Tweets3.8K
- Following124
- Followers353
- Likes166






The Financial Godfather retweeted

A few people have questioned whether my $ANT compute spending projections are realistic.
Frankly, I get why people are having a hard time accepting these. The numbers are absolutely staggering both on scale and growth rate. We're talking about tens of billions of dollars in annual compute spending, growing at an unprecedented pace.
But you actually don't have to rely entirely on growth projections for this. Anthropic's own S-1 gives a pretty good indication of how much compute capacity the company expects to need based on its total commitments and payment obligation schedule.
As seen in the amended S-1, Anthropic has nearly $900B in total commitments. Of these, $315B are contractual obligations. The S-1 also lays out the payment schedule for these contractual obligations, including $29.2B in 2027 and $44.4B in 2028. That's BEFORE accounting for the much larger pool of commitments without fixed payment schedules.
Now, contractual payments aren't necessarily the same as recognized compute expenses. But given that compute is the largest expense category on the company's P&L, they're a very useful indication of the scale of infrastructure spending Anthropic is preparing for.
I think my original compute spending estimates are not only reasonable, but potentially conservative, particularly for 2027 and 2028.
The only reason these numbers look aggressive is because Anthropic's growth is aggressive.
Demand for AI infrastructure has never been stronger.
Please consider commenting or sharing if you enjoy this type of content.


The craziest part about neoclouds ($NBIS , $IREN, $CRWV) crashing is the timing.
Stocks crash. That's normal and healthy market behavior. But what's remarkable here is that neocloud are collapsing precisely as their underlying market is experiencing explosive growth at an unprecedented pace.
Part of the reason for this crash is a distorted supply/demand view.
Neocloud and hyperscaler earnings gave us a glimpse into the supply side of the equation. That's what the street is focused on now. But the Anthropic's S-1 gave us the first look into the demand side, and that's what many investors are completely missing.
In Q2'26, $ANT was spending $5.6B on compute to support $11.6B in revenue. By Q3, revenue had climbed to $17B, and compute costs grew to $9.9B.
That's a 77% increase in compute costs in a SINGLE quarter, outpacing even revenue growth.
Understanding the source of growth makes this even more interesting.
Much of this growth is coming from enterprise customers, which usually have a significant step up in usage after joining.
So in Q2, Anthropic had 6,000 customers spending more than $100K annually. By Q3, that number had nearly doubled to 11,900. By the end of Q4, it's expected to approach 18,000.
That's potentially a tripling of large enterprise customers in just six months.
By my estimates, these additional customers alone will require at least $3B in incremental compute spending, bringing Anthropic's FY26 compute bill to roughly $31B.
By 2027 compute spending will be AT LEAST $55B, assuming revenue growth slows dramatically (after three consecutive years of roughly 10x growth). Very likely, compute will be MUCH higher because there is no evidence to show that growth is actually slowing this much.
So Anthropic's compute needs are set to nearly double AGAIN next year, while existing capacity is already stretched to its limits.
Where is all this additional compute going to come from?
AI labs cannot grow without compute. They can sign all the customers they want, but without the infrastructure to serve them, that revenue simply cannot materialize.
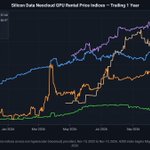
This is precisely why $ANT is reportedly willing to pay $SPCX as much as $50M per MW of compute capacity, roughly 3x the prevailing one-year spot rate.
Because the alternative is far worse: They either secure the capacity, or they stop growing.
This is the disconnect I find so extraordinary. It's fine for stock to drop in price. It's just odd for that to happen in the middle of this historic demand explosion.
Please comment and share if you enjoyed this read.


The Financial Godfather retweeted

$NBIS team or anyone that works at Nebius, plz tell the IR team that you need to do something like this please!
Being able to see the stages at which sites will be at whether its cooling or handover etc, would be great visibility for investors and showcase your strength(international expansion and execution)
$IREN set the bar here.
@nebiusai

The Financial Godfather retweeted

$IREN
For anyone wondering which phase their data centers are currently in. Big up for IREN’s transparency this quarter!

The Financial Godfather retweeted

It's... almost as if the conservative Republican cohort was just fearmongering and spreading BS as usual. This is *good* for companies like $IREN.


The Financial Godfather retweeted

$IREN: This is fundamentally what the bears don't understand.
A neocloud bear opens with cost of capital, gets shown that contracts + prepay + GPU loans solve it, then pivots to "yeah but you can't capture spot pricing."
Bruh.
That's not a rebuttal; that's moving from "it won't survive" to "it won't be a lottery ticket."
That's literally the trade I'm taking lol and the whole reason it's asymmetrical. Also why I refuse to model the upside.
But like, you're proving my point.
The Financial Godfather retweeted
$NBIS $IREN $HUT
Are neoclouds dead? I don’t think so.
Using reasonable assumptions, Blackwell seems to have a payback period of roughly 3 years, even after CapEx and operating costs.
The economics look even better for Vera Rubin.
The market may be repricing the sector aggressively, but that’s different from saying the business itself is no longer viable.
At least not yet.
omething to keep in mind as panic sets in.

The Financial Godfather retweeted

$DGXX and @michelamar3 once again delivering on their promises. Using non-dilutive debt financing is the most shareholder-friendly way to build out the Alabama AI campus.
Debt is debt, but when Goldman Sachs is willing to syndicate $200M behind DigiPower X’s execution, that says a lot.
It’s only a matter of time before the market starts giving this company the attention and respect it deserves.
DigiPower X does not deserve its current valuation.

$200 MILLION DEBT FINANCING COMMITMENT | DIGI POWER X ($DGXX)
We have announced a US$200 million debt financing commitment, with financing syndicated by Goldman Sachs, to support completion of our 40 MW Alabama AI data center campus and advance our AI infrastructure strategy.
Key updates:
• $200M Commitment: Supporting campus completion while aiming to limit shareholder dilution.
• Alabama AI Campus: Phase 1 targeted for December 2026; Phase 2 expected March 2027.
• Financial Position: Approximately $135M in cash and $153M in year-to-date capital expenditures.
• @Neocloudz : Advancing our AI token factory strategy, including plans for NVIDIA GTC Berlin.
• Expansion: Progressing AI infrastructure opportunities in New York and Silicon Valley.
From power to compute, we're building the foundation for scalable enterprise AI infrastructure.
Financing remains subject to closing conditions.
Read the full release:
digipowerx.com/press-release…
#DGXX #DigiPowerX #AIInfrastructure #NeoCloudz

The Financial Godfather retweeted
Don't get too stuck on share prices on companies that are serial dilutors.
Take $IREN for example. Last time it traded at $35, it was worth under $10B. Today, at the same $35, it's worth around $13.8B.
Shares outstanding went from 283M (EOY 2025) to 394M (Now, per 10-K Annual Report). That's why dilution matters.
I'm not saying the dilution was bad or unnecessary. The point is that "it's back to $35, so it's cheap" doesn't mean much without looking at the market cap.
Same share price but a very different valuation.
The Financial Godfather retweeted

The Financial Godfather retweeted
The S&P is only 3% from all time highs but if you read Twitter you’d think we’re in the middle of the 2008 financial crisis
The Financial Godfather retweeted
Well. I wouldn’t touch $CRWV. Their balance sheet is not balanced sh*t.
The Financial Godfather retweeted

Unless Antrhopic wants to wait years, they have to turn to IREN, because the others have already rented almost everything, $CIFR only has 70MW to rent, $NBIS is late on a contract, $CRWV has no MW, $APLD is all rented, the only one with SO MANY MW to rent NOW is $IREN


The Financial Godfather retweeted
Correction, forgot they would actually have to pay off the debt lol. Would still be about $300M in annual cash flow...
The Financial Godfather retweeted

𝐓𝐡𝐫𝐞𝐞 𝐋𝐚𝐲𝐞𝐫𝐬. 𝐎𝐧𝐞 𝐂𝐨𝐦𝐩𝐨𝐮𝐧𝐝𝐢𝐧𝐠 𝐀𝐝𝐯𝐚𝐧𝐭𝐚𝐠𝐞. 𝐓𝐡𝐞 𝐈𝐑𝐄𝐍 𝐓𝐡𝐞𝐬𝐢𝐬.
There's been a lot happening at IREN recently.
Expansion across North America, Europe and Asia-Pacific.
The NVIDIA partnership.
The Mirantis acquisition.
New GPU deployments.
New customer discussions.
A growing global footprint.
Underneath all of it is a fairly simple view of where the world is heading, and a deliberate strategy for how we position IREN within it.
That strategy is built on three layers. Together, they compound into a structural advantage that gets harder to replicate every quarter we execute.
Layer 1: Physical infrastructure. Power, land, substations, data centers, cooling. The foundation that everything else sits on.
Layer 2: Compute infrastructure. The GPUs, servers and networking that go inside those buildings. Deployed at scale. Generating revenue. Building execution track record.
Layer 3: Software and operational capability. The orchestration, deployment tooling and enterprise expertise that makes the first two layers work harder for customers, and opens the door to a broader, higher-value market over time.
Layers 1 and 2 are where the overwhelming majority of IREN's value is being created today. Layer 3 is where that advantage compounds further over time, but only because Layers 1 and 2 are built, owned and controlled at scale by IREN, not subscale nor contracted from a third party.
Think of Amazon. They didn't win e-commerce by building a great website. They won it by controlling the fulfilment infrastructure at a scale nobody else could replicate. The foundation you don't control becomes the ceiling on your business.
That is exactly how we think about IREN. The physical infrastructure - the land, the power, the substations, the data centers - is owned and controlled by us. The compute deployed into it generates the revenue and execution track record. And the software, orchestration and enterprise capability we are more methodically building on top is what turns the total product into a vertically integrated AI Cloud platform that compounds over time and deepens into a competitive moat.
AI is still early. The bottleneck is increasingly physical. And we have spent eight years building the foundations.
The Financial Godfather retweeted

seems costly for $NBIS, and others without secured power... an extra ~$10B/GW expense in fuel cells alone. On top of obvious, third-party execution risks.
$IREN does not have this expense or these additional risks... and also saves a ton of money NOT paying rent/colocation fees because it owns and fully controls their sites.
got $IREN?


The Financial Godfather retweeted

$IREN is hiring a Night Construction Supervisor for Sweetwater! That’s not a casual posting — that’s 24/7 construction mode. With the $NVDA x $IREN strategic partnership targeting up to 5GW of DSX-aligned AI infrastructure, the AI factory buildout looks like it’s about to crank up fast.
Sweetwater is getting real.

The Financial Godfather retweeted

I have never seen a company refute every single bearish thesis in one quarter as $IREN did.
Insane international market expansion (Europe + Australia (1) + AI cloud software wing (FCF positive) through shares only (2) + $NVDA using $IREN services as a customer like $MSFT and believe it or not, through Mirantis (3)🧐